
Ovintiv (OVV) Stock May Be Undervalued Following Its Logan Energy Deal
Ovintiv has delivered a strong multi year share price run, so the drop in recent weeks leaves investors asking whether the current valuation is still in line with what its earnings can support. With the stock now reflecting both that history and fresh deal activity, the question is how much of the earnings story is already priced in.
- Over the past 5 years, Ovintiv has returned about 87.5%, which puts real weight on whether its earnings justify that kind of long haul performance.
- The agreed Logan Energy acquisition, at roughly US$890m, may support future earnings power by adding production, acreage and potential cost savings that affect how investors think about Ovintiv's profit base.
- Your read on Ovintiv is one view; the desks covering it have another. See what analysts think Ovintiv's shares could be worth.
The issue now is whether Ovintiv's current share price is reasonable when set against the earnings it already generates and what investors expect those profits to look like in future.
If questions about Ovintiv's earnings power have you reassessing the whole energy space, a focused stock screen can be a useful second lens alongside this one, starting with 42 high quality undervalued stocks.
Does Ovintiv Look Undervalued on Earnings?
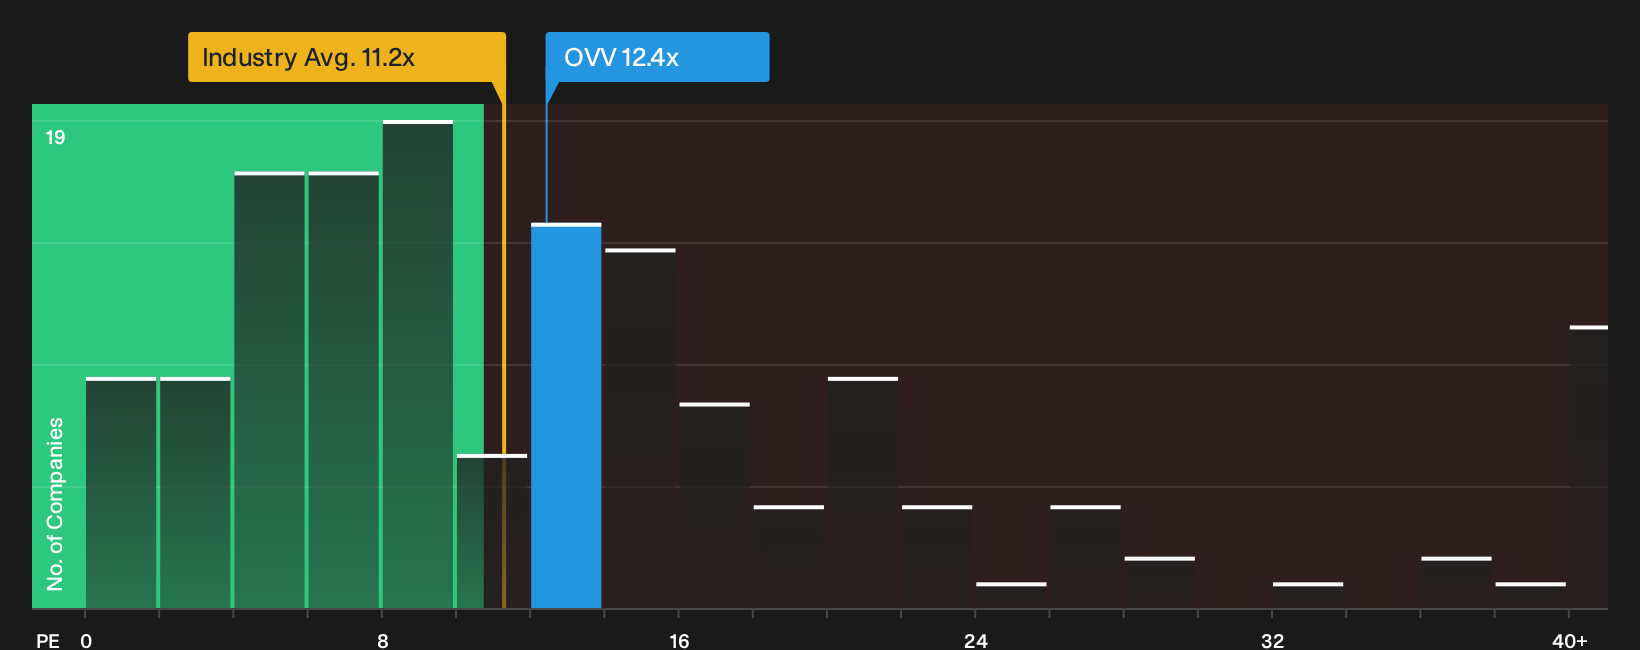
The P/E ratio fits Ovintiv because earnings are a key yardstick for established oil and gas producers. Ovintiv trades on a P/E of 12.4x, compared with an Oil and Gas industry average of 11.2x and a peer group around 15.0x. That leaves the stock priced slightly above the wider sector but below many direct comparables. This suggests investors are paying a modest premium to the sector for its earnings, yet not a full peer level tag.
The fair value model, which looks at Ovintiv’s growth profile, profitability, size and risk, points to a higher P/E than where the shares change hands today. On that framework, the current multiple screens as undervalued. Because the Logan Energy deal is framed as accretive to key financial metrics, the fact that Ovintiv still trades below this tailored P/E yardstick signals that the market is not fully reflecting that deal narrative in the earnings multiple. Explore the numbers behind Ovintiv's P/E valuation.
The Ovintiv Narrative: What Would Justify Today's Price?
Narratives for Ovintiv pick up where the valuation puzzle leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the stock to be worth significantly more or less than today’s price, and they sit on Simply Wall St’s Community page. Rather than relying on a single P/E or one fair value output, each scenario sets out its own assumptions so you can compare those expectations with Ovintiv's actual results as they arrive.
One of the top community narratives on Ovintiv: 25% undervalued
"The current valuation suggests the market is cautious on Ovintiv, even with its deep premium inventory and low leverage near $3 billion of net debt…"
Discover why this Narrative puts Ovintiv at 25% undervalued.
Ovintiv's price is only one piece of the decision
Valuation tells you what the market pays for Ovintiv today. Analyst projections for revenue, profits and cash flow a few years out offer a separate yardstick that can shift how you see that price. Explore where analysts expect Ovintiv to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com