
3 Canadian Value Stocks To Own In November 2026
Asian markets have been hit hard by the recent tech and AI selloff, and plenty of Canadian stocks have been dragged down with them even when their core cash engines look intact. When prices fall faster than the underlying cash flow outlook, patient investors sometimes get a window to consider quality businesses at lower prices. This article highlights three Canadian stocks that currently screen as undervalued on cash flows.
The stocks highlighted below are just a starting sample, and the full screen on Simply Wall St surfaced 3 more Canadian companies with equally compelling cash flow stories that are not covered here. To identify and analyze those additional ideas for yourself, head straight into the Undervalued Stocks Based On Cash Flows screener.
Stantec (TSX:STN)
Stantec is a global design and consulting group focused on infrastructure, buildings, and environmental projects, with a major role in long term water and municipal engineering programs that can support predictable, contract backed cash flows.
Stantec earns about CA$3.6b from the United States, CA$1.7b from global work and CA$1.6b from Canada, and the stock has a market value of roughly CA$12.4b.
Recent large acquisitions such as Page, Cosgroves and Ryan Hanley have significantly expanded Stantec's presence in the U.S., New Zealand and Ireland.
The key consideration for investors is how one quiet shift in profitability on that growing backlog influences future cash generation.
That shift in profitability is exactly what the full narrative for Stantec unpacks in detail, spotlighting where cash generation could be quietly accelerating or stalling next.

Suncor Energy (TSX:SU)
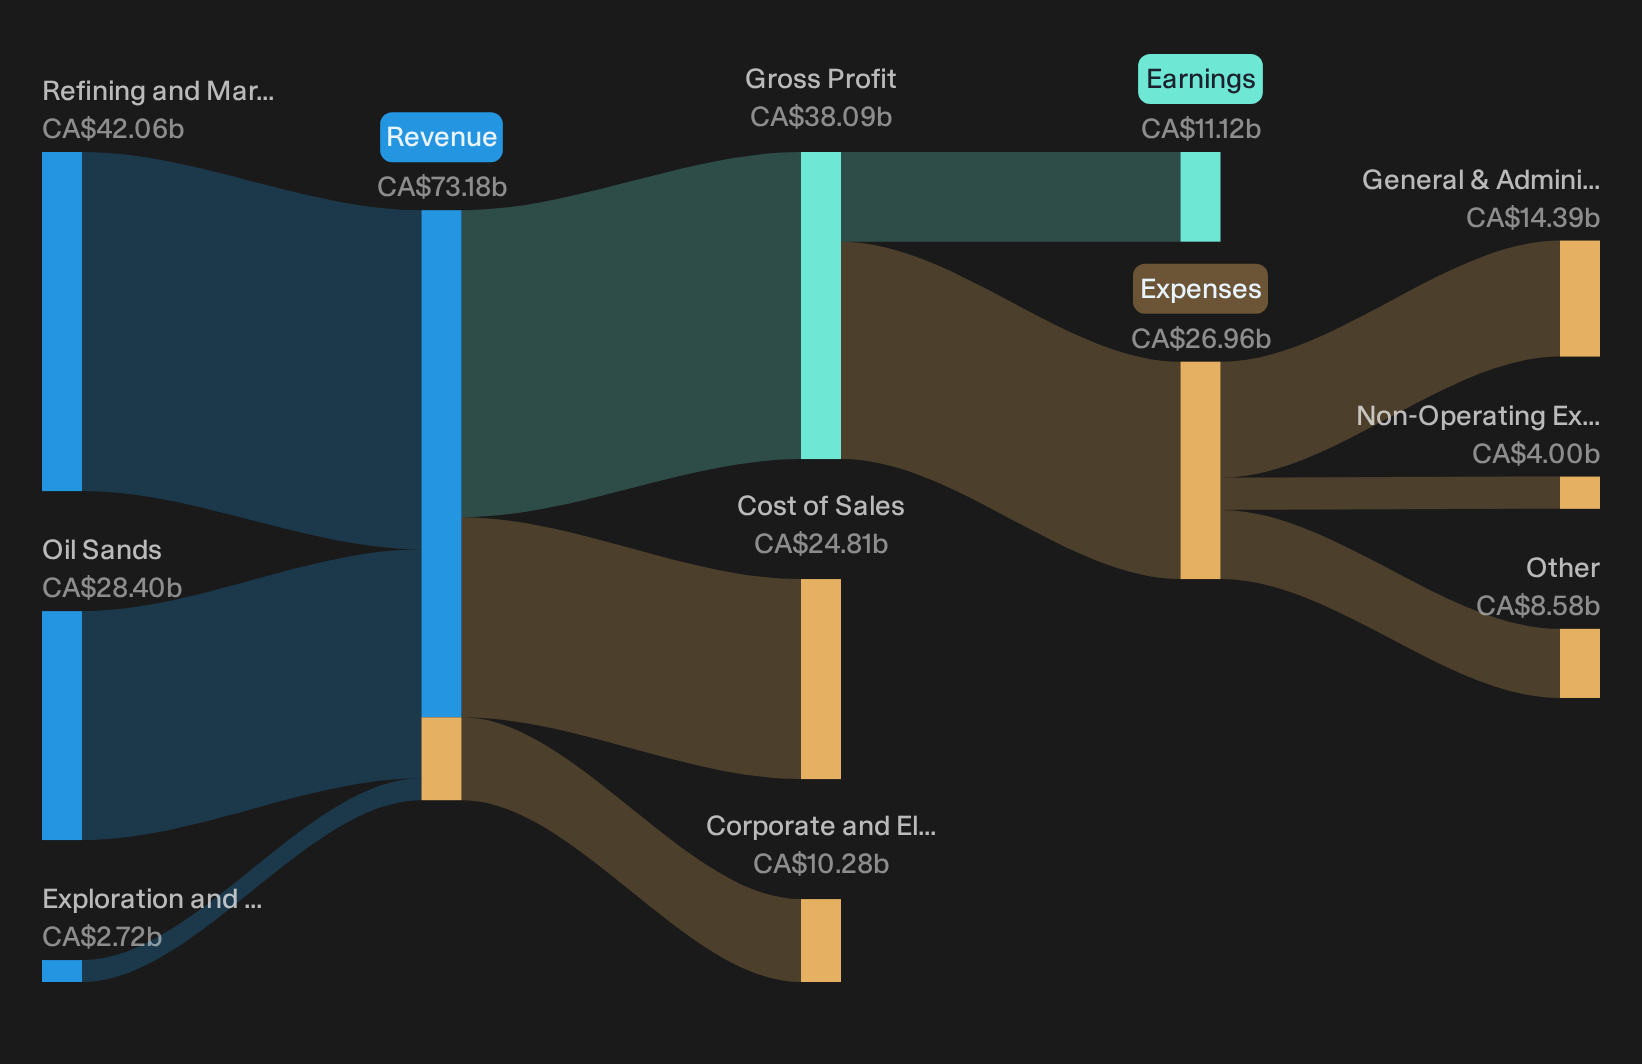
Suncor Energy is an integrated energy producer that turns Canadian oil sands bitumen into refined fuels and petrochemical products, which ties it closely to the screener’s focus on cash flow. It generated about CA$28.4b from Oil Sands and CA$42.1b from Refining and Marketing, and has a market value near CA$116.1b.
Suncor Energy adds a different flavor to this cash flow focused list, because the heavy oil sands projects feeding its refineries can generate sizeable, long-life cash streams when they run well. The next quote focuses on that point.
Reliance on very high utilization of existing oil sands and refining assets, including refinery runs consistently at or above 100% and upgrader utilization above 100%, leaves little unused capacity to offset unplanned outages, which could pressure volumes and compress margins if reliability slips from current record levels.
What happens to Suncor Energy’s valuation gap if a single key assumption in that high utilization cash engine stops holding perfectly steady?
If that question is front of mind, the full narrative for Suncor Energy shows where Suncor Energy's cash engine could be quietly decoupling from headline utilization risk.
Imperial Oil (TSX:IMO)
Imperial Oil is a long established Canadian energy group that links exploration and production with refining and chemicals, and its upstream oil, gas and bitumen operations are the key connection to this cash flow focused screener. It generated about CA$18.2b from Upstream, CA$61.7b from Downstream and CA$1.5b from Chemical activity, and the stock is valued at roughly CA$84.3b.
Imperial Oil gives this cash flow focused list some real heft, because the upstream wells that feed its refineries and chemical plants help anchor the long life production streams at the heart of the theme.
Ramped up solvent assisted SAGD at Cold Lake, with Grand Rapids producing above 20,000 bpd, Leming SAGD moving toward 9,000 bpd and the planned 30,000 bpd Mahihkan start up in 2029, points to a production mix shift toward lower unit cash costs that can support revenue and net margin improvement.
What really decides how far that kind of production mix shift can carry Imperial Oil is how one less visible cost pressure evolves in the background.
That quiet cost lever is exactly where the full narrative for Imperial Oil shows whether Imperial Oil's cash engine is quietly accelerating, stalled, or masking an even stronger earnings mix shift.

Seeking Alternatives Before The Crowd
Fresh ideas move first. By the time momentum is flying, the best entry points can be gone. Scan these curated shortlists while they are still under the radar for now and consider them before they become widely followed.
- Target steady payout potential by reviewing a curated group of income opportunities in the 3 dividend fortresses before yields change or attention shifts to the strongest options.
- Look for underfollowed opportunities among the 7 high quality undiscovered gems that still trade quietly while fundamentals develop and institutional money has not fully focused on them.
- Prepare for potential shifts in infrastructure and energy trends with the 16 nuclear energy infrastructure stocks that highlights operators tied to long dated build outs while headlines remain limited.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com