
Transcat (TRNS) Could Be 4% Undervalued As Earnings Beat Lifts Outlook
Transcat (TRNS) just paired an earnings beat with a higher outlook for fiscal 2027 service organic revenue, after strong second quarter results in both its Service and Distribution operations caught investors’ attention.
That stronger outlook has arrived after a powerful run in Transcat’s shares, with a year-to-date share price return of 75.61% and a 1-year total shareholder return of 73.01%, even though the stock fell 7.17% on the day. It remains up 11.78% over 30 days and 7.81% over 90 days, which points to positive momentum that is now being tested by how investors read the latest earnings beat, higher debt for acquisitions, and the upgraded service growth targets.
Scan stocks with similar momentum and earnings upgrades by running through the hand-picked 42 high quality undervalued stocks that combine solid fundamentals with pricing that may still offer potential for gains.
Transcat now appears to be a stronger and more focused service platform, yet the share price has already risen significantly on that story. The key issue is whether the current valuation still provides sufficient compensation for the risks being taken.
Most Popular Narrative: 4% Undervalued
Transcat is being framed as modestly undervalued, with a narrative fair value of $104.33 against the latest close at $100.38, which puts the recent share price surge in context rather than calling it excessive.
Ongoing investments in operational excellence, including Lean initiatives, pricing analytics, and AI-enabled process improvements, are intended to raise Service productivity and support higher Service gross margins. These efforts can flow through to stronger earnings over time.
See why 2 investors see Transcat as 4% undervalued.
Result: Fair Value of $104.33 (UNDERVALUED)
Still, Transcat’s reliance on acquisition-fueled expansion and recent gross margin pressure in both Service and Distribution could quickly challenge that modest undervaluation story.
Find out about the key risks to this Transcat narrative.
Another View: Transcat Looks Expensive On Sales
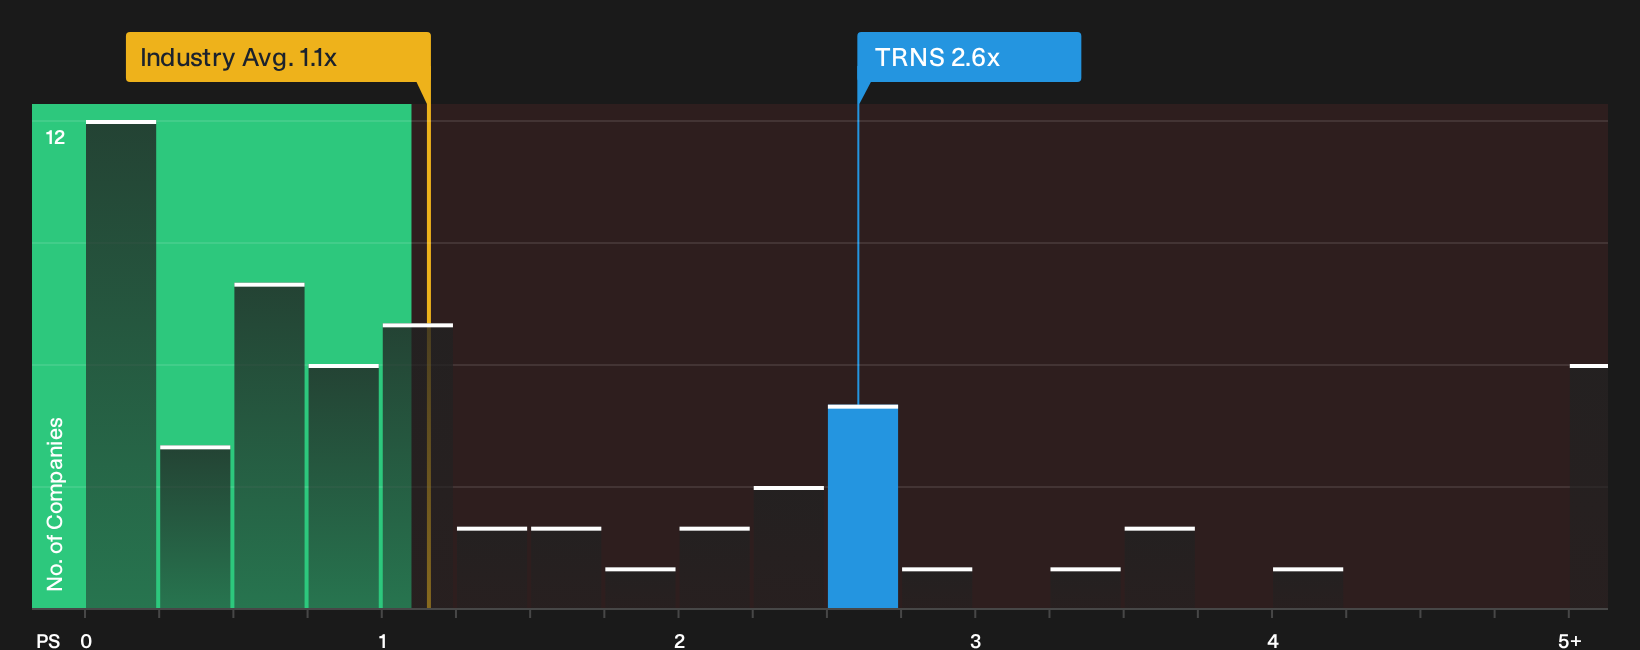
On a simple sales multiple, Transcat tells a tougher story. The stock trades on a P/S of 2.6x while both the US Trade Distributors industry and peer group sit closer to 1.1x to 1.6x, and the fair ratio points to 1.1x. That gap leans toward valuation risk rather than a clear bargain, so which story do you trust more right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Transcat’s valuation and expectations can pull opinions in opposite directions, so scan the data, move promptly, and weigh both the upside and the risks through the 1 key reward and 3 important warning signs.
Looking for more Transcat-sized opportunities?
If Transcat has you rethinking what is possible in your portfolio, do not stop here. Use focused stock lists to spot other opportunities before the crowd moves.
- Target resilient balance sheets and cleaner fundamentals by zeroing in on companies from this list of solid balance sheet and fundamentals (25 results).
- Hunt for quality at a reasonable price by scanning the 21 high quality undiscovered gems that may not yet be widely followed.
- Prioritize stability and capital protection by reviewing a 32 resilient stocks with low risk scores that aims to limit unpleasant portfolio surprises.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com