
Missed ASML's Run? What Holders Had To Believe
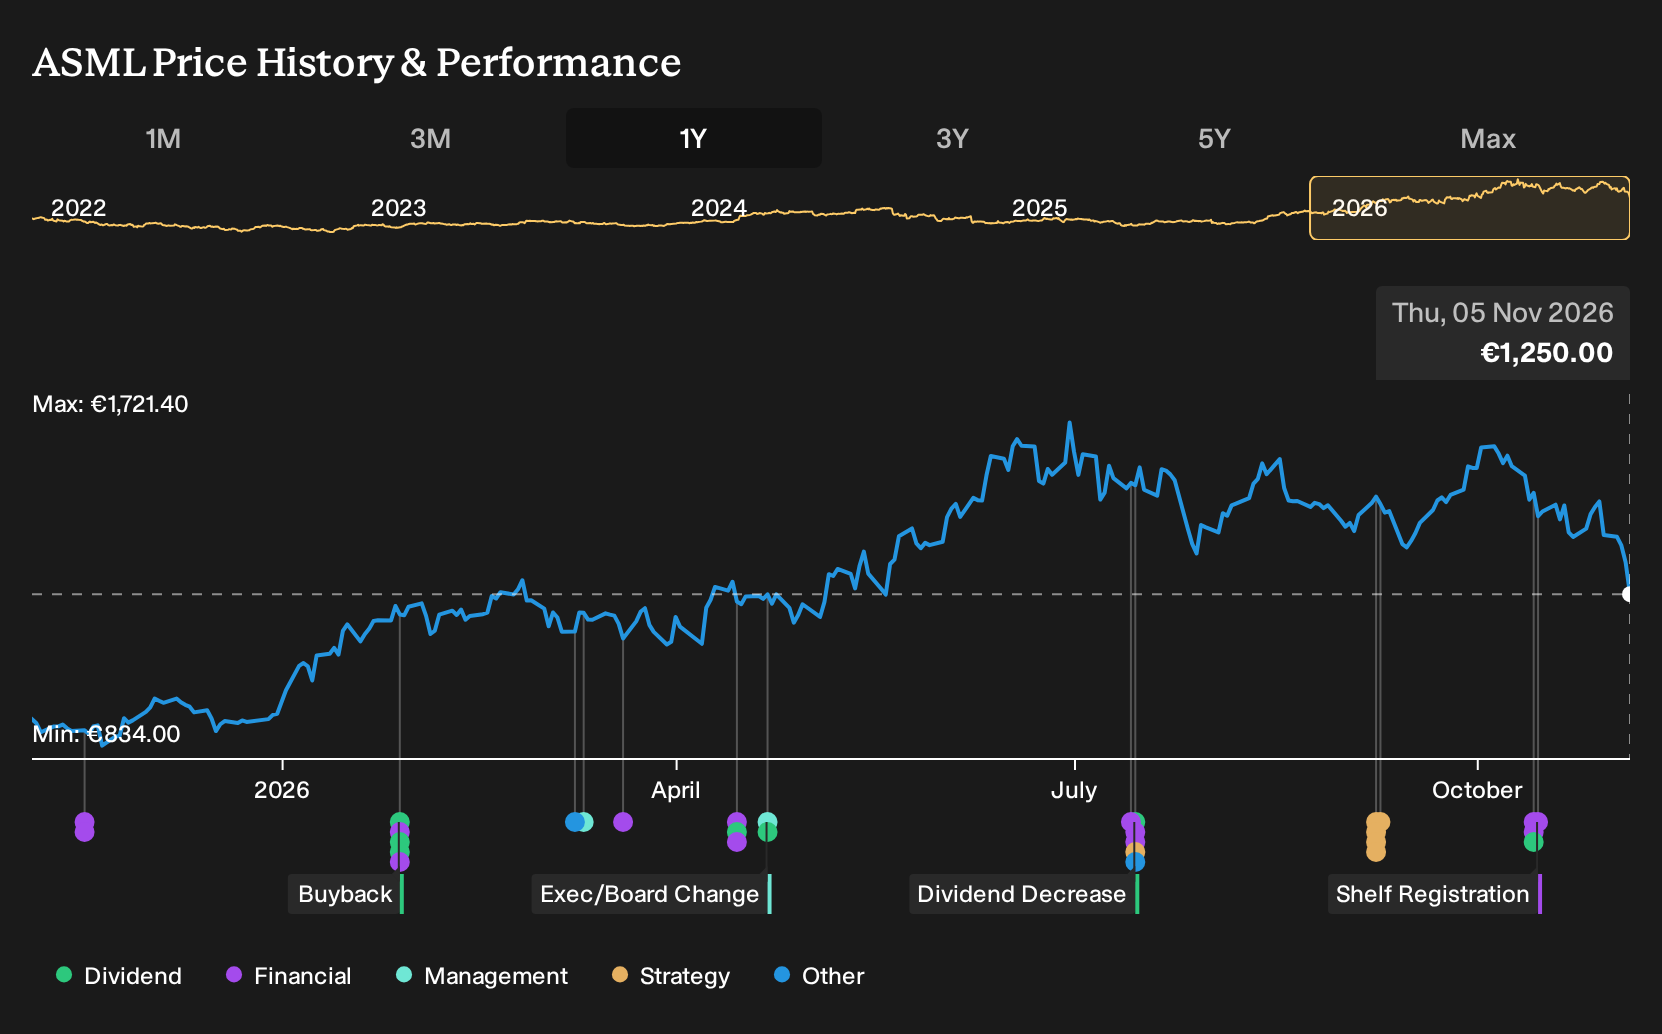
If you had put money into ASML on 5 November 2025 and simply sat on it for a year, the outcome was hard to ignore. For ASML shareholders, the return over the past year was 40.5%, including dividends. That result now sits alongside headlines about AI chip demand, new export controls and fresh record quarters. If you were weighing ASML back then, what exactly were you trading off between monopoly power on one side and rising geopolitical and competitive risk on the other?
ASML has already moved. Pinpoint other ways to investigate the theme among 53 AI infrastructure stocks.
The Argument You Would Have Been Weighing Up On ASML
The shares cost €907 at the start of the period, and anyone looking at ASML then had two very different stories to consider.
The bullish narrative pointed to a Fair Value of €1,000, a rough estimate of what the stock might be worth if revenue grew 17.3% a year and profit margins stayed near 29.3% over five years.
The bearish view suggested Fair Value of €769, based on assumptions of 7.2% annual revenue growth and a key risk that tighter export controls and geopolitical shocks could disrupt sales and margins.
What The Results Changed In The ASML Argument
ASML went on to report Q3 2026 revenue of €11.662b and net income of €4.960b, up from €7.516b and €2.124b in Q3 2025, with net margin rising from 28.3% to 42.5%. That strength leaned toward the optimistic case that assumed high profitability, although fresh export control headlines and new Chinese lithography capacity kept the geopolitical and competitive risks in play. Overall, the evidence cut both ways.
The key assumption that got tested was pricing power in a constrained supply chain. For any other chip equipment stock, you would now track whether higher orders and tight capacity actually show up in both revenue and net margin, rather than just in commentary about AI demand.
What ASML's 40% Run Already Prices In
ASML now trades at €1,250, up 40.5% over the past year. The selected Narrative sets its Fair Value below that level, arguing the share price already bakes in a lot of good news about the business.
The Narrative highlights extraordinary competitive strength, then asks what has to keep working perfectly for this valuation to hold. In particular, it focuses on the idea that elevated AI driven chip spending and EUV intensity will persist long enough to justify today’s terms.
"The problem is not ASML. The problem is the price investors are being asked to pay for it."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 32% below our estimate - builds out coconut based drinks as they shift from niche shelves to mainstream fridges.
- Company 2 - 23% below our estimate - adds advanced packaging and wet cleaning tools as chipmakers retool lines for AI driven designs.
- Company 3 - 27% below our estimate - tightens costs and reshapes the loan book toward secured mortgages and conservative gold lending.
Three companies from the same screener. Open the full list of 211 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com