
Has GE HealthCare Technologies (GEHC) Risen Above Fair Value On Earnings?
GE HealthCare Technologies has rallied hard in recent weeks, and that kind of move naturally raises a simple question for investors who care about valuation. Is the current share price in line with what the company is earning today, especially after a run like this?
- The stock has climbed 29.3% over the past month, which puts fresh focus on whether recent enthusiasm is fully grounded in its earnings power.
- Recent earnings news, including stronger profitability metrics and new investments in imaging and AI-related capabilities, can influence how sustainable investors think future margins and cash generation may be.
- There is a second opinion on GE HealthCare Technologies worth weighing. See what analysts think GE HealthCare Technologies's shares could be worth.
For investors, the debate is whether GE HealthCare Technologies' recent share price strength is adequately supported by the earnings the business is currently generating.
If you are weighing whether GE HealthCare Technologies' 29.3% one month move matches its earnings, it can help to compare it against a wider group of 42 high quality undervalued stocks.
Is GE HealthCare Technologies a Bargain on Earnings?
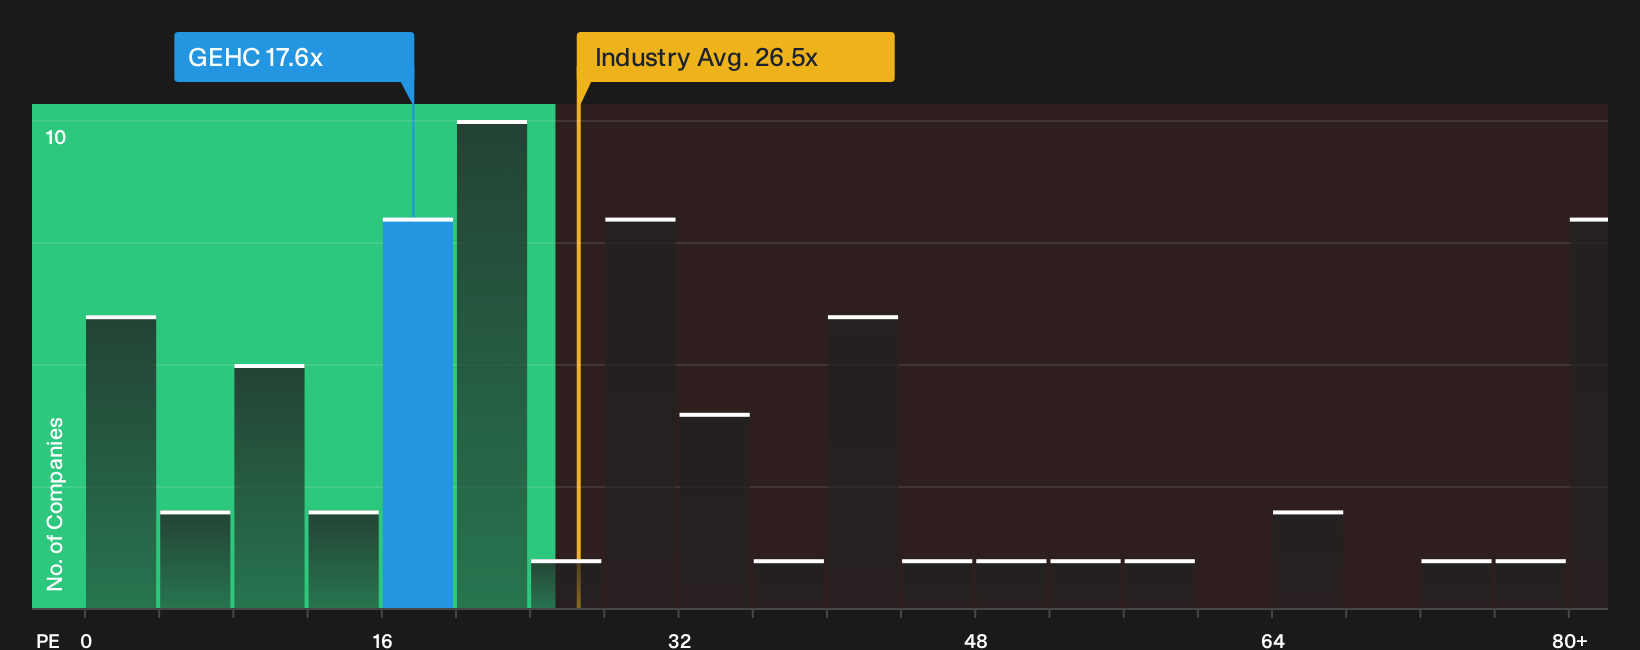
The P/E ratio fits GE HealthCare Technologies well because earnings remain a key focus for investors in established medical equipment companies. At roughly 17.6x earnings, the shares trade at a lower multiple than both the wider medical equipment industry on about 26.5x and the peer group average near 33.2x. That places the stock on a lower earnings tag than many comparable businesses in the sector.
The bespoke fair multiple for GE HealthCare Technologies, which folds in its growth outlook, profitability profile, scale and risk, sits above the current P/E. Because of that gap, the shares screen as undervalued on this earnings yardstick. Because GE HealthCare recently raised its 2026 outlook after stronger results and deal activity, the fact that the P/E still trails this tailored benchmark suggests the latest good news has not fully closed the valuation gap in this framework. Explore the numbers behind GE HealthCare Technologies's P/E valuation.
The GE HealthCare Technologies Narrative: What Would Justify Today's Price?
Narratives pick up where the P/E comparison leaves off for GE HealthCare Technologies by spelling out what path for growth, profitability and earnings would need to play out for the current share price to look too low or too demanding. Each storyline on Simply Wall St's Community page links a fair value estimate to a particular mix of potential catalysts and key risks, so you can track which version of events is actually unfolding over time.
Community views on GE HealthCare Technologies are split between those who see more upside left in the recent story and those who think a lot is already reflected in the price.
Bull case: roughly fairly valued
"The focus on expanding recurring revenue, particularly in areas like digital solutions and advanced visualization, now includes multi year equipment plus service alliances such as the approximately US$500 million Catholic Health Care agreement and rising service backlog..."
Discover why this Narrative puts GE HealthCare Technologies at roughly fairly valued.
Bear case: 15% overvalued
"While the company is bringing a broad wave of new CT and MR systems to market, the long lag between regulatory clearance, order conversion and site readiness means much of the expected revenue is pushed into 2027 and beyond..."
Explore why this Narrative puts GE HealthCare Technologies at 15% overvalued.
GE HealthCare Technologies: why the price is only half the story
GE HealthCare Technologies passes several valuation checks, yet the broader review process has also flagged specific concerns that thoughtful investors may want to weigh alongside the numbers. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com