
Helios Towers (LSE:HTWS) Lifts Medium Term Targets, Is The 23% Discount Below Fair Value Real?
Helios Towers (LSE:HTWS) grabbed investor attention after management lifted its 2026 outlook, pairing record tenancy additions with higher third-quarter revenue and fresh medium term targets for earnings and cash generation.
Recent price action shows that investors have been warming to the Helios Towers story, with the share price delivering a 33.86% year to date share price return and a 28.34% total shareholder return over the past 12 months as the market digests the upgraded 2026 targets and stronger third quarter trading.
Scan the tower-space momentum story beyond Helios Towers by lining up peers with similar earnings and balance sheet profiles using our hand-picked list of solid balance sheet and fundamentals (9 results).
Helios Towers now trades at a sizeable discount to both analyst targets and some intrinsic value estimates after a strong run. Is that caution about execution and cash generation, or a mispriced rerating waiting to happen?
Most Popular Narrative: 23% Undervalued
Helios Towers most followed valuation story puts fair value at £2.86 against a last close of £2.20, so the debate is really about whether the cash flow and tenancy growth assumptions used to reach that figure feel realistic to you.
The ongoing rollout and adoption of 4G/5G networks by African telecom operators and the proliferation of affordable smartphones are causing network congestion, compelling operators to invest in coverage expansion and densification. This should increase both tenancy ratios and rental yields, improving EBITDA margins and overall group profitability.
See why 9 investors see Helios Towers as 23% undervalued.
Result: Fair Value of £2.86 (UNDERVALUED)
Still, Helios Towers carries real execution risk if capital spending stays heavy while net margins lag forecasts. Customer concentration also leaves cash flows exposed to contract changes.
Find out about the key risks to this Helios Towers narrative.
Another View: Helios Towers Through The P/E Lens
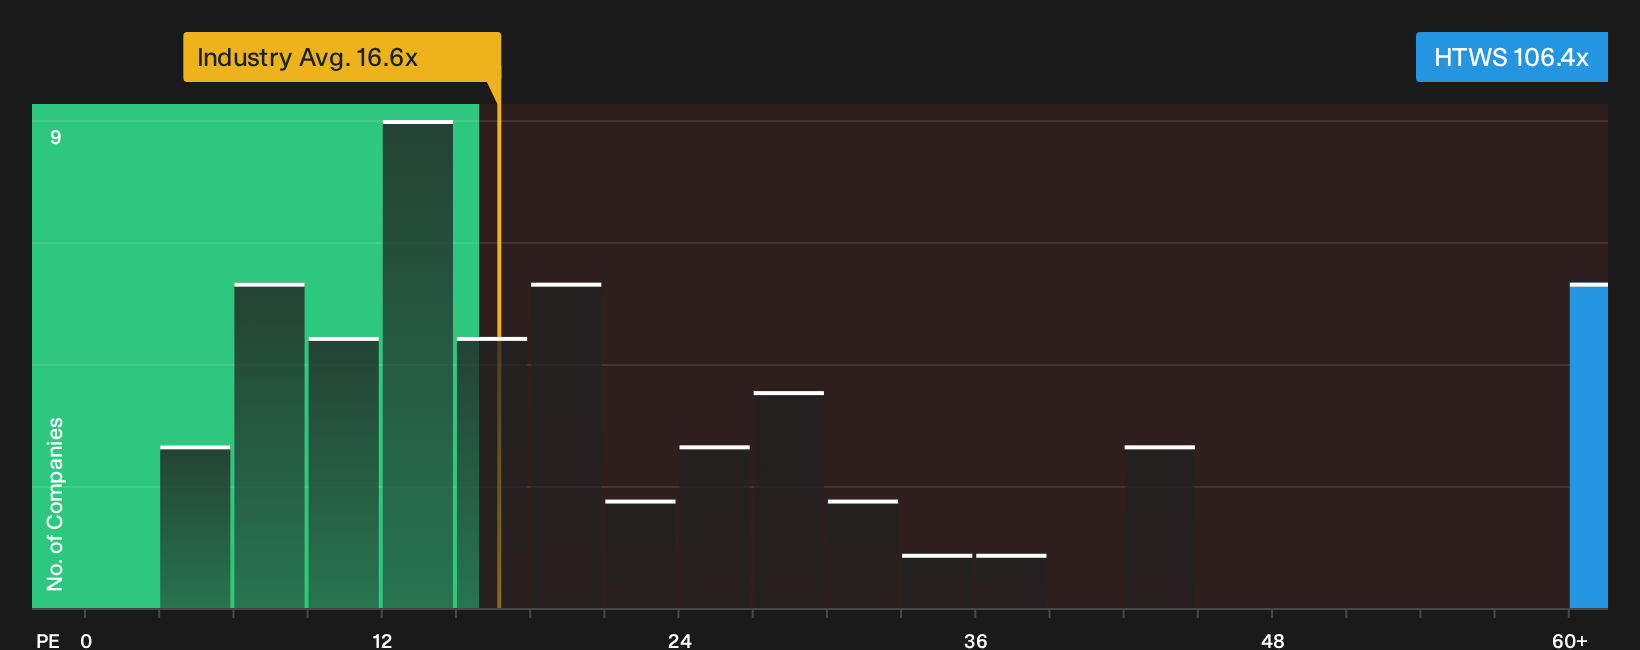
The story changes when you swap cash flow models for a simple earnings multiple. On a P/E of 106.4x, Helios Towers screens far richer than the European telecom group at 16.6x and peers at 15.8x, and it also sits above its own fair ratio estimate of 32.6x.
That kind of gap suggests the share price already bakes in a lot of improvement, so the risk for investors is that execution, earnings quality or sentiment have less room for disappointment than the DCF narrative implies. Which version of value do you trust more when the signals point in different directions?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Helios Towers so far. If the split between risks and potential rewards feels finely balanced, consider acting promptly and pressure test the numbers yourself by weighing up the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Helios Towers?
If Helios Towers has sharpened your focus on valuation, do not stop here. Put a broader watchlist together now so you are not reacting late.
- Target resilient balance sheets by sorting companies with robust finances using the list of solid balance sheet and fundamentals (9 results).
- Hunt for quality at a discount through our hand picked lineup of 5 high quality undiscovered gems.
- Zero in on cash generating blue chips that prioritize income stability with a curated set of 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com