
Is Hartford Insurance Group (HIG) Still Cheap on Earnings?
Hartford Insurance Group has delivered a strong multi year share price rise, and the question now is whether the current valuation is properly grounded in its earnings power. With the stock moving again in recent weeks, investors are asking how much of Hartford Insurance Group's profit story is already embedded in today's price.
- Over the past 5 years the stock has returned 106.9%, which makes it important to test whether that climb still lines up with the level and quality of earnings the business generates.
- Recent financial results showed higher net income and a larger dividend, along with leadership changes, which can shape how investors assess the durability of Hartford Insurance Group's profitability and its capacity to keep rewarding shareholders over time.
- There is a second opinion on Hartford Insurance Group worth weighing. See what analysts think Hartford Insurance Group's shares could be worth.
The issue now is whether Hartford Insurance Group's current share price is justified by its earnings when measured against a Fair Ratio benchmark.
If you want to test the same earnings based valuation question you are asking of Hartford Insurance Group across a wider field, scan through 42 high quality undervalued stocks.
Is Hartford Insurance Group Still Cheap on Earnings?
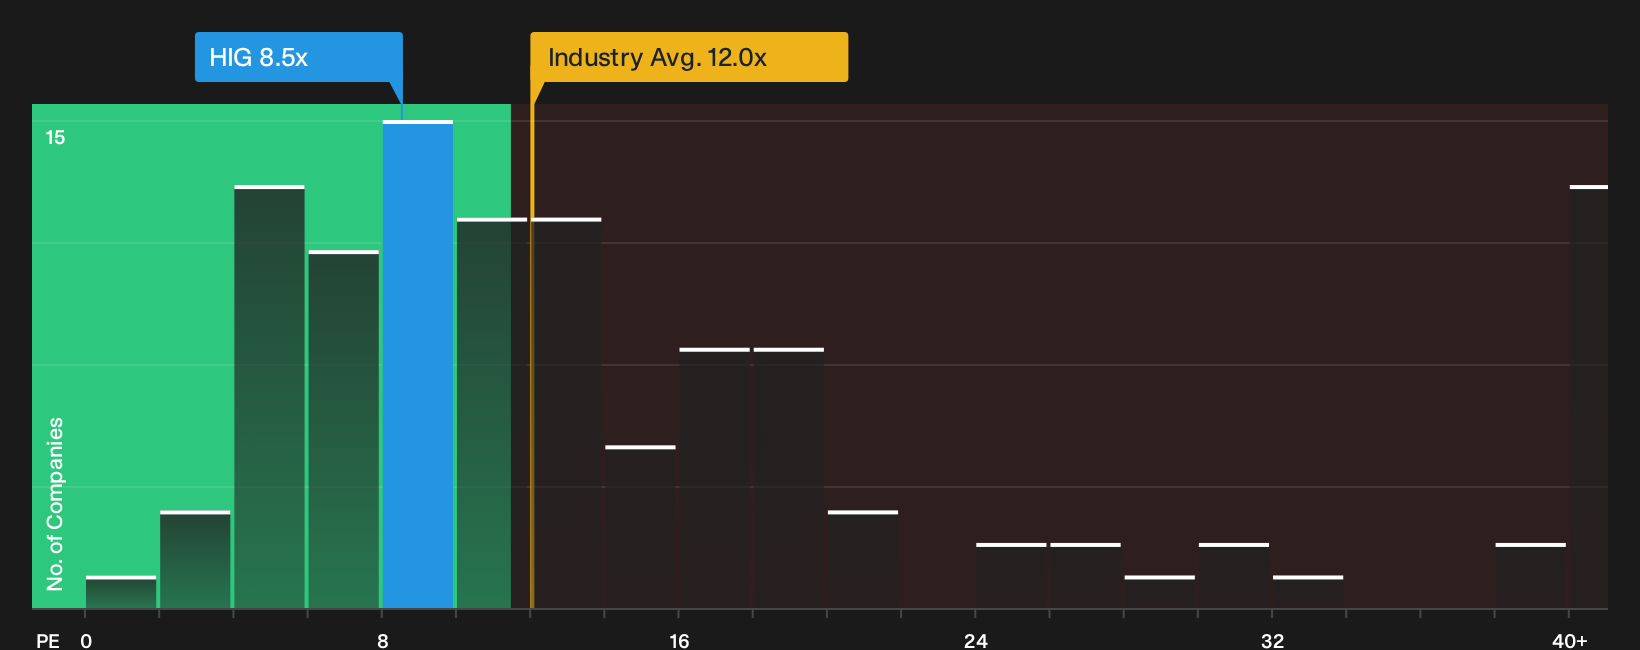
A P/E lens suits Hartford Insurance Group because earnings remain a central yardstick for insurers with long underwriting histories. Hartford Insurance Group trades on a P/E of 8.5x, below both the Insurance industry average of 12.0x and the broader peer group at 12.6x. Against a Fair Ratio benchmark that reflects its own profitability profile and risk mix, that level screens as undervalued rather than simply low compared with the pack.
The recent third quarter update, which showed higher net income and an increased dividend, has not pushed the P/E multiple up to those peer levels. The current price therefore still embeds a discount to what the Fair Ratio model implies. For anyone weighing Hartford Insurance Group against other insurers, the gap between its 8.5x and those benchmarks points to a stock that the market prices cautiously relative to its earnings power, which is what the detailed Fair Ratio output is designed to quantify. Explore the numbers behind Hartford Insurance Group's P/E valuation.
The Hartford Insurance Group Narrative: What Would Justify Today's Price?
Narratives for Hartford Insurance Group pick up where the valuation puzzle leaves off by spelling out the specific growth, margin and earnings paths that would need to hold for the stock to be worth materially more or less than today's price on Simply Wall St's Community page. Where a single valuation ratio gives one number, these scenarios unpack the future conditions that number rests on so you can watch in real time whether Hartford Insurance Group's actual progress keeps matching those assumptions or starts to drift away.
One of the top community narratives on Hartford Insurance Group: 6% undervalued
"The current valuation suggests that the market is not fully crediting Hartford Insurance Group for its reported 18.7% trailing 12 month core earnings ROE…"
Discover why this Narrative puts Hartford Insurance Group at 6% undervalued.
One more piece of the Hartford Insurance Group puzzle before you move on
Valuation only tells you what the market is paying today. To see how that stacks up against where professionals expect Hartford Insurance Group to be in a few years, you will want to line it up with. Explore where analysts expect Hartford Insurance Group to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com