
Innodata (INOD) Faces Fresh Scrutiny, Is The Stock Overvalued?
Innodata (INOD) has filed a shelf registration for up to 600,000 common shares, valued at about $35.946 million, in connection with an employee stock ownership plan offering.
That share issuance news lands after a sharp pullback in Innodata’s recent trading, with the 30 day share price return down 34.63% and the year to date share price return down 18.29%, even though the 3 year total shareholder return is very large. Recent mass layoffs tied to weaker client demand and an investigation into past disclosures have weighed on sentiment. This helps explain why momentum has faded despite that multi year gain and why investors are rethinking how much earnings risk they are willing to price into a US$43.30 share.
Compare Innodata's recent pullback with other AI focused small caps by scanning our curated list of 41 AI small caps that may be pricing earnings risk very differently.
Innodata now trades well below the analyst price target range, yet still reflects a large multiyear gain. So where does a reasonable estimate of fair value actually land after this pullback and the new share issuance plan?
Most Popular Narrative: 65% Undervalued
The most followed narrative pegs Innodata’s fair value at $122.75, which sits far above the last close at $43.30. As a result, the recent pullback looks very different through that lens.
The current valuation, including a P/E of about 50.7x that is more than double the Professional Services industry average, implies the market is already pricing in strong ongoing revenue growth and margin resilience. As a result, any setback on AI-related demand, major customer programs, or trust and safety offerings could have a sharp impact on the share price.
See why 90 investors see Innodata as 65% undervalued.
Result: Fair Value of $122.75 (UNDERVALUED)
Still, this bullish Innodata narrative leans heavily on concentrated Big Tech spending and a rich P/E near 50.7x that could unwind quickly if growth expectations slip.
Find out about the key risks to this Innodata narrative.
Another View: DCF Points The Other Way
The SWS DCF model paints a very different picture from the bullish $122.75 narrative. On this approach, Innodata’s shares at $43.30 sit above an estimated future cash flow value of $23.44, which screens as overvalued rather than cheap. That gap raises a simple question: Which lens do you trust more for a long term position?
For readers who want to see how those cash flow assumptions are put together in detail, Look into how the SWS DCF model arrives at its fair value.
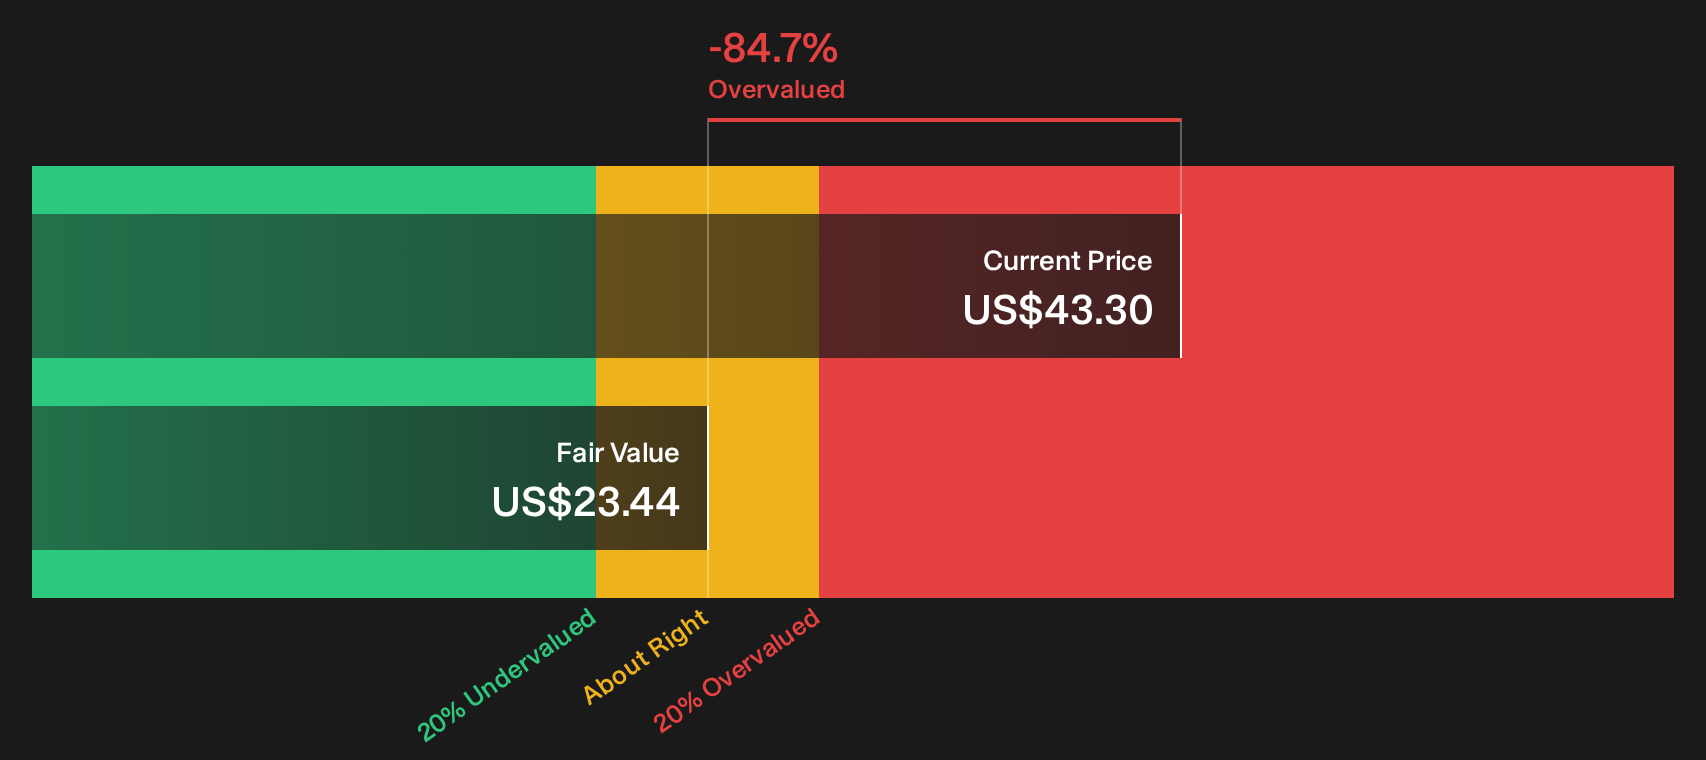
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Innodata for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around Innodata is clearly split. Consider acting promptly, reviewing the numbers yourself, and weighing the 3 key rewards and 1 important warning sign against your own expectations.
Looking for more ideas beyond Innodata?
If Innodata has sharpened your focus on valuation and risk, do not stop here. Use screeners to spot other opportunities before the crowd catches on.
- Target quality at a discount by scanning a curated 35 high quality undervalued stocks that already blends strong cash flows with sturdier balance sheets.
- Strengthen your downside protection by reviewing a 31 resilient stocks with low risk scores that filters for businesses with more resilient risk profiles.
- Get ahead of the crowd by checking a 19 high quality undiscovered gems that highlights lesser known companies with solid fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com