
Cushman And Wakefield (CWK) Stock Could Be Overvalued Following A 93% Run
Cushman & Wakefield shares closed at US$14.93. After a strong multi year run, the key issue for investors is whether that price still aligns with what the company is earning. With the spotlight back on commercial property activity and data center demand, the question now is how much of that story is already embedded in the stock's valuation.
- Over the past 3 years the share price has gained 93.1%, which puts real pressure on the current earnings stream to justify the move.
- Recent deals in offices, apartments and data center related real estate can support expectations for fee income and profitability that feed directly into any earnings based valuation.
- The analysts covering Cushman & Wakefield have run their own numbers. See what analysts think Cushman & Wakefield's shares could be worth.
The stock's next move may depend on whether Cushman & Wakefield's current earnings make today's valuation look reasonable when set against the Fair Ratio benchmark.
To put Cushman & Wakefield in context and see how other real estate related plays stack up on quality and valuation, compare it with the 35 high quality undervalued stocks.
Is Cushman & Wakefield Getting Expensive on Earnings?
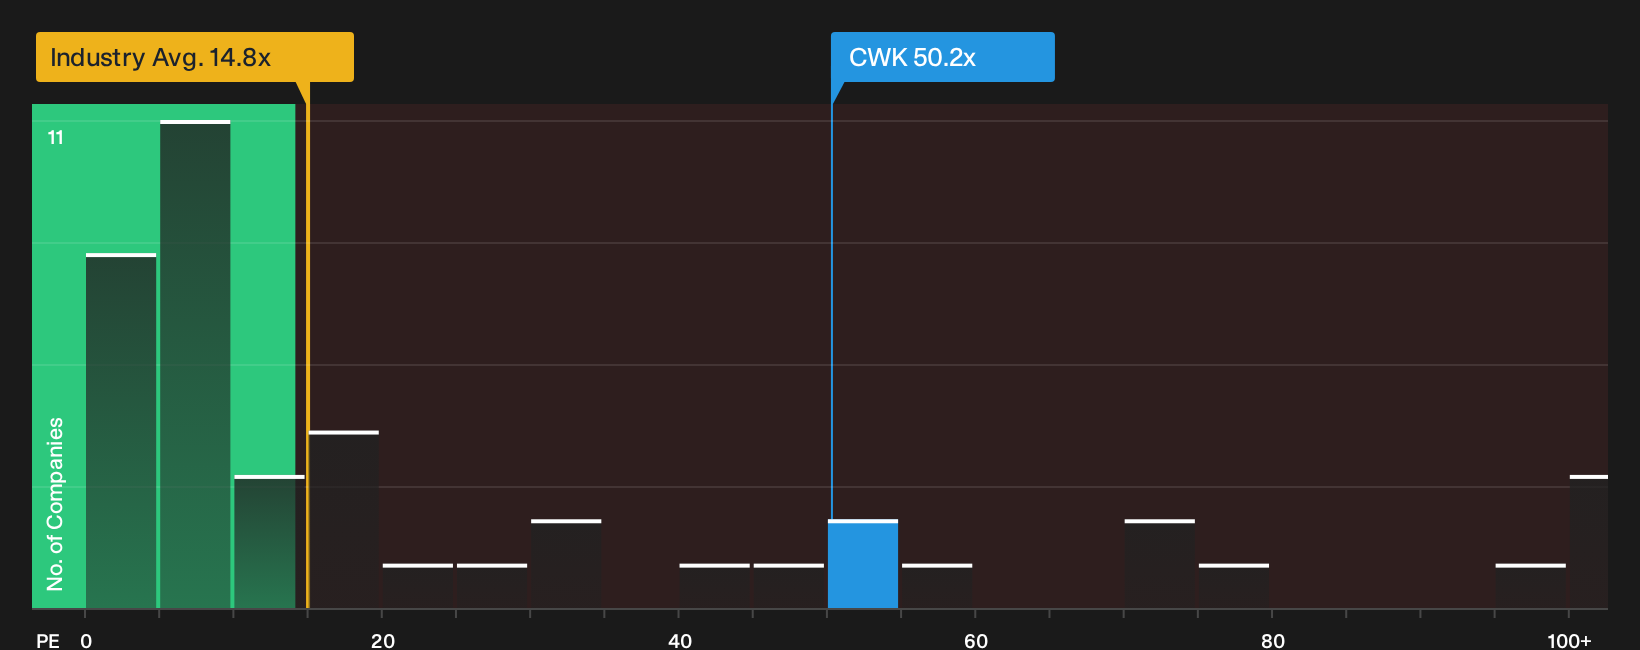
The P/E ratio works well for Cushman & Wakefield because investors are focused on how consistently its advisory and brokerage earnings can support the current share price. On this measure, the stock trades on a P/E of 50.2x, compared with a Real Estate sector average of 14.8x and a peer group closer to 86.6x. This means the shares price in a richer earnings tag than the broad industry but below more highly rated rivals.
The Fair Ratio model, which looks at earnings quality, growth, size and risk, points to a lower P/E than where Cushman & Wakefield is currently trading, so the shares screen as overvalued on this framework. Because the business has reported strong Q3 2026 earnings and cleared its nearest debt maturities, optimism around the story already appears well reflected in the multiple. Explore the numbers behind Cushman & Wakefield's P/E valuation.
The Cushman & Wakefield Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Cushman & Wakefield's valuation debate leaves off and explain what kind of growth, margins and earnings path would need to hold for the current P/E to look high, low or about right, all within the Community page. Each scenario links a fair value estimate to a particular set of potential drivers and setbacks, so you can track over time which version of Cushman & Wakefield's story the numbers are aligning with.
Bulls and bears on Cushman & Wakefield are reading the same earnings story, yet they reach very different conclusions about how much credit to give the services and data center mix shift.
Bull case: 12% undervalued
"High client retention and recurring services are now complemented by rapid growth in higher value offerings such as data center work..."
Discover why this Narrative puts Cushman & Wakefield at 12% undervalued.
Bear case: 15% overvalued
"The current numbers on deleveraging, free cash flow conversion, and earnings guidance imply a share price that treats Cushman & Wakefield as a cyclical services company..."
Explore why this Narrative puts Cushman & Wakefield at 15% overvalued.
One more Cushman & Wakefield check that sits beyond today's P/E debate
There is a separate lens that compares Cushman & Wakefield's current share price with where professional covering analysts expect the business to be several years from now. That gap or overlap can be revealing. Explore where analysts expect Cushman & Wakefield to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com