
Workiva (NYSE:WK) surprises with Q3 2026 sales but quarterly revenue guidance slightly misses expectations
Cloud reporting platform Workiva (NYSE:WK) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 17.3% year on year to $263 million. On the other hand, next quarter’s revenue guidance of $276.5 million was less impressive, coming in 0.6% below analysts’ consensus estimates. Its non-GAAP profit of $0.72 per share was 9.8% below analysts’ consensus estimates.
For more on Workiva, read our free full research report.
Workiva (WK) Q3 2026 highlights:
- Revenue $263 million vs S&P analysts’ consensus estimates of $261.4 million (17.3% year-on-year growth, 0.6% beat)
- Adjusted EPS $0.72 vs S&P analysts’ consensus estimates of $0.80 (9.8% miss)
- Adjusted operating income $48.25 million vs analysts’ consensus estimates of $44.93 million (18.3% margin, 7.4% beat)
- Revenue guidance $276.5 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $278.1 million
- Adjusted EPS guidance Management lowered its full-year adjusted EPS guidance to $2.82 at the midpoint, a 16.8% decrease
- Operating margin 6.8%, up from -1.5% in the same quarter last year
- Free cash flow margin 26.1%, down from 30.5% in the previous quarter
- Customers 6,840, up from 6,750 in the previous quarter
- Net revenue retention rate 110%, down from 111% in the previous quarter
- Billings $287 million at quarter end, up 10.8% year on year
- Market capitalization $4.64 billion
“Our third quarter results reflect continued momentum across the Workiva platform as organizations navigate growing complexity,” said Julie Iskow, President & Chief Executive Officer. “AI is fundamentally changing enterprise software, from helping people do the work to increasingly doing the work itself. This shift plays directly to Workiva’s strengths. As software takes on more complex, regulated, and high-stakes work, the need for accuracy, transparency, and trust becomes even more critical. Workiva is uniquely positioned to meet these needs and expand the role our platform plays across the enterprise.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Workiva’s revenue grew at a decent 19.3% compounded annual growth rate over the last five years. Its growth was slightly above the average software company and shows its offerings resonate with customers.
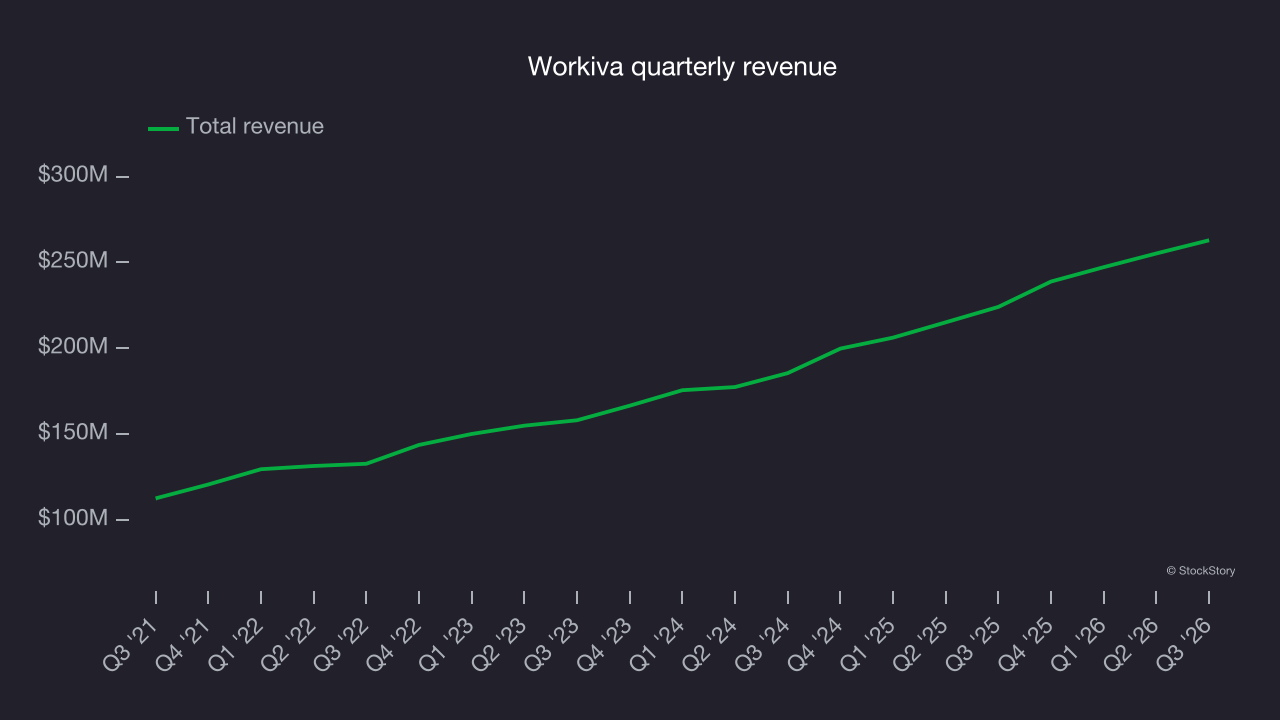
Long-term growth is the most important, but within software, a half-decade historical view may miss new innovations or demand cycles. Workiva’s annualized revenue growth of 19.3% over the last two years aligns with its five-year trend, suggesting its demand was stable. 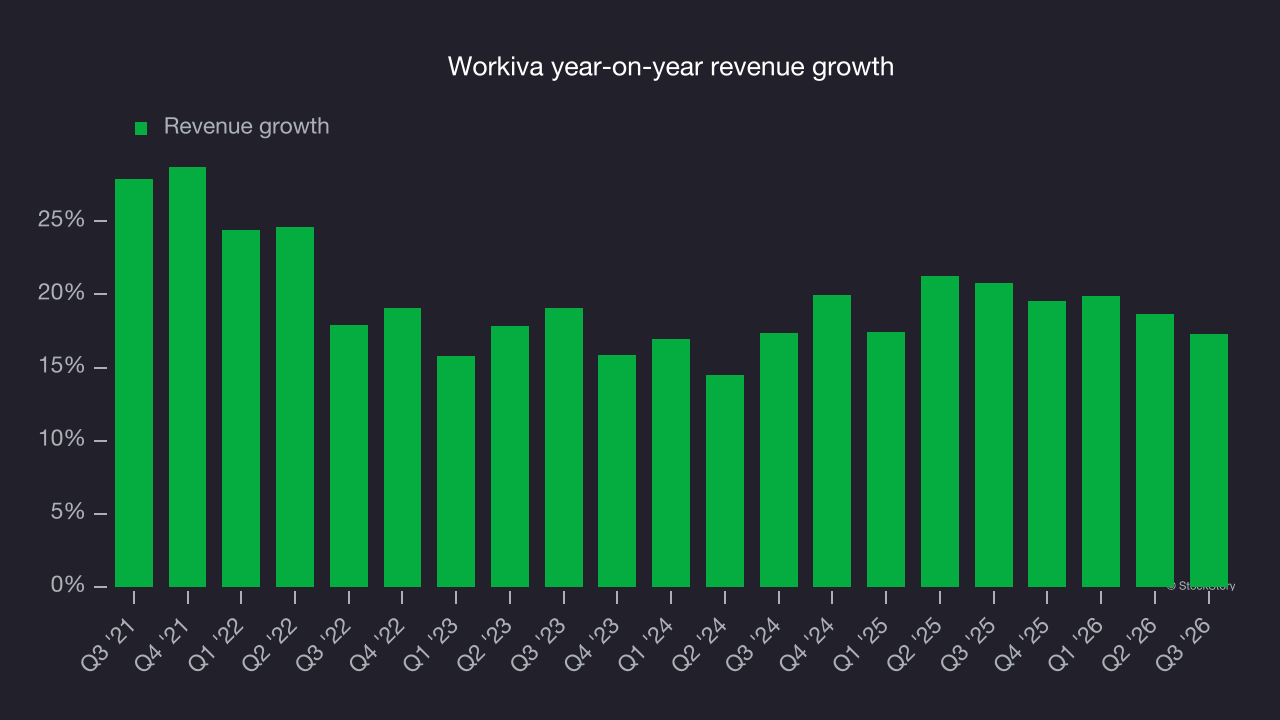
This quarter, Workiva reported year-on-year revenue growth of 17.3%, and its $263 million of revenue exceeded Wall Street’s consensus estimates by 0.6%. Company management is currently guiding for a 15.7% year-on-year increase in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 15.5% over the next 12 months, according to S&P, a deceleration versus the last two years. Despite the slowdown, this projection is above the sector average and implies the market sees some success for its newer products and services.
Billings
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
Workiva’s billings came in at $287 million in Q3, and over the last four quarters, its growth slightly lagged the sector as it averaged 14.2% year-on-year increases. This alternative top-line metric grew more slowly than total revenue, meaning the company recognizes revenue faster than it collects cash – a headwind for its liquidity that could also signal a slowdown in future revenue growth. 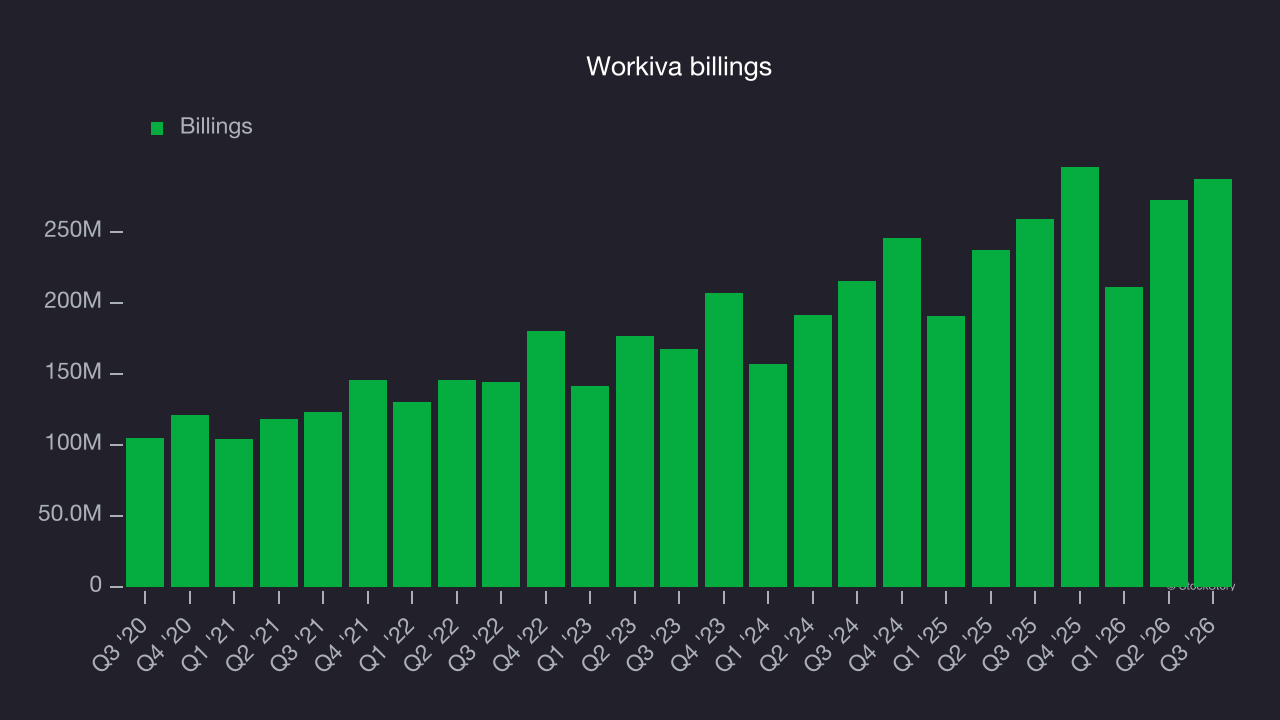
Customer retention
An advantage of the software-as-a-service business model, and a reason these companies trade at high valuation multiples, is that customers typically spend more on a company’s products and services over time.
Workiva’s net revenue retention rate, a key performance metric measuring how much money existing customers from a year ago are spending today, was 110% in Q3. This means Workiva would’ve grown its revenue by 10% even if it didn’t win any new customers over the last 12 months.
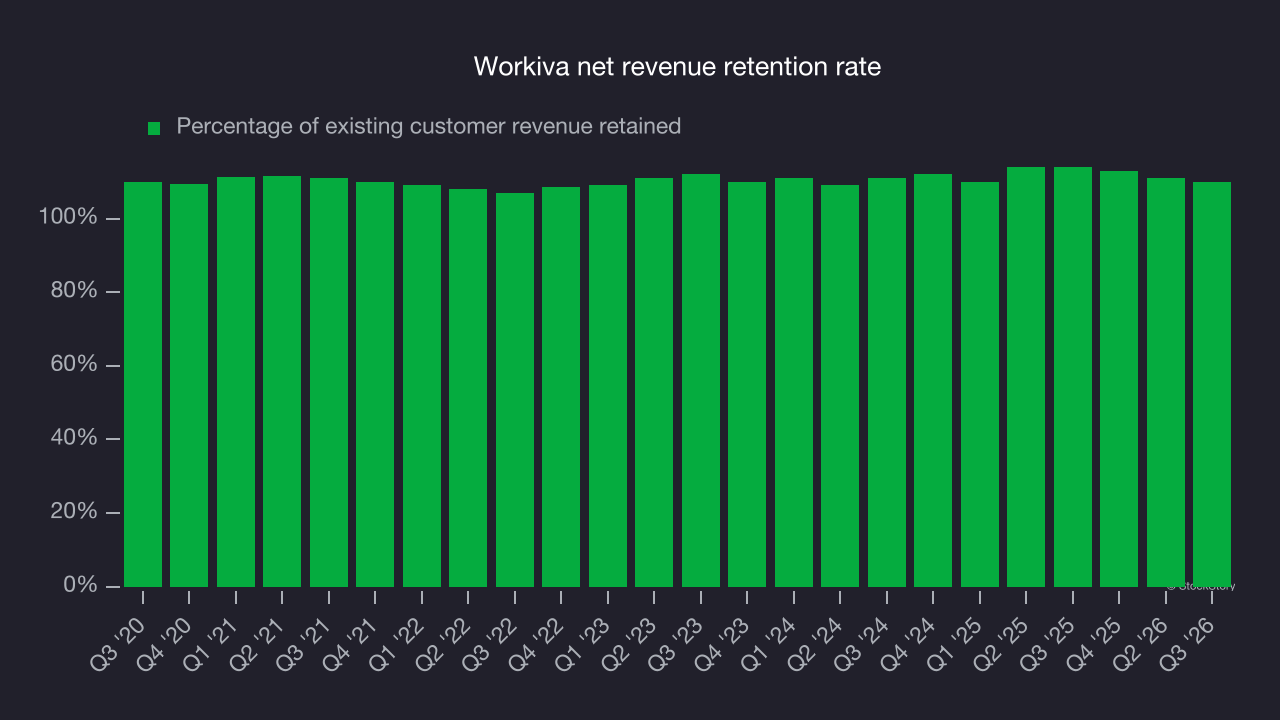
Despite its recent drop, Workiva still has a good net retention rate, indicating that customers are satisfied with its software and getting more value from it over time.
Key takeaways from Workiva’s Q3 results
Workiva’s EPS outlook fell short of expectations for both the full year and next quarter, making this a weaker quarter despite adjusted operating income beating analysts’ consensus estimates. Shares remained flat at $85.50 immediately after the results.
Workiva’s latest quarter was underwhelming. One earnings report doesn’t define a company’s quality, though, so let’s examine whether the stock is a buy at the current price. The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation when deciding if the stock is a buy. For more on Workiva, read the free full research report here.