
Should Rising AI Power Demand Require Action From AGL Energy (ASX:AGL) Investors?
- AGL Energy is being reappraised after analysis highlighted how its large generation fleet and retail base could capture electricity demand from AI intensive data centres, supported by its grid scale batteries and renewable firming projects.
- The interesting angle is that AGL Energy’s extensive pipeline of batteries and firming capacity links directly to data centre load growth, tying long dated transition projects to a very immediate source of potential power demand.
- We now examine how AGL Energy’s investment narrative may shift as its grid scale batteries intersect with rising AI data centre demand.
Scan beyond AGL Energy and compare it with hand-picked power players positioned for AI data centre demand through our 41 power grid technology and infrastructure stocks
AGL Energy Investment Narrative Recap
To own AGL Energy, you need to believe the heavy spend on grid scale batteries, firming assets and retail technology eventually feeds through to steadier earnings, even as analysts currently see a decline in profit over the next three years. The AI data centre theme gives that investment a clearer potential demand story, but it does not remove the execution work ahead.
The key near term swing factor is whether major projects and the extended retail transformation land close to the revised cost and timing guidance. The biggest risk remains cash being tied up in capex and dividends, which can keep free cash flow tight and limit room to reduce debt or commit to new projects on attractive terms.
Against this backdrop, the extended retail transformation program looks highly relevant. AGL Energy now expects the program to cost an extra A$100 million to A$150 million and to run up to 12 months longer, while still targeting A$70 million to A$90 million of annual cash savings from FY30 through its AI native Kaluza and Salesforce platform.
For an investor focused on the AI data centre angle, that retail work matters because cost to serve and billing efficiency shape how much benefit AGL Energy can keep from any extra volume. Any further delays, overspends or slippage in those promised savings would add pressure to earnings at the same time that heavy investment in batteries and firming capacity continues.
AGL Energy Earnings And Valuation Assumptions
AGL Energy's AI data centre pitch sits on top of an earnings path that analysts currently see trending lower rather than higher. Consensus forecasts point to revenue shrinking by 1.2% a year and profit margins moving from 5.4% today to 3.3% by 2029. This means the grid scale battery build out and retail overhaul are being tested against a thinner profitability profile, not a richer one.
On the earnings line, analysts are modelling A$756.0 million today dropping to A$442.8 million by 2029. That is a decline of A$313.2 million in profit, even before considering the spread between the most optimistic forecast at A$548.0 million and the most cautious at A$262.8 million. The gap between those end points highlights how much uncertainty investors are weighing over execution, policy settings and how much value AGL Energy can capture from AI power demand once the capital spend is committed.
Valuation assumptions are even more demanding. To bridge the current set up with the analyst targets, the stock would need to move from trading on a P/E of 8.1x today to 18.6x on those 2029 earnings. This is above the 10.2x multiple cited for the wider Australian integrated utilities peer group. In plain terms, the market would be asked to pay more than double the current earnings multiple for lower forecast profit, on the basis that decarbonisation projects, grid batteries and retail platform savings eventually support steadier cash generation.
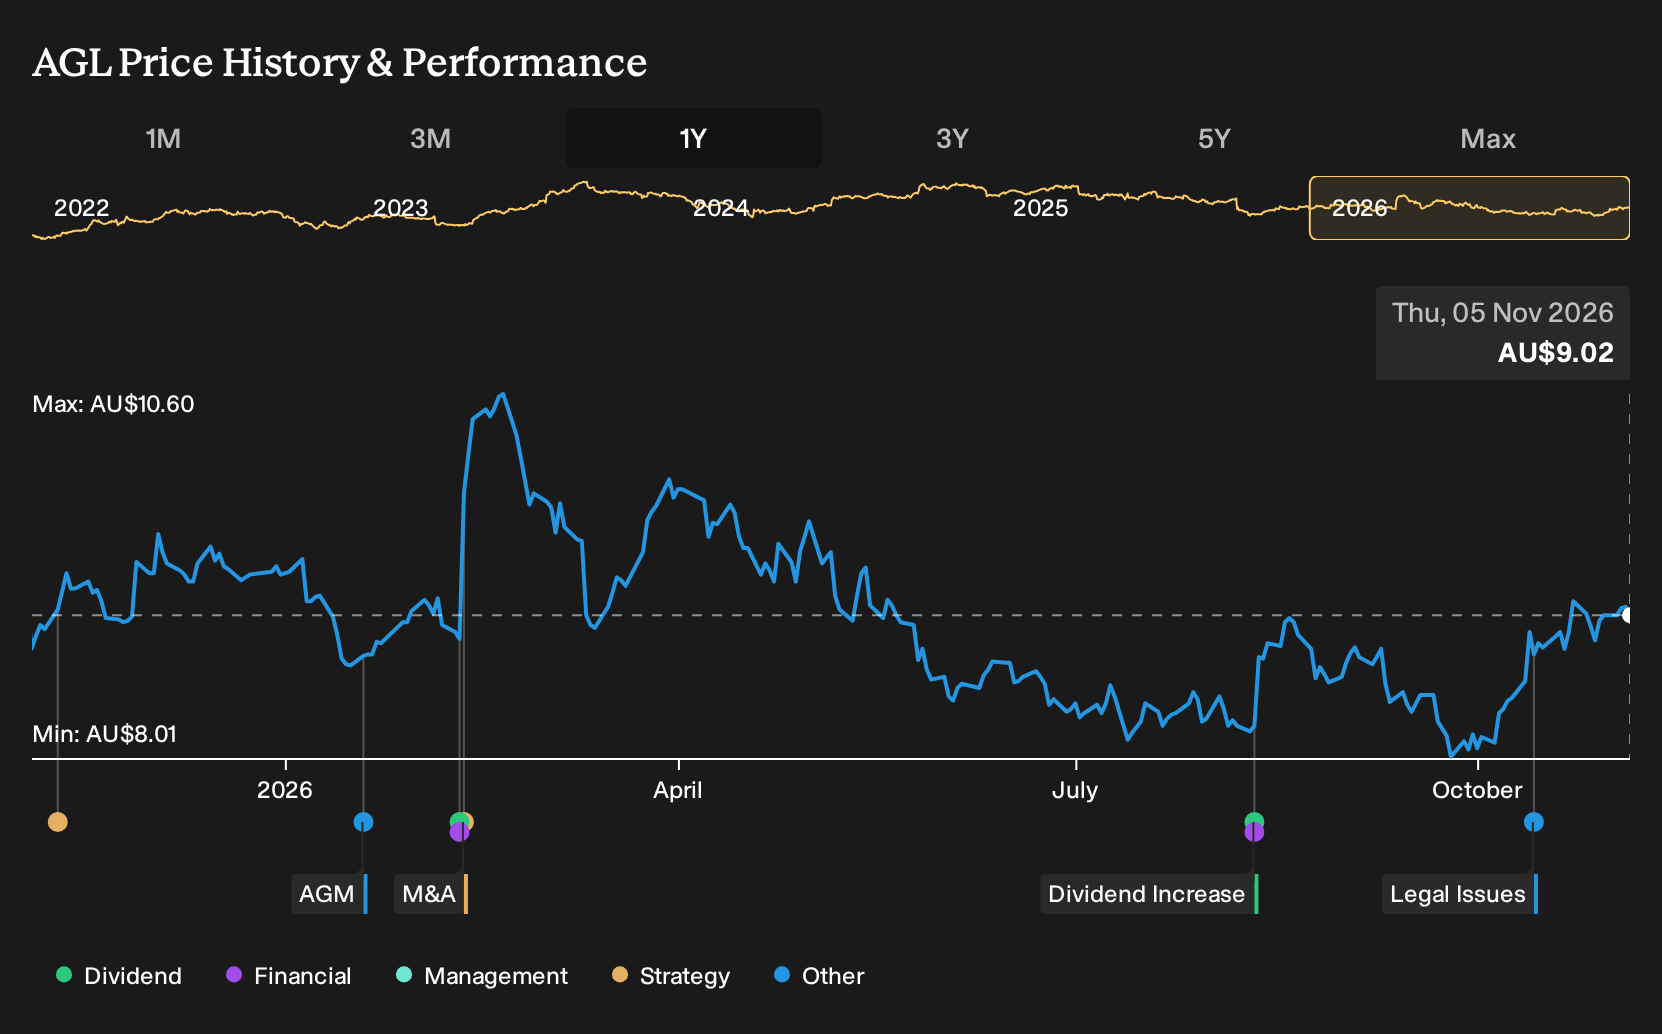
Price targets built on that framework cluster around A$9.92 per share, with a range from A$8.10 to A$11.25 against a recent price of A$9.12. An 8.1% gap between the market price and the average target signals that, on these inputs, analysts as a group view AGL Energy as roughly in line with their fair value estimates. For you as an investor, the question becomes whether the AI data centre opportunity, the battery pipeline and the retail cost savings justify the combination of lower earnings forecasts and a higher assumed P/E multiple.
AGL Energy's narrative projects A$13.4b revenue and A$442.8 million earnings by 2029. This involves revenue declining at 1.2% per year and earnings falling by A$313.2 million from A$756.0 million today.
Uncover why AGL Energy's fair value indicates a 10% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community has only three fair value estimates for AGL Energy, yet they stretch from A$9.79 to A$16.34 per share. That kind of spread shows how sharply opinions differ. Weigh those crowd views against the heavy capex load and AI linked battery projects, then explore multiple perspectives before deciding your next move.
Explore 2 other AGL Energy fair value estimates, including one that suggests there could be as much as 81% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your AGL Energy research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for AGL Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AGL Energy's overall financial health at a glance.
Looking For More Investment Ideas Beyond AGL Energy?
If the AGL Energy story has sharpened your thinking on risk, valuation and long term themes like AI driven power demand, use that same lens across a wider watchlist. The Simply Wall St Screener lets you filter for different strengths so you can focus on companies that better fit your own risk, income or quality preferences.
- If capital protection is front of mind, start with businesses that screen for resilience and lower risk profiles through our 6 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, sort through companies that combine solid fundamentals with appealing valuations using the 5 high quality undervalued stocks.
- If you want sturdier balance sheets to anchor your portfolio, filter for firms with stronger financial footing via the list of solid balance sheet and fundamentals (12 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com