
We're Hopeful That LARK Distilling (ASX:LRK) Will Use Its Cash Wisely
We can readily understand why investors are attracted to unprofitable companies. For example, although Amazon.com made losses for many years after listing, if you had bought and held the shares since 1999, you would have made a fortune. But while history lauds those rare successes, those that fail are often forgotten; who remembers Pets.com?
Given this risk, we thought we'd take a look at whether LARK Distilling (ASX:LRK) shareholders should be worried about its cash burn. In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. Let's start with an examination of the business' cash, relative to its cash burn.
When Might LARK Distilling Run Out Of Money?
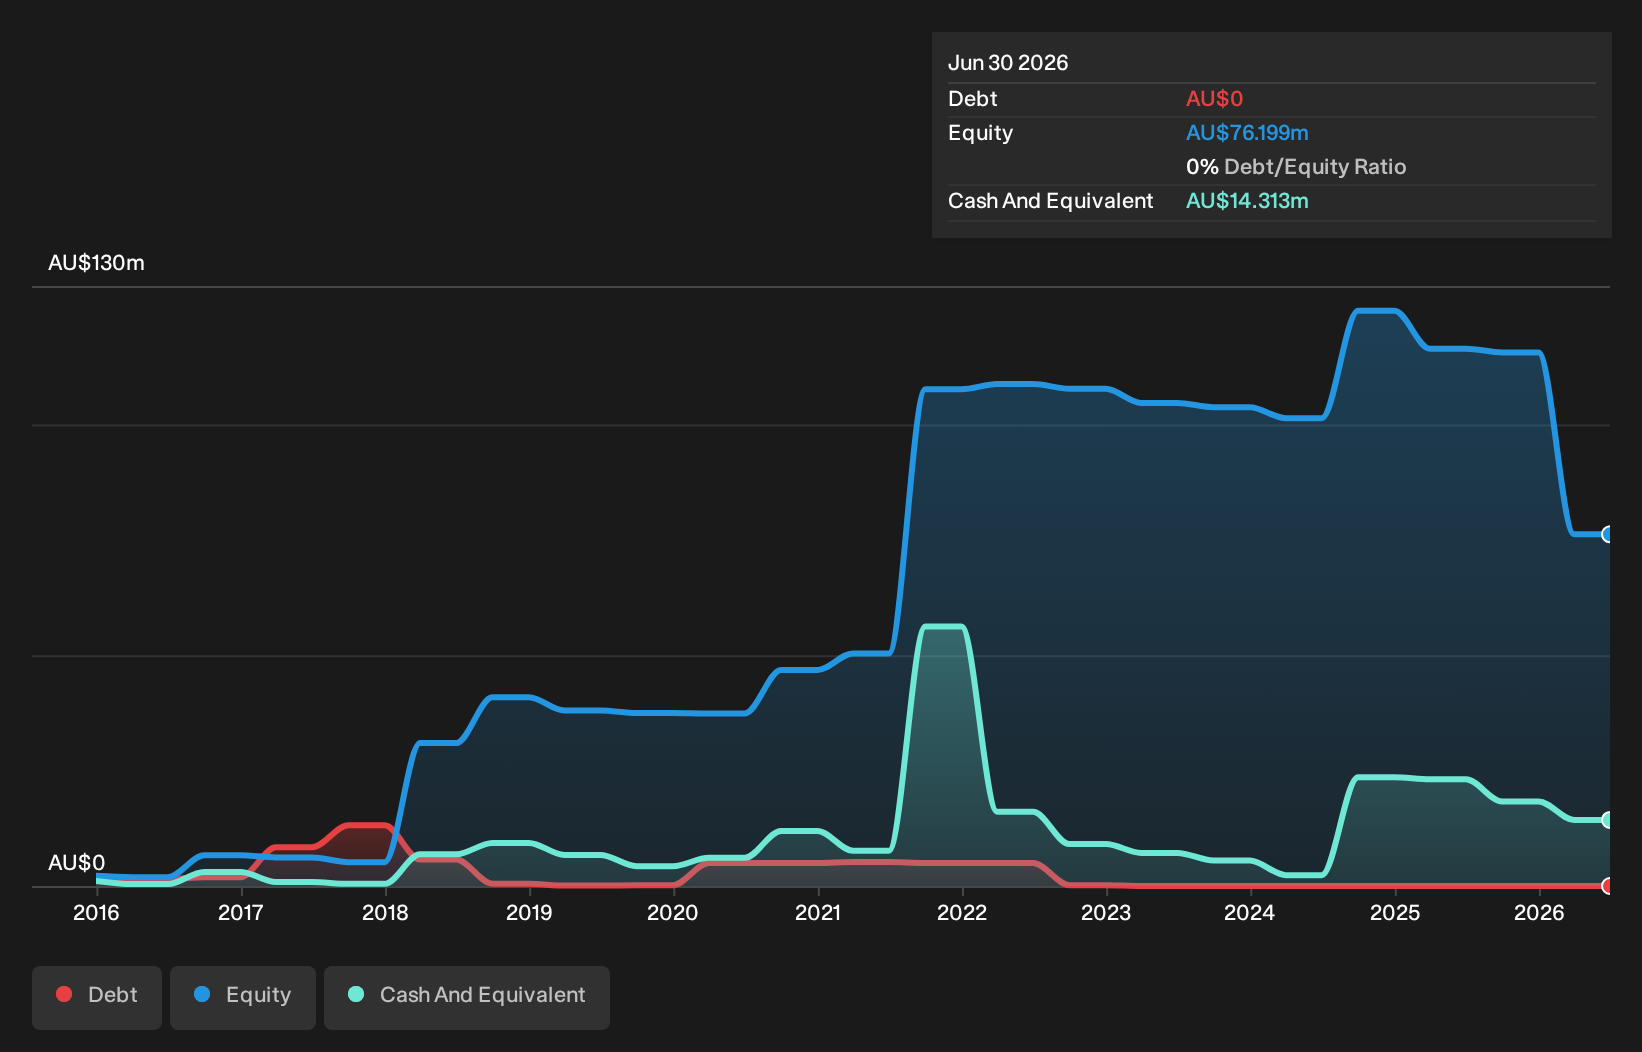
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. In June 2026, LARK Distilling had AU$14m in cash, and was debt-free. Looking at the last year, the company burnt through AU$7.6m. Therefore, from June 2026 it had roughly 23 months of cash runway. That's not too bad, but it's fair to say the end of the cash runway is in sight, unless cash burn reduces drastically. Importantly, if we extrapolate recent cash burn trends, the cash runway would be a lot longer. The image below shows how its cash balance has been changing over the last few years.
View our latest analysis for LARK Distilling
How Well Is LARK Distilling Growing?
At first glance it's a bit worrying to see that LARK Distilling actually boosted its cash burn by 12%, year on year. The revenue growth of 15% gives a ray of hope, at the very least. On balance, we'd say the company is improving over time. While the past is always worth studying, it is the future that matters most of all. So you might want to take a peek at how much the company is expected to grow in the next few years.
How Easily Can LARK Distilling Raise Cash?
While LARK Distilling seems to be in a fairly good position, it's still worth considering how easily it could raise more cash, even just to fuel faster growth. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. One of the main advantages held by publicly listed companies is that they can sell shares to investors to raise cash and fund growth. By comparing a company's annual cash burn to its total market capitalisation, we can estimate roughly how many shares it would have to issue in order to run the company for another year (at the same burn rate).
LARK Distilling has a market capitalisation of AU$62m and burnt through AU$7.6m last year, which is 12% of the company's market value. Given that situation, it's fair to say the company wouldn't have much trouble raising more cash for growth, but shareholders would be somewhat diluted.
Is LARK Distilling's Cash Burn A Worry?
Even though its increasing cash burn makes us a little nervous, we are compelled to mention that we thought LARK Distilling's cash runway was relatively promising. While we're the kind of investors who are always a bit concerned about the risks involved with cash burning companies, the metrics we have discussed in this article leave us relatively comfortable about LARK Distilling's situation. Readers need to have a sound understanding of business risks before investing in a stock, and we've spotted 2 warning signs for LARK Distilling that potential shareholders should take into account before putting money into a stock.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.