
Cencora (COR) Stock May Be A Bargain Following A $2.4B Acquisition
Cencora has put up a long run in its share price, and the stock is now back in focus as investors ask whether the current level can still be explained by its earnings power. With the company active in complex pharmaceutical distribution and services, that question matters for anyone trying to separate price momentum from underlying profit support.
- Over the past 5 years, Cencora has delivered a total return of 196.0%, which places a lot of weight on the idea that its earnings can justify a much higher share price than in the past.
- The recently announced plan to acquire American Oncology Network in a transaction valued at up to US$2.4b may support expectations for future earnings by expanding Cencora's community oncology footprint and changing how capital is allocated across the business.
- Your read on Cencora is one view; the desks covering it have another. See what analysts think Cencora's shares could be worth.
The stock's next move may depend on whether Cencora's current earnings are strong enough to support a share price around US$354.
If you are comparing Cencora's earnings story with its recent stock performance, it can be helpful to evaluate it alongside 35 high quality undervalued stocks.
Does Cencora Look Undervalued on Earnings?
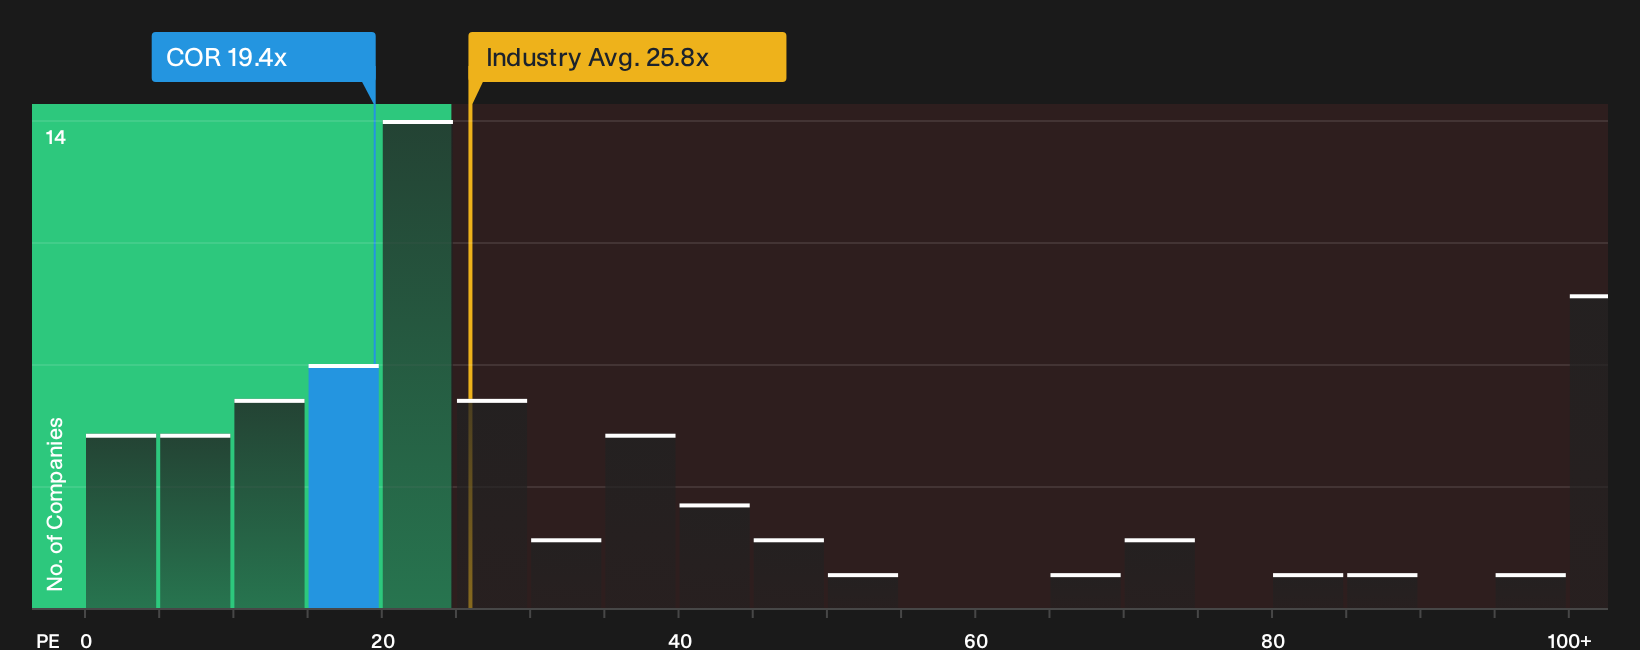
The P/E ratio suits Cencora because earnings are a central reference point for a large, established distributor. On this measure, the stock trades on roughly 19.4x, which is below both the broader healthcare sector on 25.8x and the peer group average of 31.3x. For a business this size, a discount of that scale signals that the market is not attaching the same multiple to each dollar of profit as it does for many comparable operators.
The fair multiple implied by the valuation model is higher than Cencora’s current 19.4x P/E, so the shares screen as undervalued on this framework. Because the agreed US$2.4b deal for American Oncology Network could reshape the earnings mix, the present discount suggests investors are not paying up in advance for that integration risk or potential upside. The gap between the present P/E and what the model suggests as a fairer level leaves room for readers to test whether they think Cencora’s profit quality, balance sheet and acquisition track record justify any narrowing of that spread. Explore the numbers behind Cencora's P/E valuation.
The Cencora Narrative: What Would Justify Today's Price?
Narratives for Cencora on Simply Wall St pick up where the valuation puzzle leaves off. They spell out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today's price. Each scenario links a fair value to a particular set of catalysts and risks for Cencora's business, so you can track over time which version of the story is actually unfolding.
Community views on Cencora are split between those who see more upside in its specialty and buyback story and those who focus on execution and mix risks.
Bull case: roughly fairly valued
"The deepening focus on specialty pharmaceuticals through platforms such as OneOncology and Retina Consultants of America, which are currently performing ahead of initial expectations..."
Discover why this Narrative puts Cencora at roughly fairly valued.
Bear case: 7% overvalued
"While Cencora is embedding AI tools and broader digital capabilities across its highly automated distribution network, the ongoing cost and complexity of these investments could limit the benefit to operating margin..."
Explore why this Narrative puts Cencora at 7% overvalued.
One more Cencora signal to check before you decide
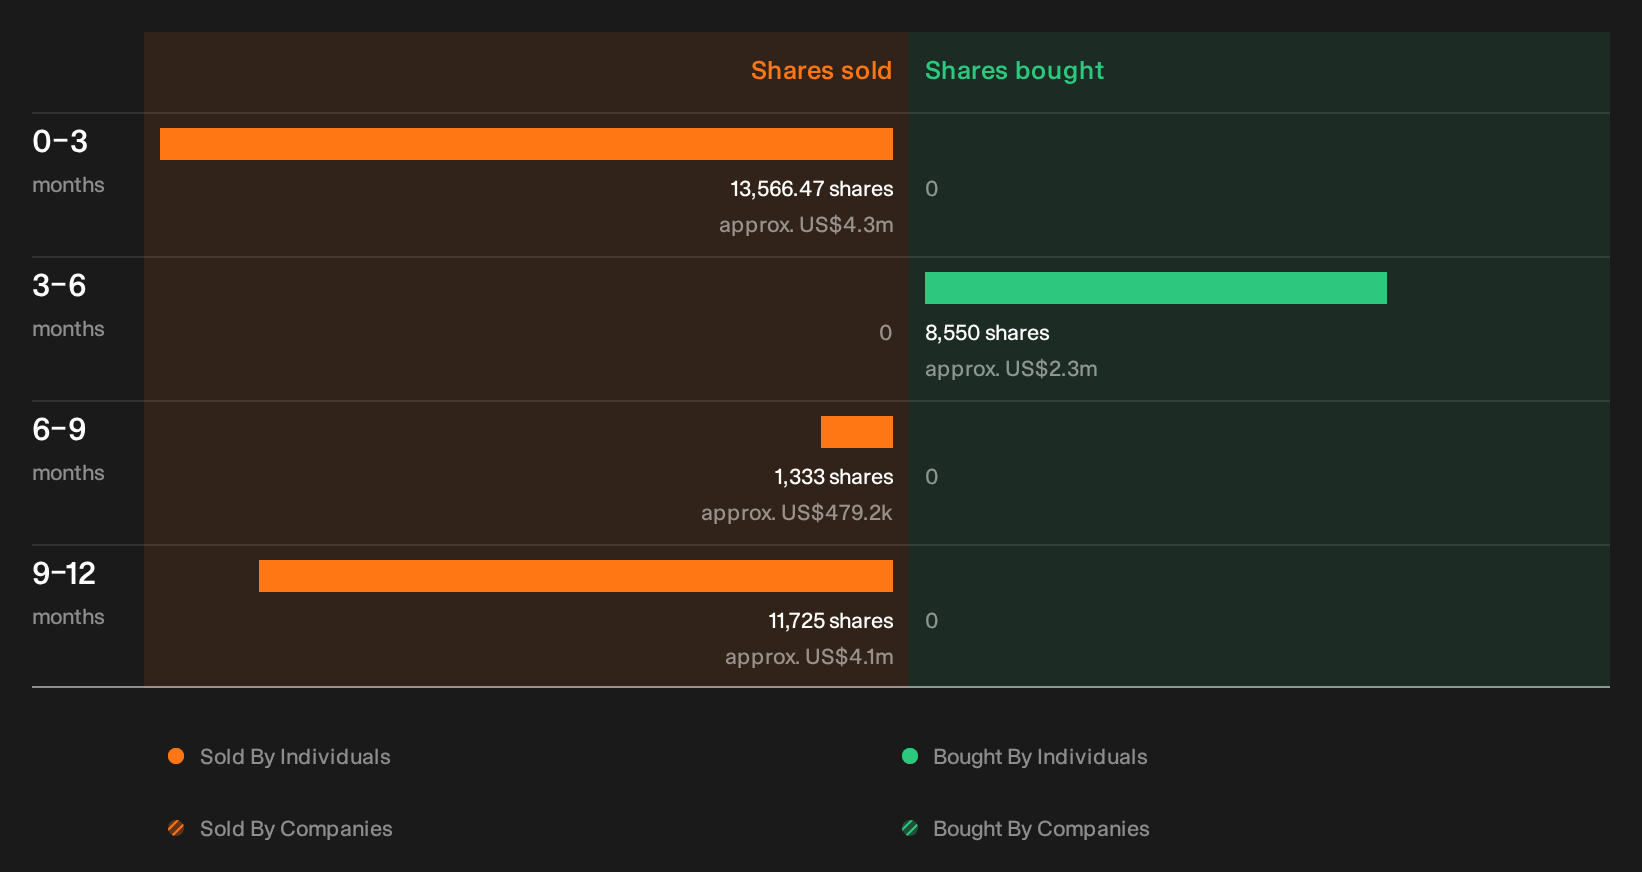
Cencora’s valuation story is only part of the picture, because recent insider share disposals have been flagged by our checks and the specific sellers, trade sizes and possible readings are still for you to review. See the recent insider selling flagged for Cencora.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com