
Raised Outlook And Strong Quarter Could Change The Case For BioCryst Stock
- BioCryst Pharmaceuticals raised its full-year 2026 revenue guidance to US$715 million to US$730 million and reported third quarter 2026 revenue of US$180.29 million and net income of US$37.92 million, alongside a long lived asset impairment of US$9.54 million.
- The nine month figures show a sharp contrast between higher revenue of US$554.96 million and a reported net loss of US$605.5 million, which puts the updated outlook and ORLADEYO driven operating momentum in the context of heavy costs and impairment charges.
- This article considers how BioCryst Pharmaceuticals' raised 2026 revenue guidance may reshape the investment narrative built around ORLADEYO concentration risk.
Scan beyond BioCryst Pharmaceuticals and see how other healthcare specialists are priced for their next move with our curated 38 healthcare AI stocks.
BioCryst Pharmaceuticals Investment Narrative Recap
To own BioCryst Pharmaceuticals, you need to be comfortable with a business that is still built around ORLADEYO and a rare disease focus while carrying heavy recent losses. The raised 2026 revenue guidance to US$715 million to US$730 million signals management confidence in ORLADEYO demand, but the nine month net loss of US$605.5 million keeps cash burn and funding flexibility in sharp focus.
The key short term swing factor is whether ORLADEYO driven operating momentum can offset rising competition and the drag from high R&D and any future impairments. The latest quarter shows positive net income, yet the large year to date loss underlines that execution on cost control and pipeline progress remains the biggest operational risk.
The most relevant update here is the guidance revision, because it directly ties to how you think about ORLADEYO concentration risk and near term execution. Management now expects 2026 revenue of US$715 million to US$730 million, compared with the prior US$690 million to US$715 million range, which tightens the focus on delivery against those numbers.
In the short term, that higher bar interacts with the recent long lived asset impairment of US$9.54 million and the year to date loss profile. If BioCryst Pharmaceuticals continues to lean on ORLADEYO while investing in pipeline assets such as navenibart, the key question is whether operational progress and any future HAE data can outpace competitive pressure and ongoing expense intensity.
Analysts expect BioCryst Pharmaceuticals to reach US$930.1 million in revenue and US$131.3 million in earnings by 2029. That outlook reflects forecast annual revenue growth of 1.6% and an earnings swing of about US$589.3 million from a current loss of US$458.0 million to the projected profit level.
Uncover why BioCryst Pharmaceuticals' fair value indicates a 158% potential upside to its current price that could narrow quickly.
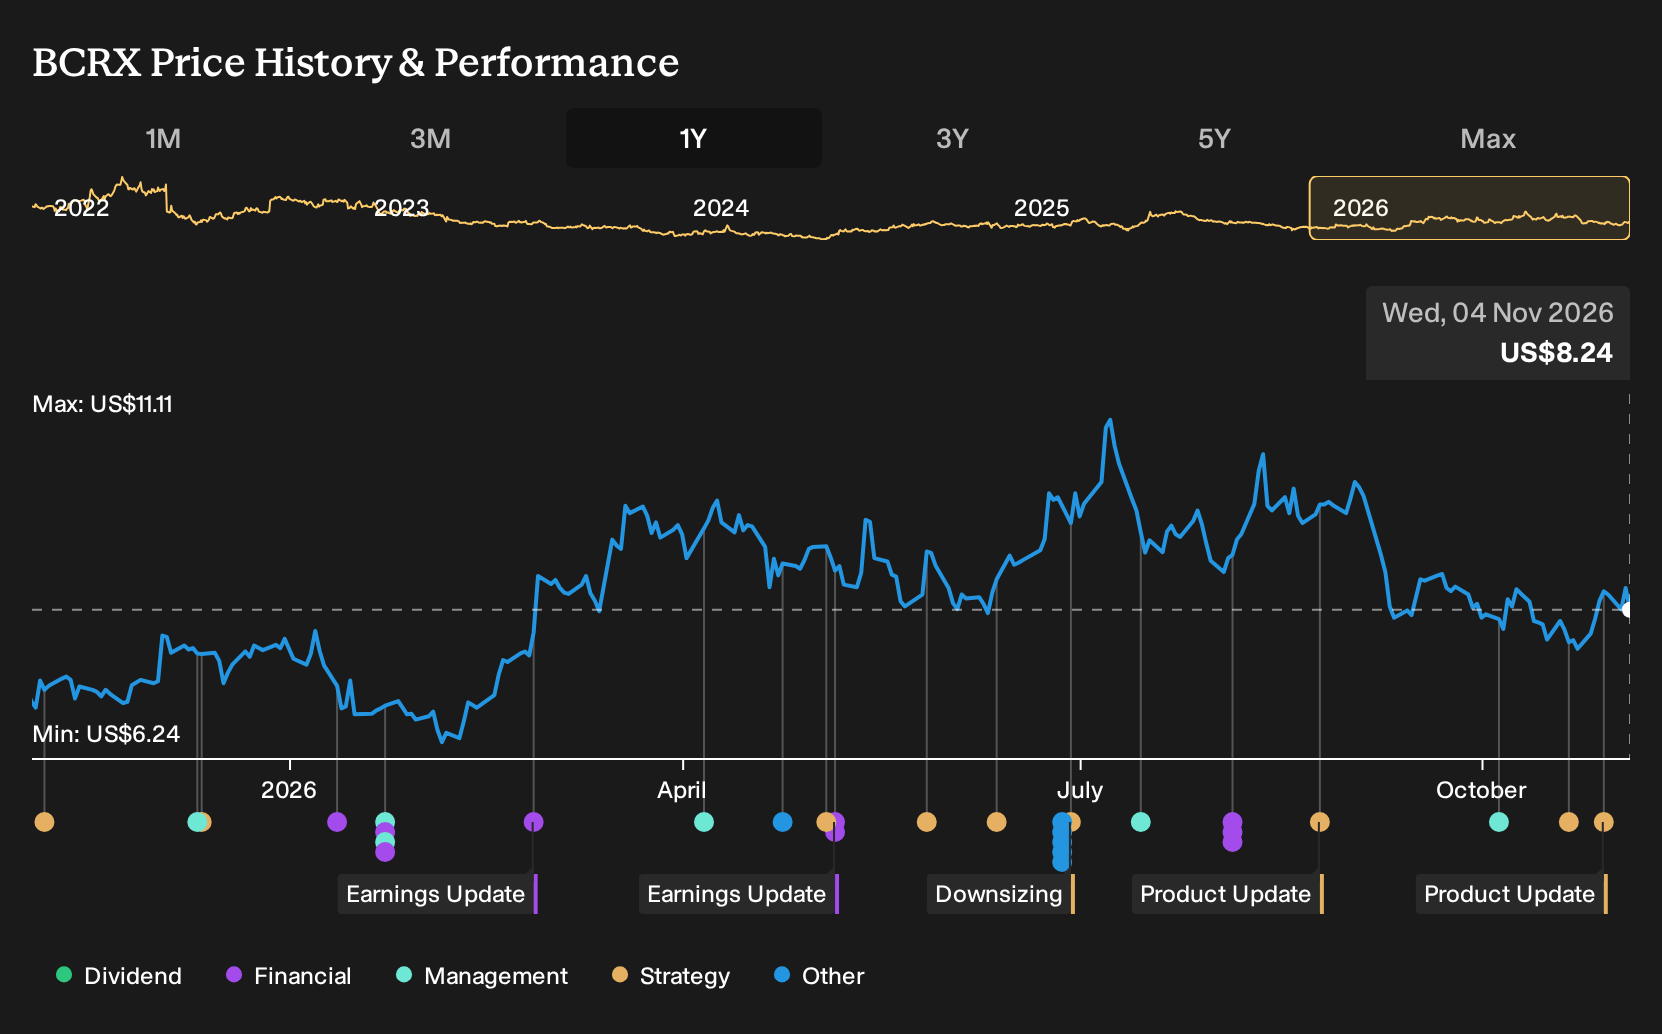
Exploring Other Perspectives
One bullish twist on BioCryst Pharmaceuticals focuses less on ORLADEYO itself and more on the shift toward external deals like Astria. Before this guidance hike, the most optimistic analysts were already modeling revenue of about US$1.0b and earnings of roughly US$723.7 million by 2029. That is far above consensus, and it shows how widely opinions can differ. Use this new outlook as a prompt to compare those older forecasts with your own expectations, and then decide which story you find more convincing.
Explore 3 other BioCryst Pharmaceuticals fair value estimates, including one that suggests as much as 929% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your BioCryst Pharmaceuticals research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for BioCryst Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BioCryst Pharmaceuticals' overall financial health at a glance.
Looking for more investment ideas beyond BioCryst Pharmaceuticals?
If BioCryst Pharmaceuticals sharpened your thinking about risk, returns and concentration in a single product, you can use that momentum to broaden your watchlist with a few focused stock shortlists from the Simply Wall St Screener.
- For investors hunting for mispriced quality rather than hype, you can consider stocks with strong fundamentals that still trade below estimated worth through our 35 high quality undervalued stocks.
- If capital preservation sits high on your agenda, you can target companies with sturdier finances and cleaner balance sheets using the list of solid balance sheet and fundamentals (24 results).
- Those who care about resilience and smoother return profiles can focus on companies with lower overall risk scores by starting with the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com