
Can Magnite (MGNI) Still Be Undervalued After A 211% Run?
Magnite has delivered a 53.3% share price gain over the past year, which naturally raises a question for anyone looking at the stock today. Is the current US$22.79 price still aligned with the cash flows the advertising technology business is expected to generate, or has the story moved ahead of the underlying numbers?
- Over the last 3 years, Magnite has returned 211.1%, which puts real weight on whether that share price climb can be supported by the cash its operations are expected to produce.
- Comscore's expanded partnership to bring Proximic’s predictive audiences and contextual tools into Magnite’s SpringServe video platform may support expectations for future connected TV cash generation if advertisers and publishers continue to adopt these capabilities.
- Prefer to judge Magnite on earnings? See why Magnite's 19.6x P/E tells a different valuation story.
For investors, the debate is whether Magnite's recent share price level is justified by the cash flows implied by its current intrinsic value estimates.
If you are weighing whether Magnite’s recent rerating is justified by its cash flows, it can help to see how that same question looks across 35 high quality undervalued stocks.
Does Magnite Look Undervalued on Cash Flow?
The Discounted Cash Flow (DCF) model here uses a 2 Stage Free Cash Flow to Equity approach to translate Magnite’s projected cash generation into today’s dollars. Latest twelve month free cash flow sits at about $216.7 million, and analyst projections point to higher annual free cash flow by 2030, followed by a gentler climb as the business matures in the model.
Those rising cash flow estimates, when discounted back and compared with the current US$22.79 share price, lead to an intrinsic value outcome that sits meaningfully above where the stock trades today. Comscore’s expanded integration of Proximic’s predictive audiences into Magnite’s SpringServe platform provides some context for why analysts assume ongoing free cash flow growth, because it relates directly to monetisation potential in connected TV. For investors, the key point is that the DCF output suggests the recent price move has not fully closed the gap implied by those cash flow forecasts. Find out what Magnite could be worth using our Discounted Cash Flow (DCF) estimate.
The Magnite Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Magnite pick up where the valuation puzzle leaves off and explain which assumptions on growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price on the Community page. Instead of a single model output, Narratives describe the future that those valuation numbers rely on so you can track how Magnite's actual progress compares with that path over time.
Magnite investors on the Community page are split between a CTV driven upside story and a DV+ pressured ceiling on what the stock can justify.
Bull case: 23% undervalued
"Magnite is positioned to benefit from the accelerating shift of ad spend from traditional TV to digital and connected TV platforms, with recent CTV contribution ex TAC of US$97 million at 51% of total..."
Discover why this Narrative puts Magnite at 23% undervalued.
Bear case: 9% overvalued
"Bearish analysts expect Magnite’s exposure to shrinking open-web browser traffic to cap DV+ contribution ex-TAC at flattish levels, while CTV growth must increasingly carry the business..."
Explore why this Narrative puts Magnite at 9% overvalued.
One more Magnite question that could matter even more than the model
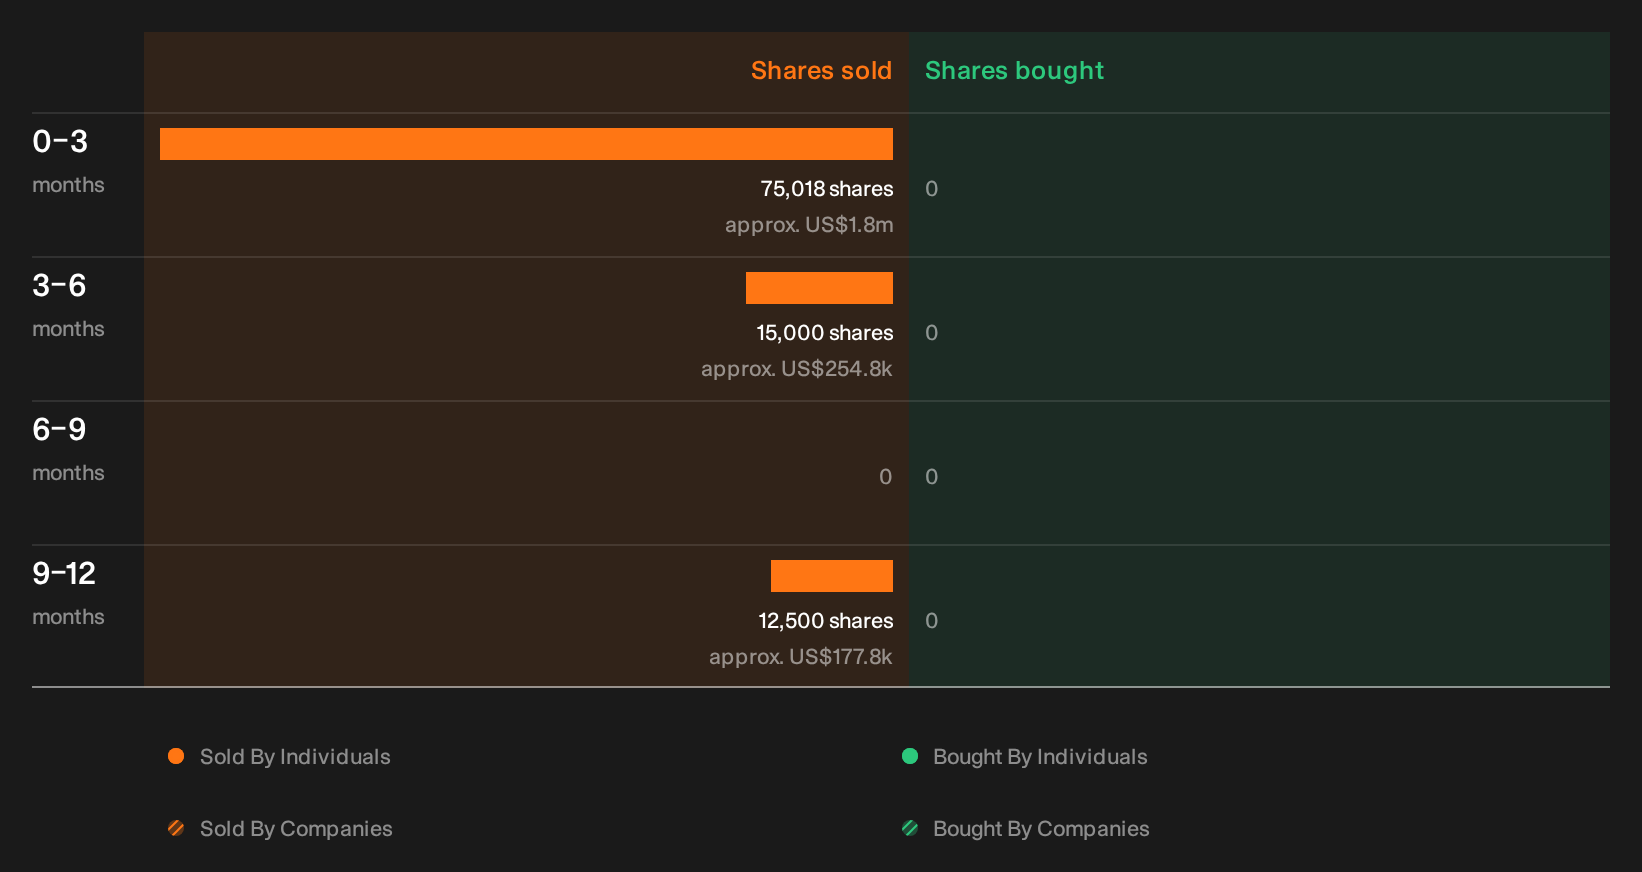
Valuation work only tells part of the story, and recent transactions by Magnite insiders can sometimes speak just as loudly as any cash flow forecast if you look closely at who is selling and how much. See the recent insider selling flagged for Magnite.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com