
Missed Hannover Rück's Rally? Here's The Bet Holders Made
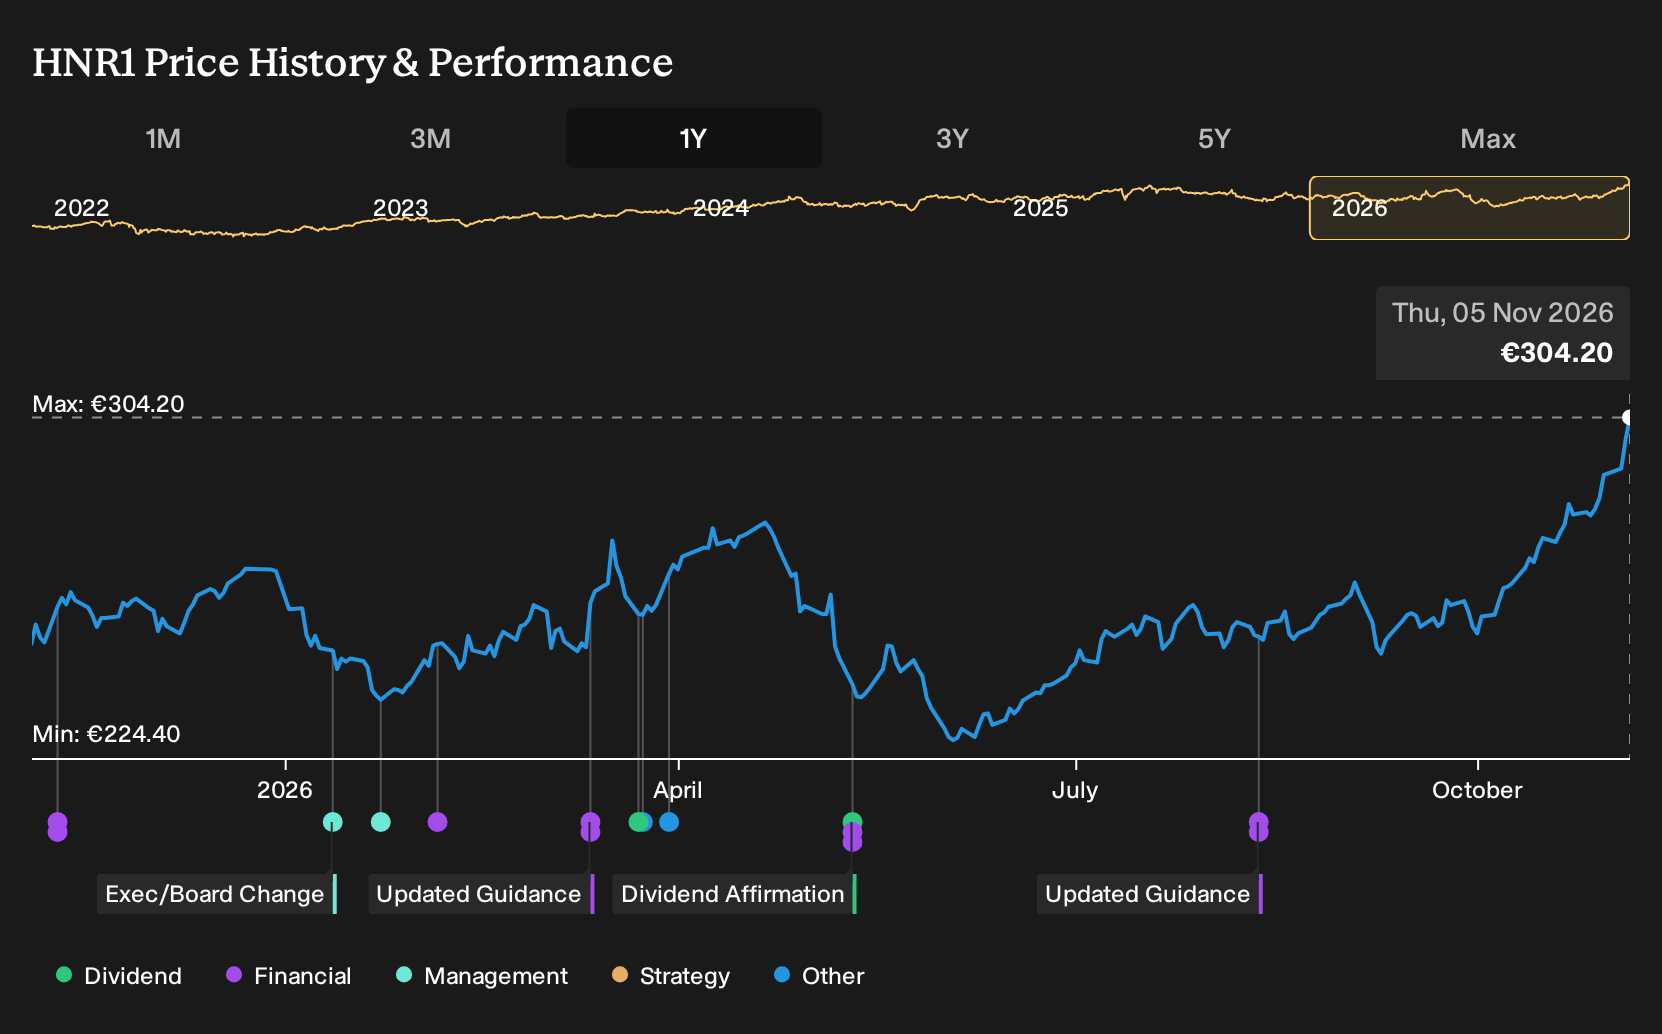
If Hannover Rück was on your watchlist instead of in your portfolio, the recent move may feel like a missed call. For Hannover Rück shareholders, the return over the past year was 27.9%, including dividends. Analysts were split at the start, with bulls focusing on emerging market demand and bears worried about softer property catastrophe pricing. The real question is whether confidence in expanding emerging market reinsurance was the key assumption to recognise before the gain arrived.
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
Hannover Rück has already moved. See which of 203 high quality undervalued stocks still trade below our estimates.
The Argument Hannover Rück Investors Faced Upfront
The shares cost €253 at the start of the period, and anyone looking at Hannover Rück then had to decide which story about the future felt more realistic.
On the optimistic side, the bull Narrative set Fair Value at €287, 14% above the start price. It leaned on emerging markets and structured reinsurance, assuming revenue would decline 0.9% a year while profit margins climbed from 8.4% to 9.6% by 2028.
The bearish story put Fair Value at €221, 13% below the start price. It focused on catastrophe exposure and softer property pricing, assuming revenue would grow 2.7% annually with margins rising from 8.1% to 9.2% despite pressure from alternative capital.
What The Results Changed For Hannover Rück
Hannover Rück’s Q2 2026 report gave both camps something to chew on. Revenue slipped from €7,182.9m to €5,511.2m and net income eased from €833.5m to €695.3m, which challenged the bullish hope for an expanding top line. Net margin still edged up from 11.6% to 12.6%, so profitability per euro of revenue supported the more cautious case.
The takeaway to reuse elsewhere is simple. When a story leans on efficiency and underwriting quality, track the net margin and combined ratio more closely than raw growth claims.
What Hannover Rück’s Price Already Bakes In
After a 27.9% total return over the past year, Hannover Rück now trades at €304. The selected Narrative’s Fair Value sits below that quote, framing today’s level as already embedding a confident read on earnings durability and capital strength.
The Narrative leans on strong solvency, Life & Health contributions and reserve buffers, yet questions how repeatable those supports really are. Anyone paying €304 is effectively assuming current profitability can hold up. The key question is how that thesis handles thinner P&C pricing and less repeatable investment gains.
"Even though Hannover Rück reports return on investment around 3.6% to 3.7% with reinvestment yields near 4.4%, a portion of the higher book yield comes from prior loss realizations that are not repeatable every year. Any moderation in reinvestment rates or reduced scope to recycle realized losses could cap future investment income growth and limit support for group earnings."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Which Company Could Surprise You Next?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 25% below our estimate - builds clinically supported probiotics as adult and oral health products outgrow legacy pediatric lines.
- Company 2 - 35% below our estimate - picks up more freight and customs work as AI related cargo and compliance needs expand.
- Company 3 - 17% below our estimate - attracts senior lawyers onto a dispersed platform as clients accept flexible, tech enabled legal service delivery.
That is three of the list. See the full list of 194 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com