
Planet Labs Stock In Focus After Farm AI Deal And Pelican 12 First Light
- Planet Labs PBC released its first light image from the Pelican-12 high resolution satellite, a 30 cm class capable spacecraft carrying NVIDIA Jetson edge compute and a new low latency communications demo, while FarmQA announced a collaboration that uses Planet imagery to build AI-based yield forecasting tools for enterprise agriculture.
- The pairing of higher resolution Pelican-12 data with FarmQA’s agronomic dataset indicates Planet Labs PBC is moving further into packaged decision tools, with emphasis shifting from raw imagery toward embedded, workflow-ready solutions for large agricultural customers.
- We will examine how Planet Labs PBC's investment narrative changes as Pelican-12 capacity connects directly into AI agronomic tools.
Compare Planet Labs PBC’s AI-powered earth observation story with a curated group of 53 AI infrastructure stocks riding the buildout of compute, data transport, and real-time analytics.
Planet Labs PBC Investment Narrative Recap
To own Planet Labs PBC, you need to buy into a world where high cadence imagery, higher resolution Pelican satellites and AI-ready data streams become embedded in customer workflows rather than bought as raw pixels. In the short term, the key swing factor is whether this model can translate strong forecast top line growth into a clearer path toward free cash flow, while maintaining larger accounts in long sales cycles.
The biggest near term risk is that building and launching new fleets like Pelican-12, along with the Berlin manufacturing ramp up, keeps cash needs high while profitability remains distant. If AI agronomy and satellite services contracts do not scale fast enough or geopolitical delays affect larger deals, revenue predictability and investor confidence could weaken.
The FarmQA collaboration is the clearest operational bridge between Pelican-12 and Planet Labs PBC’s solution-heavy pitch. Sugar beet yield forecasting may sound niche, yet it directly tests whether higher resolution, lower latency data and agronomic ground truth can justify larger, stickier contracts with cooperatives and enterprise agriculture customers.
As a catalyst, this partnership is a practical test case of the AI narrative that sits alongside the JSAT agreement and satellite services push. The key dependency risk is execution. Planet Labs PBC needs these kinds of deployments to convert constellation investment into recurring, workflow-level value, instead of leaving Pelican-12 as impressive but under-monetized capacity.
Planet Labs PBC's narrative uses analyst assumptions that revenue will reach US$788.4 million and earnings will be US$53.3 million by 2029. This implies 27.7% yearly revenue growth and an earnings swing of about US$413 million from a current loss of US$359.9 million.
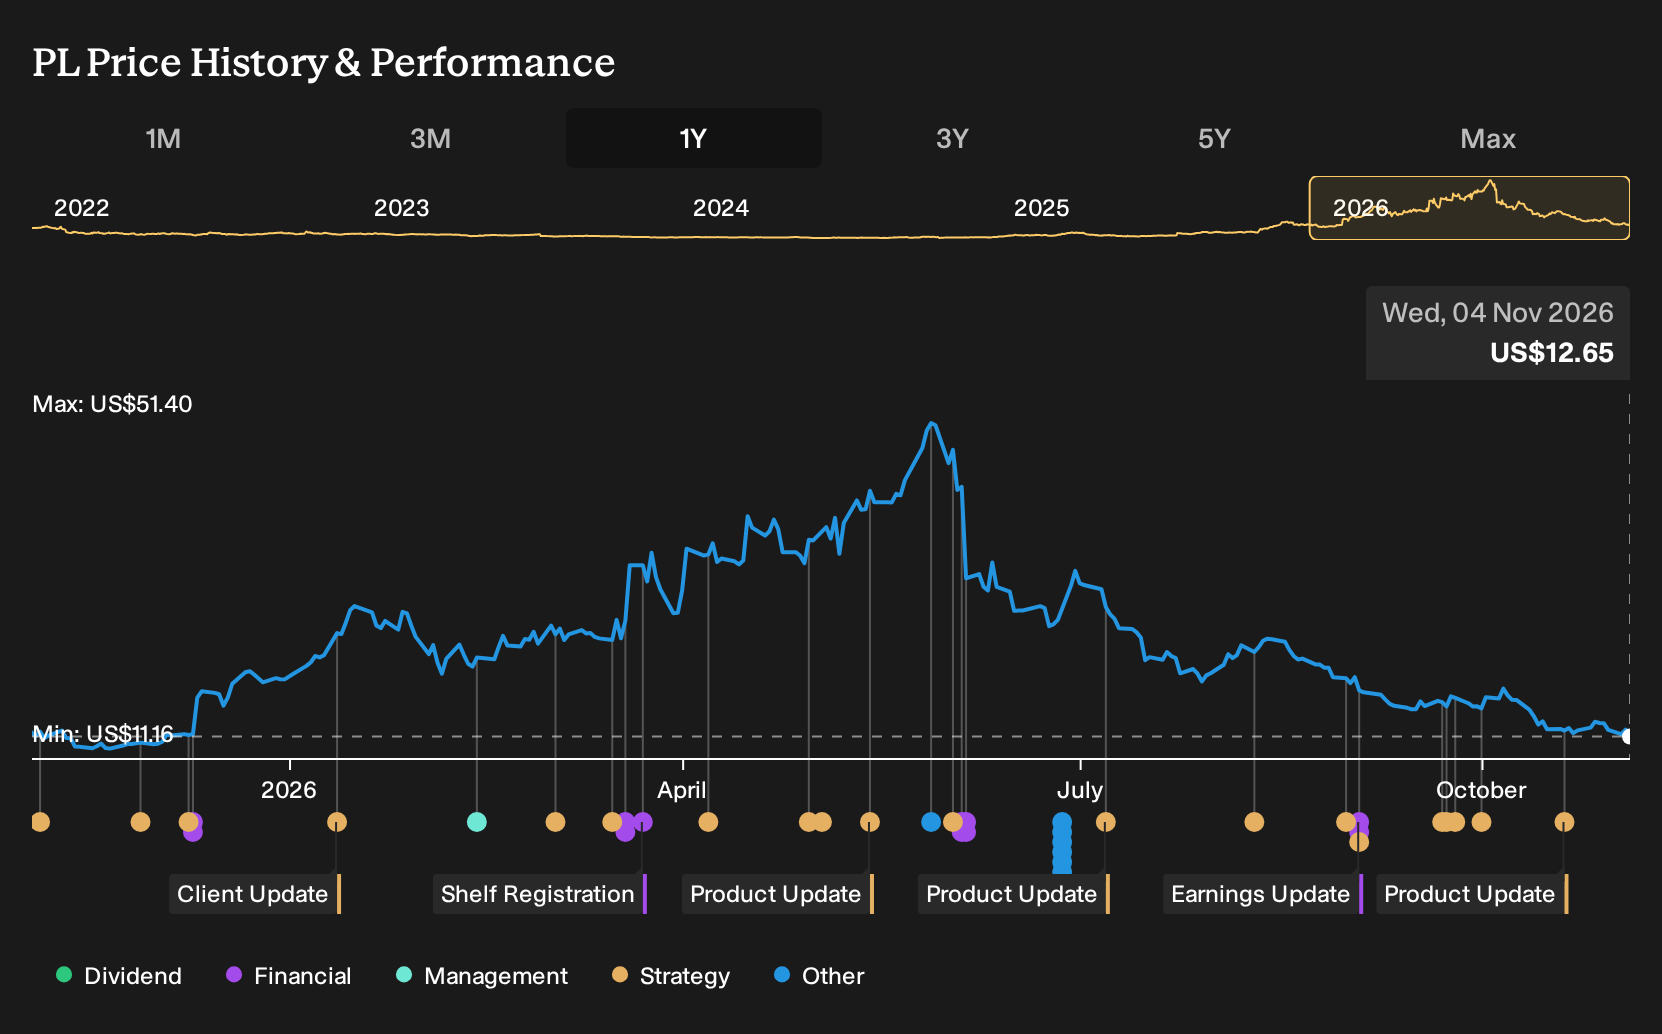
Uncover why Planet Labs PBC's fair value indicates a 139% potential upside to its current price; a discount that could close faster than expected.
Exploring Other Perspectives
One bullish twist on Planet Labs PBC focuses on the satellite services pipeline as the main catalyst. The most optimistic analysts were already using that story to justify revenue forecasts of about US$937.6 million and earnings of US$63.4 million by 2029. Those views pre date Pelican 12 and the FarmQA news, so readers should expect opinions to evolve and explore several possible paths rather than one fixed outcome.
Explore 8 other Planet Labs PBC fair value estimates, including one that suggests as much as 295% upside from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Planet Labs PBC research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Planet Labs PBC. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Planet Labs PBC's overall financial health at a glance.
Looking For More Investment Ideas Beyond Planet Labs PBC?
Once you have formed a view on Planet Labs PBC, it can help to zoom out and compare it with other potential opportunities that fit very different risk and income profiles. A flexible screener lets you move from a single stock story to a shortlist that actually matches your return goals and risk tolerance.
- If you want to keep risk in check while still hunting for returns, start with a 31 resilient stocks with low risk scores that already score well on resilience.
- For investors who care most about quality at a reasonable price, use the 35 high quality undervalued stocks to see which companies combine stronger fundamentals with what may be discounted share prices.
- If you prefer businesses with sturdier finances and less stretched balance sheets, filter for a list of solid balance sheet and fundamentals (24 results) and build a watchlist from there.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com