
Why It’s Time to Load Up on Arm Stock
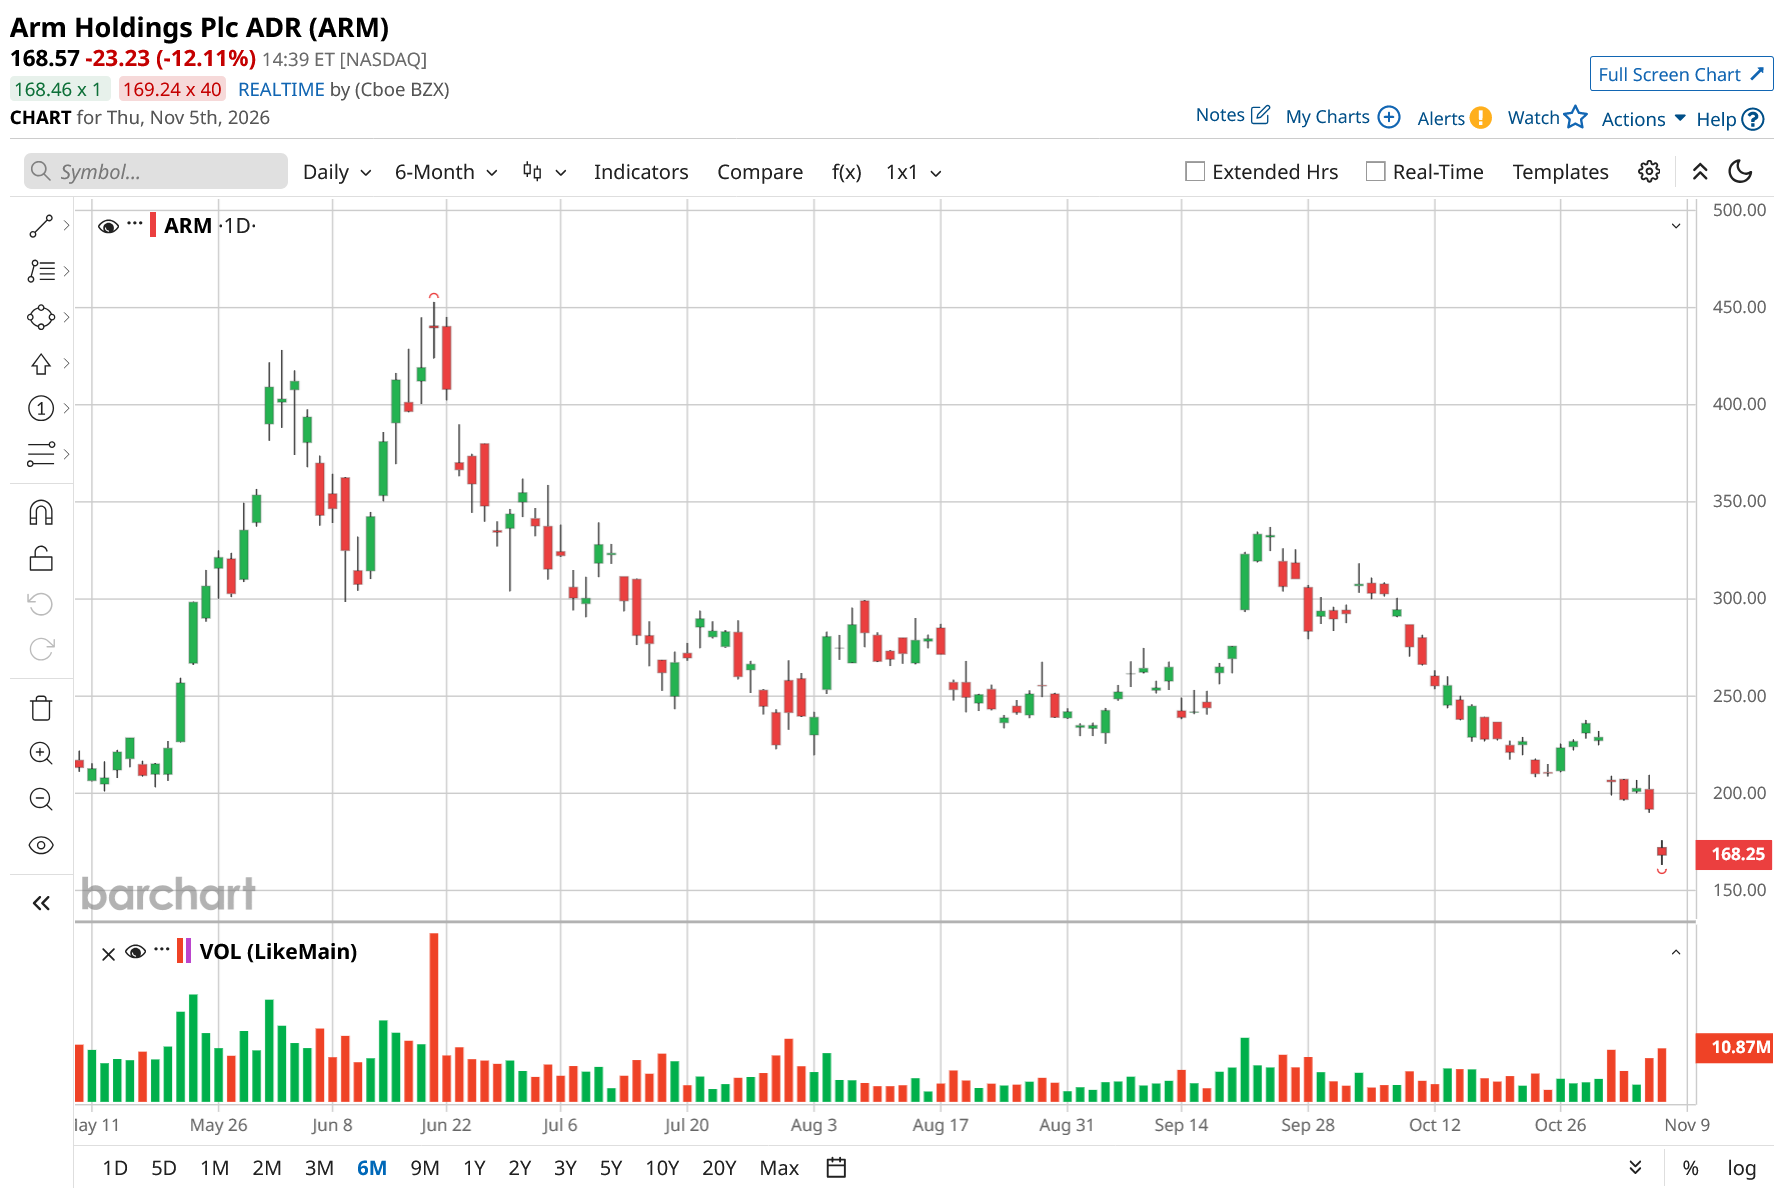
Arm Holdings (ARM) stock fell sharply, down 44% over the past month and trading about 63% below its 52-week high. The selloff in ARM stock intensified following the company's second-quarter earnings announcement, as concerns over slowing royalty revenue growth led by the softness in the smartphone market weighed on investor sentiment. Today's broad selloff in chipmakers and AI stocks hasn't done ARM stock any favors either.
Overall, however, Arm’s underlying business performance remains encouraging. Strong demand for ARM-based computing architectures helped drive solid growth in both revenue and earnings during the quarter. That said, the smartphone market continues to pose a challenge. Higher memory prices are weighing on smartphone demand, particularly in the mid- and lower-end segments, pressuring royalty revenue. Royalty revenue from edge AI applications was also broadly flat year-over-year (YoY).
Management expects these challenges to persist in the near term. While demand from cloud AI and physical AI is expected to support royalty growth, continued weakness in the smartphone market and tough YoY comparisons are likely to limit gains in edge AI. As a result, Arm expects royalty revenue to increase at a low teens rate sequentially but only at a low single-digit rate YoY, pointing to a further slowdown in growth.
Nevertheless, the royalty business is only part of the investment story. Arm continues to see strong demand for its licensing portfolio, which is expected to more than offset the near-term weakness in royalties. Growing adoption of its architecture across AI, cloud computing, and other high-performance computing applications provides solid growth opportunities.
Although the slowdown in royalty revenue and weakness in smartphone demand cannot be overlooked, the recent selloff has created a more attractive risk-reward opportunity.
Arm to Sustain Solid Growth Despite Smartphone Weakness
Arm reported a strong second quarter, and momentum will likely continue. Its revenue rose 27% YoY to $1.44 billion, marking its fifth consecutive quarter of growth above 20%. Growth was largely driven by a 50% increase in licensing revenue to $773 million, reflecting stronger customer demand for Arm's technology and Compute Platform. The higher licensing activity is encouraging, as it indicates that more customers are committing to Arm's architecture, which could translate into higher royalty revenue in the future.
Royalty revenue increased 8% YoY to $670 million, supported by strong demand from cloud AI and physical AI markets. Data center royalties doubled from the previous year as Arm-based CPUs gained traction across AI infrastructure and cloud computing. Physical AI royalties also grew 50%, driven by wider adoption of Arm technology in automotive and robotics.
However, edge AI growth remained relatively flat as higher memory prices continued to weigh on smartphone demand. This weakness was partly offset by higher royalty rates from the growing adoption of Armv9 and its Compute Subsystems (CSS). A recovery in smartphone demand could provide further support to royalty growth over time.
Arm’s bottom-line performance was also strong, with adjusted EPS increasing 33% to $0.52, outpacing revenue growth. Another positive development was the improving outlook for Arm's AGI CPU business. Management now sees the opportunity to generate up to $2 billion in revenue across FY2027 and FY2028, compared with its earlier expectation of more than $1 billion. This upbeat guidance follows new purchase orders from multiple customers and supply agreements with supply-chain partners.
Looking ahead to Q3, Arm expects revenue of approximately $1.54 billion, representing around 24% YoY growth, while adjusted EPS is projected at $0.56, up 30%. Licensing revenue is expected to remain strong, with growth above 50%. Royalty growth should continue to benefit from cloud and physical AI demand, although weaker smartphone sales and a challenging comparison base are likely to limit near-term growth.
Overall, Arm's business remains well-positioned to benefit from rising AI-related demand. While weakness in the smartphone market may weigh on near-term royalties, strong licensing activity, growing data center adoption, and contributions from AGI CPUs provide meaningful support for longer-term growth prospects.
ARM Stock's Selloff Is a Buying Opportunity
ARM stock's recent pullback has created an attractive entry point for long-term investors, despite near-term challenges in its royalty business. While persistent weakness in the smartphone market could constrain royalty growth, strong licensing demand, accelerating data center adoption, and the expanding opportunity in AGI CPUs provide multiple growth drivers.
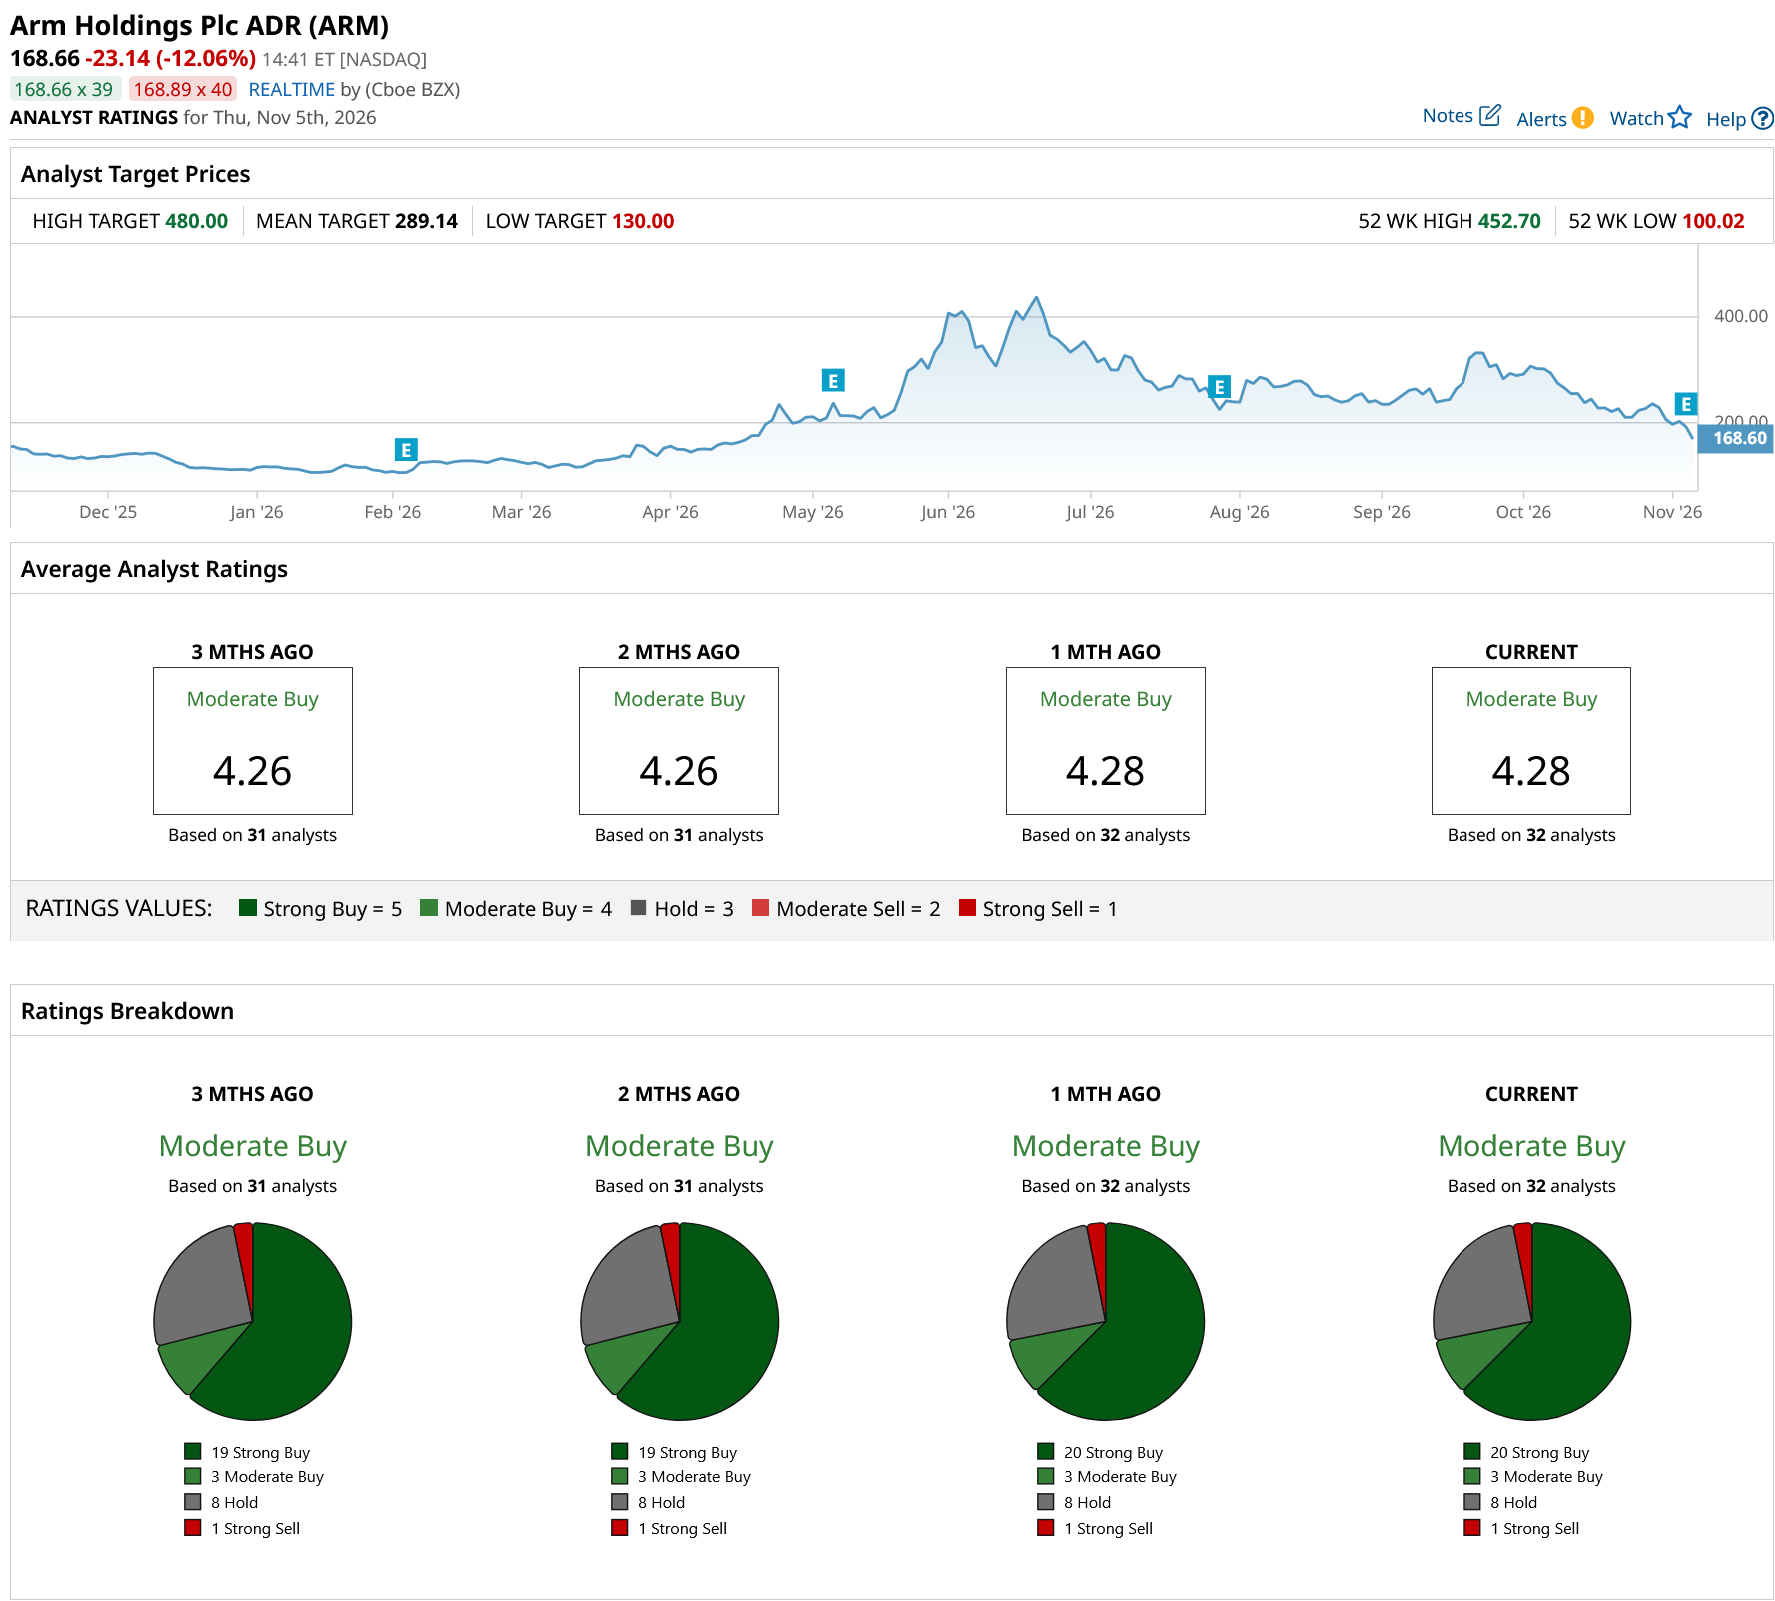
While analysts have a “Moderate Buy” consensus rating on ARM stock, its solid fundamentals and significant share price decline make it an attractive stock to consider now.
On the date of publication, Amit Singh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.