
Alamos Gold Stock In Focus After Mixed Q3 Results And Production Guidance
- Alamos Gold reported third quarter 2026 results with sales of US$510.4 million, net income of US$165.6 million, and quarterly gold output of 119,000 ounces, alongside updated 2026 production guidance of 510,000 to 560,000 ounces.
- The nine month figures show Alamos Gold pairing higher sales of US$1.7 billion and net income of US$627.4 million with lower year to date gold production than the prior year, which highlights the importance of pricing, mix, and cost control in the business model.
- The next step is to examine how Alamos Gold's mixed quarterly earnings, particularly the lower Q3 net income, may influence the existing investment narrative.
Compare Alamos Gold's latest earnings swing with other producers by scanning the handpicked 34 elite gold producer stocks that could be primed for their next big move.
Alamos Gold Investment Narrative Recap
To own Alamos Gold, you need to believe the company can convert its current project pipeline into stable, cash-generative Canadian operations while keeping inflation and technical issues in check. The latest quarter shows higher sales but lower net income versus a year ago, so cost pressure and grade mix remain front of mind for any shareholder.
The key short-term catalyst is execution at Island Gold and Magino, where throughput, grades and integration will shape unit costs and cash flow. The recent earnings swing does not yet change that core story. However, softer quarterly production and profit keep the risk of further cost guidance increases firmly on the table.
The most relevant update for this earnings print is Alamos Gold’s 2026 production guidance of 510,000 to 560,000 ounces. That range effectively sets the bar for how quickly the expansion projects and existing mines can deliver volume after a quarter where output and net income were both lower than the prior-year period.
For you as an investor, the question is how firmly that production band can be met in light of past cost inflation and project delays. Meeting the guidance would support the existing growth narrative built around Island Gold, Magino and Lynn Lake. Any sustained shortfall, by contrast, could compound cost risks and keep the focus on execution rather than expansion benefits.
Alamos Gold's narrative projects US$3.9b revenue and US$1.9b earnings by 2029. This assumes 19.8% yearly revenue growth and an earnings increase of about US$800m from US$1.1b today.
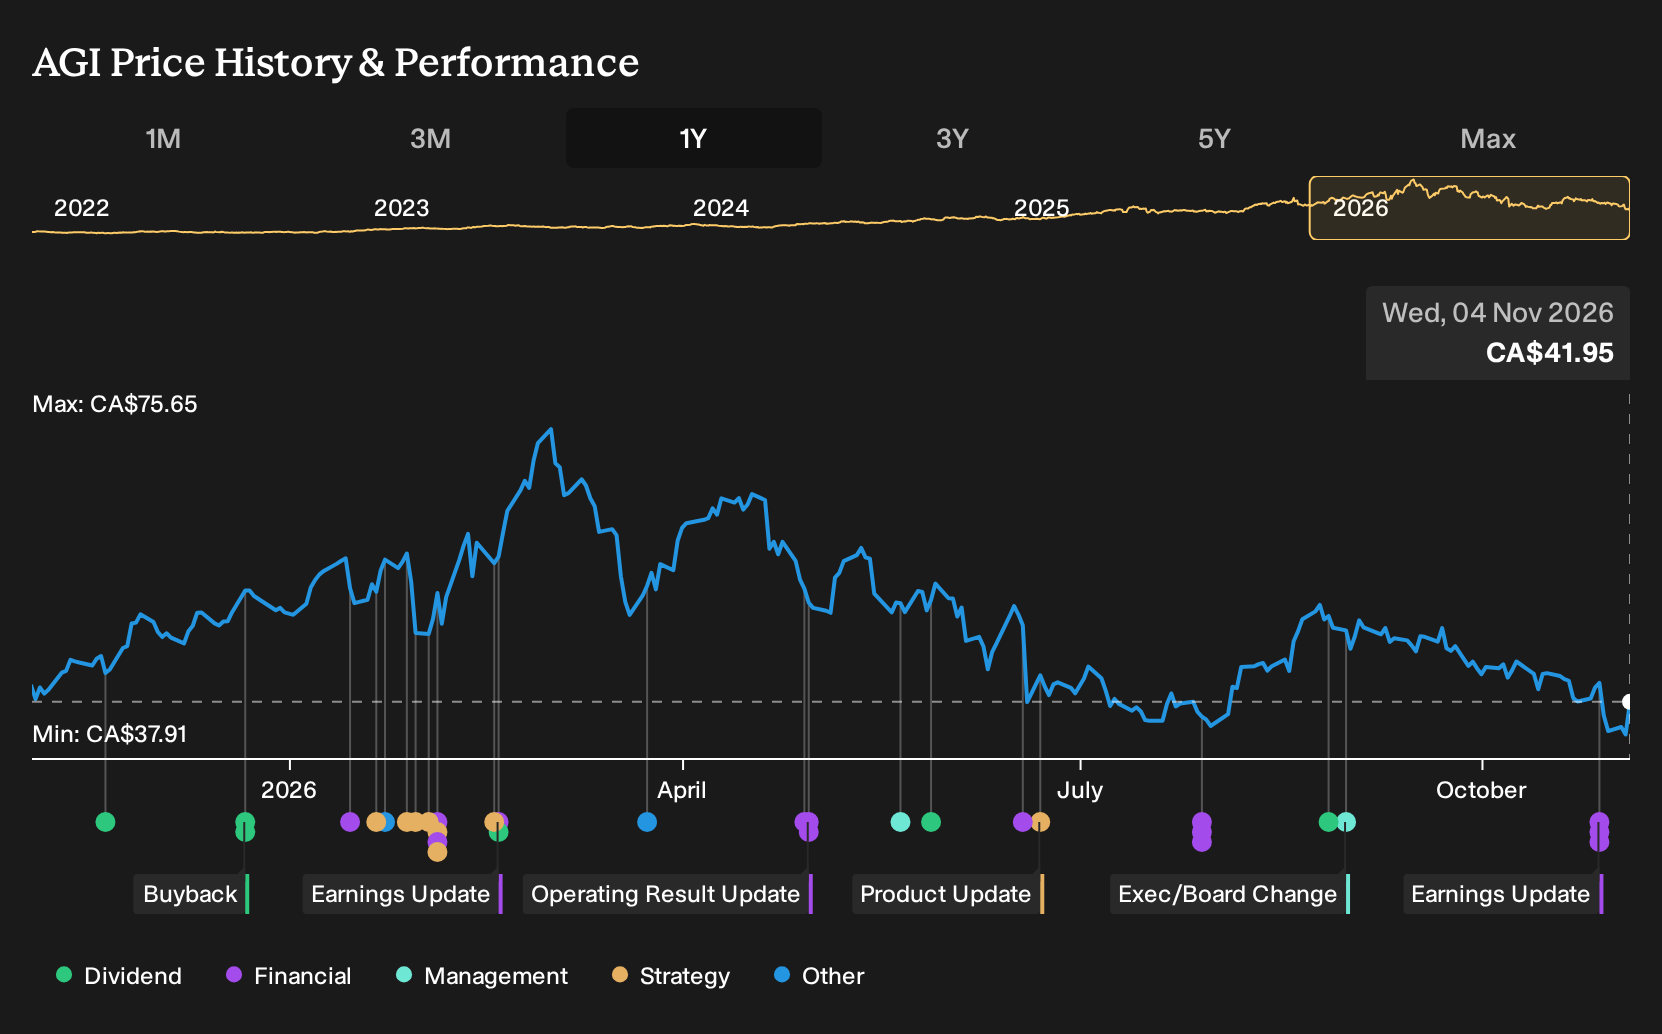
Uncover why Alamos Gold's fair value indicates a 53% potential upside to its current price before the discount to Alamos Gold closes.
Exploring Other Perspectives
One alternate view focuses less on production growth and more on costs staying stubbornly high. The most cautious Alamos Gold analysts were only penciling in revenue of about US$3.5b and earnings of roughly US$1.6b by 2029, compared with the baseline US$3.9b and US$1.9b. After this quarter’s earnings surprise, those expectations could shift again. It makes sense for you to compare both sets of assumptions and decide which story feels closer to how you see the business.
Explore 4 other Alamos Gold fair value estimates, including one that suggests it could be worth just CA$62.87.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Alamos Gold research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alamos Gold. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alamos Gold's overall financial health at a glance.
Looking For More Ideas Beyond Alamos Gold?
If Alamos Gold has sharpened your view on what you want from a miner, it can help to line it up against companies with very different profiles. Use the Simply Wall St Screener to spot other opportunities that match your risk tolerance and income needs instead of relying on one story alone.
- For investors who care most about financial resilience and clean balance sheets, start with this curated list of solid balance sheet and fundamentals (6 results) and see which businesses best fit your comfort zone.
- If your priority is stability with income, focus on companies in the 3 dividend fortresses that pair higher yields with fundamentals you can interrogate in detail.
- For those hunting for less crowded opportunities, broaden your radar with a 8 high quality undiscovered gems that may not yet be widely followed but still show robust underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com