
Is Zip Co (ASX:ZIP) Undervalued On Its Best Buy Nationwide Rollout?
Zip Co (ASX:ZIP) is back in focus after expanding its Best Buy partnership across all U.S. stores, letting shoppers use Zip’s tap to pay service in person at the checkout.
For context, Zip Co’s latest A$2.14 share price comes after a sharp 15.7% 1 day share price return and a 15.1% 7 day share price return, yet the stock is still down 25.2% on a 90 day share price basis and the 1 year total shareholder return has declined 40.7%. This comes even after a very large 3 year total shareholder return that sits in the hundreds of percent, suggesting short term momentum has picked up while longer term holders have experienced a bumpier ride.
Scan how Zip Co compares with other high momentum, flexible finance players by filtering for 14 high quality undiscovered gems that are already turning fast-changing consumer payment habits into real business traction.
The Best Buy rollout and sharp rebound in Zip Co’s share price have reset expectations fast. Has the real upside already been absorbed, or do the current valuation markers still leave meaningful room ahead?
Most Popular Narrative: 47% Undervalued
On the most followed view of Zip Co, a fair value near A$4.03 sits well above the latest A$2.14 close. This suggests the current Best Buy momentum story is only part of what followers are watching.
Scaling distribution through partnerships and embedded finance with major merchants and platforms (such as Google Pay, Stripe, and large retailers in key verticals) is decreasing customer acquisition costs and increasing take rates, which should drive further operating leverage and higher earnings.
See why 91 investors see Zip Co as 47% undervalued.
Result: Fair Value of A$4.03 (UNDERVALUED)
Still, rising regulatory pressure in the U.S. and Australia, along with any uptick in bad debts on newer products like Zip Cash, could quickly challenge that 47% undervalued story.
Find out about the key risks to this Zip Co narrative.
Another View On Zip Co’s Valuation
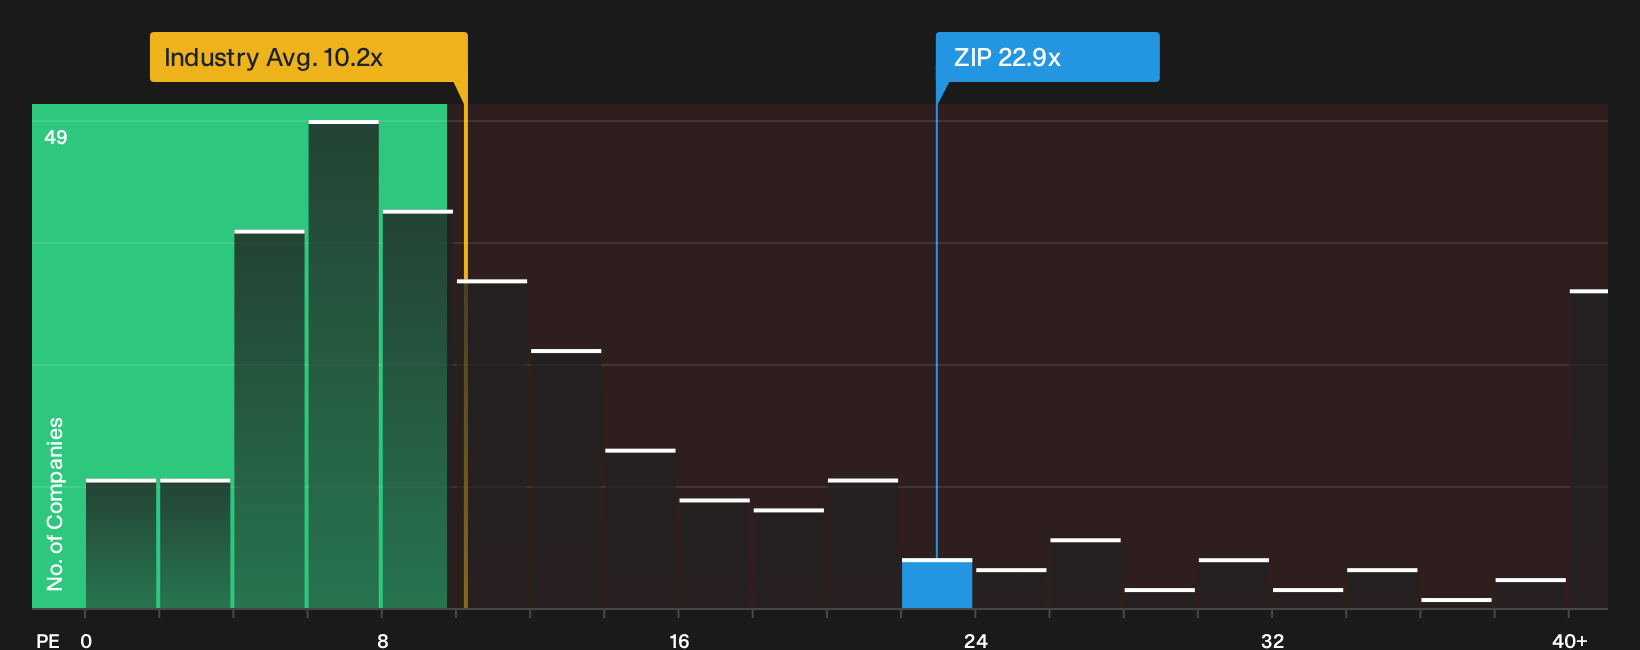
That 47% gap to A$4.03 rests on forward-looking fair value work. On current pricing, Zip Co trades on a P/E of 22.9x compared with 11.9x for domestic peers and 10.2x for the global consumer finance group, even though its own fair ratio sits closer to 23.1x.
This splits the picture for investors. The broader sector comparison points to a rich tag, while the fair ratio suggests the multiple is roughly in line with what the market could move toward if Zip Co keeps executing. Which reference point carries more weight for you when momentum cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Zip Co is split, with sharp price moves and mixed expectations on risk and reward. Consider acting promptly, weigh both sides, and check the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Zip Co?
If you stop with Zip Co, you only see one angle. Broaden your watchlist now and give yourself more ways to put capital to work.
- Target potential mispricing by scanning the market for companies screened as high quality yet out of favour using the 5 high quality undervalued stocks.
- Prioritise resilience first and sort for businesses with stronger balance sheets and healthier fundamentals through the list of solid balance sheet and fundamentals (12 results).
- Focus on companies highlighted as 5 dividend fortresses if you are interested in dividend-paying shares.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com