
Mesoblast (ASX:MSB) Refreshes Its Board, Is It Still Below Fair Value?
Mesoblast (ASX:MSB) has shifted investor attention to its boardroom after announcing the planned retirement of long-serving directors and a push to recruit new members with global commercial biopharma experience.
Recent trading reflects that shift in focus. Mesoblast’s share price is A$2.17, with a 1-day share price return of 3.33% and a 30-day share price return of 10.43%. However, the year-to-date share price return is down 21.66%, while the 3-year total shareholder return is very large, suggesting longer term holders have seen strong gains even as near term momentum has been mixed.
Spot opportunities around Mesoblast’s boardroom pivot by scanning a curated 14 high quality undiscovered gems that could also be quietly repositioning for their next phase of commercial growth.Mesoblast has already delivered a very large 3 year shareholder return, yet the stock is still trading below analyst targets and an intrinsic value estimate. Is the bigger opportunity still ahead, or has most of it already been priced in?
Most Popular Narrative: 39% Undervalued
Mesoblast’s most followed valuation storyline pegs fair value at about A$3.59 per share, compared with the last close at A$2.17. This puts that board refresh firmly in the context of a business priced well below this narrative estimate while still unprofitable today.
The first and only FDA approved mesenchymal stromal cell product in the U.S., Ryoncil, together with over 1,100 patents and established commercial scale manufacturing, positions Mesoblast to benefit if cell therapies gain wider medical adoption. This would be most visible in revenue growth and operating leverage.
See why 16 investors see Mesoblast as 39% undervalued.
Result: Fair Value of A$3.59 (UNDERVALUED)
Still, the Mesoblast story leans heavily on successful label expansions and assumes that Ryoncil usage scales fast enough so that current cash burn does not force fresh capital raises.
Find out about the key risks to this Mesoblast narrative.
Another View: Mesoblast On Sales Multiples
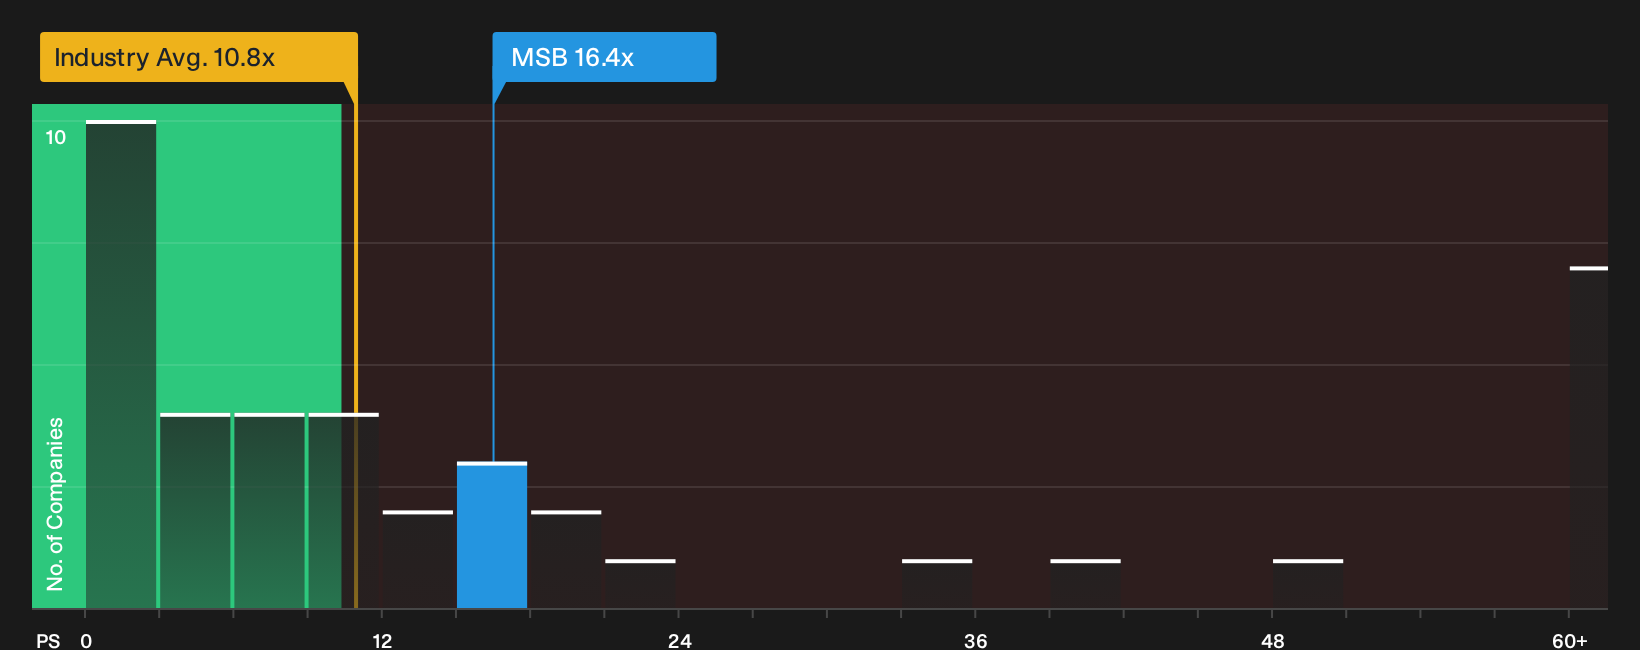
The DCF and analyst narrative both lean toward Mesoblast appearing inexpensive, yet the current A$2.17 price tells a different story when viewed through sales multiples. The stock trades on a P/S of 16.4x, compared with about 10.8x for the Australian Biotechs industry and a fair ratio estimate of 10.6x.
That gap suggests the market already assigns Mesoblast a premium relative to peers and the fair ratio. This can mean less room for error if revenue or margin expectations change. The key question is whether this represents a quality premium that persists or a valuation stretch that narrows if sentiment shifts.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Mesoblast is split, with some investors focusing on valuation upside and others watching execution risk closely. Act while the data is fresh and pressure test the thesis for yourself, then weigh those potential upsides through the 3 key rewards.
Looking for more Mesoblast investment ideas?
If Mesoblast has your attention, do not stop there. Use the same disciplined lens across other opportunities so you are not relying on a single story.
- Target potential mispricing by scanning a focused group of companies that screen as quality yet potentially overlooked through the 5 high quality undervalued stocks.
- Prioritise resilience first by reviewing a 6 resilient stocks with low risk scores that aims to keep capital at work while limiting unwelcome surprises.
- Broaden your watchlist with a list of solid balance sheet and fundamentals (12 results) that may handle shocks better and support more consistent execution over time.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com