
Earnings Beat May Change The Case For GEO Group Stock
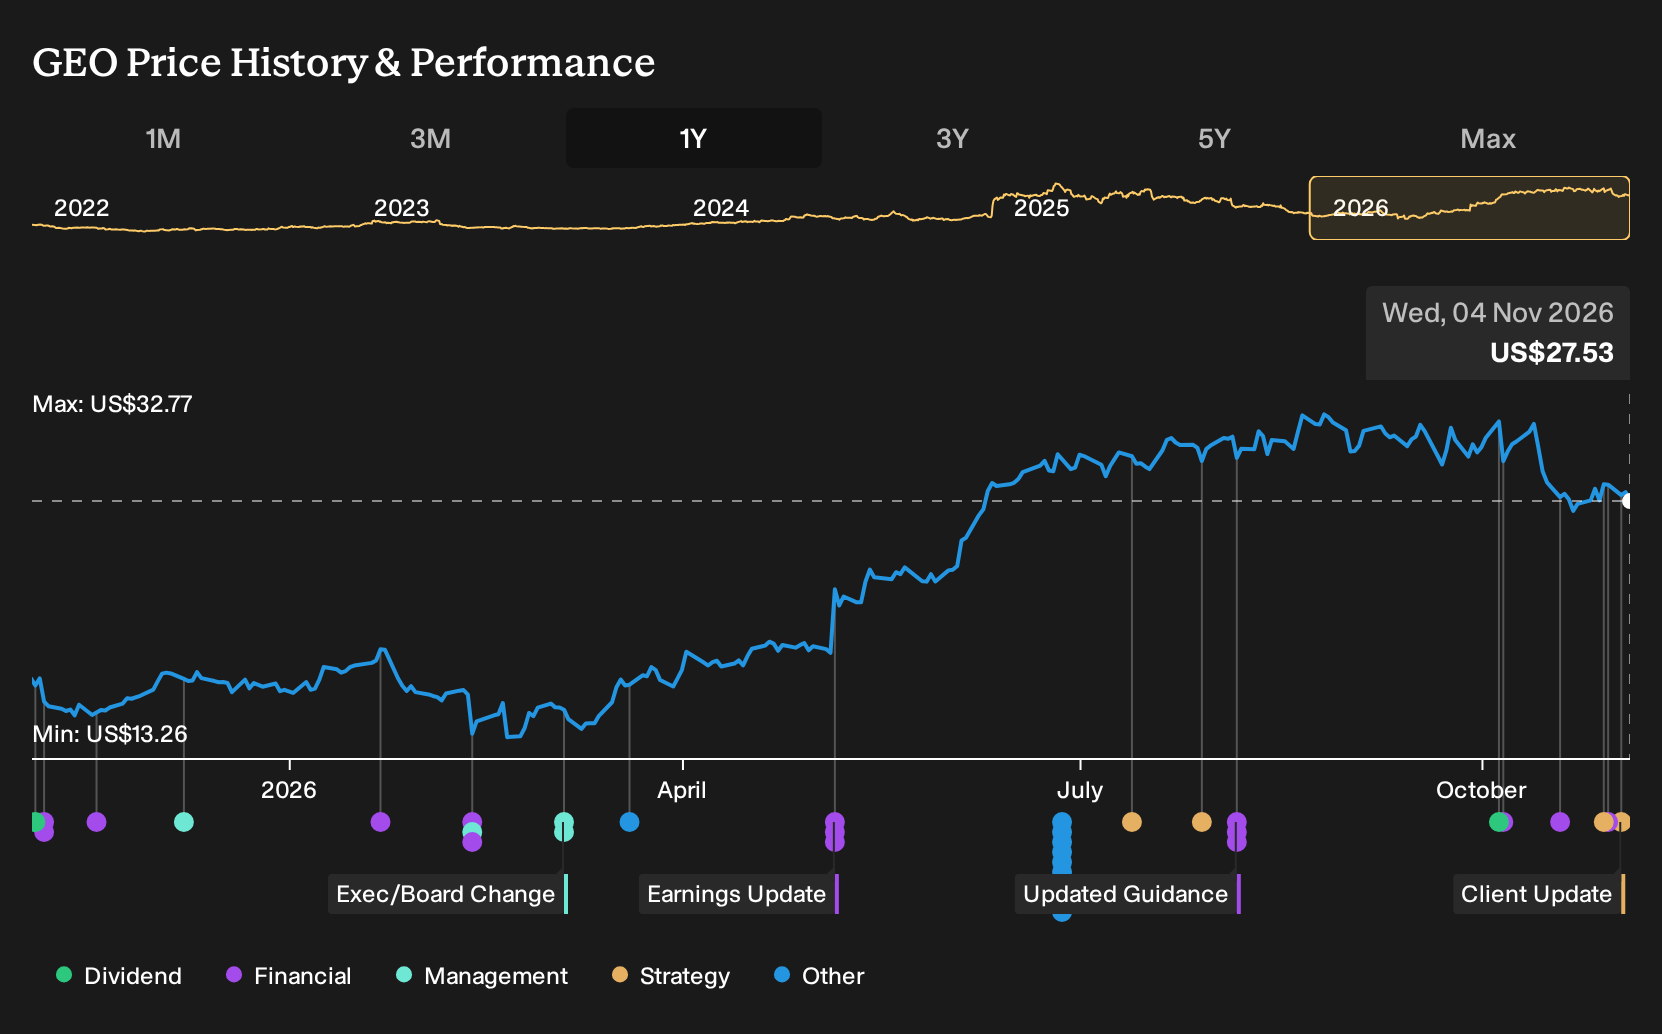
- GEO Group reported third quarter 2026 sales of US$761.06 million and net income of US$49.21 million, alongside record revenue and adjusted EBITDA, and raised its full year 2026 guidance while expanding its share repurchase program to US$1.25 billion through 2029.
- Alongside these results, GEO Group secured two 10 year ICE service agreements in Texas and Washington that are expected to contribute roughly US$340 million in combined annual revenue, while also completing a US$950 million facility sale that supports balance sheet flexibility and ongoing capital returns.
- We will now examine how GEO Group's record quarterly performance and higher full year guidance could reshape the investment narrative around detention exposure.
Scan beyond GEO Group and compare it with a curated list of solid balance sheet and fundamentals (24 results) that benefits from resilient funding options and disciplined capital allocation.
GEO Group Investment Narrative Recap
To own GEO Group, you need to be comfortable with a detention focused business that leans heavily on multi year US government contracts and ICE funding decisions. The big short term swing factor is how quickly new and renewed agreements translate into stable occupancy and cash flow. Third quarter 2026 results showed record revenue but lower net income, which keeps execution on profitability and interest coverage firmly in focus.
The largest immediate risk is policy and budget reversals that could reduce ICE bed demand after GEO commits resources to activate or expand facilities. Legal, political, and reputational scrutiny highlighted in recent reports could also feed into contract renewals or operating costs. The latest earnings beat and higher guidance do not remove those pressures; they just give GEO more room to manage through them.
The fresh 10 year ICE contracts in Big Spring, Texas and Tacoma, Washington matter most for this earnings story. Together they are expected to add about US$340 million in yearly revenue once fully up and running, which directly links to the detention capacity and idle bed activation thesis many investors are watching. For a business tied to a small number of large customers, that kind of multi year volume can be central to confidence in the model.
Those agreements also sit alongside GEO Group’s US$950 million Adelanto facility sale and expanded US$1.25 billion share repurchase program through 2029. The sale introduces more balance sheet flexibility, while the repurchase authorization signals a willingness to use cash for capital returns if operations support it. For you as a shareholder, the key question is whether these long term ICE commitments and asset moves offset the policy and legal overhang that still defines GEO’s risk profile.
Analysts expect GEO Group to generate about US$3.8b in revenue and US$137.8 million in earnings by 2029, which implies annual revenue growth of 9.9% and an earnings decline of roughly US$153.7 million from current earnings of US$291.5 million.
Uncover why GEO Group's fair value indicates a 37% potential upside to its current price, which could narrow quickly if GEO Group keeps meeting contract milestones.
Exploring Other Perspectives
One alternate view on GEO Group focuses on the risk that federal appropriations stall again. Before this week’s contracts and earnings, the most cautious analysts were working off roughly US$3.7b in 2029 revenue and about US$250.0 million in earnings. That is a much cooler story. Use that gap as a prompt to explore multiple scenarios, not a verdict.
Explore 3 other GEO Group fair value estimates, including one that suggests it could be worth just $37.75!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your GEO Group research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for GEO Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GEO Group's overall financial health at a glance.
Looking For More GEO Group Sized Ideas?
If GEO Group has sharpened your focus on balance sheets, cash generation, and contract risk, use that same checklist across a wider watchlist. The Simply Wall St Screener can help you filter for companies that fit the profile you care about, then compare their fundamentals side by side.
- If you want potential mispricing to work in your favor, start with companies that look attractively valued on both earnings and cash flow using the 35 high quality undervalued stocks.
- If resilience matters more to you than excitement, build a shortlist around lower risk profiles and steadier financial metrics through the 31 resilient stocks with low risk scores.
- If you prefer to hunt in less crowded corners of the market, focus on under-followed businesses with solid fundamentals via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com