
PLS Group (ASX:PLS) Could Be 22% Undervalued On Fortescue Power Deal
PLS Group (ASX:PLS) moved back into focus after signing a 20-year power purchase agreement with Fortescue, securing renewable power for its Pilgangoora Operation and supporting A$1.9b of planned expansion.
The Fortescue agreement comes after a difficult period for PLS Group’s shares, with the 30-day share price return down 25.72% and the 90-day move down 38.21%, while the 5-year total shareholder return remains up 29.12%.
Scan the renewable and resources space beyond PLS Group by reviewing the hand picked 33 best rare earth metal stocks positioned around long term electrification and energy transition themes.
Bulls point to long-term renewable power and expansion plans, while bears focus on recent share price declines and lithium volatility. Which case does PLS Group’s current valuation lean toward as you weigh the numbers next?
Most Popular Narrative: 22% Undervalued
PLS Group closed at A$2.83, while the most followed narrative assigns a fair value of A$3.63 using an 8.86% discount rate. That view leans on Pilgangoora’s mine life and expansion plans rather than any short term bounce in lithium pricing.
The question now is whether the setup is right to repeat that success. As a tier one lithium asset with strong long term fundamentals, PLS remains a premier vehicle for the sector. If you can look past the short term cyclical noise and let time work in your favour, some investors see PLS as offering a compelling long term investment case once again. The key consideration is the price paid and the level of market pessimism at the time of entry.
See why 1 investors see PLS Group as 22% undervalued.
Result: Fair Value of A$3.63 (UNDERVALUED)
Still, the narrative can crack if lithium prices stay weak through the P2000 spend, or if project costs rise again and squeeze PLS Group’s balance sheet.
Find out about the key risks to this PLS Group narrative.
Another View: PLS Group Looks Expensive On Earnings
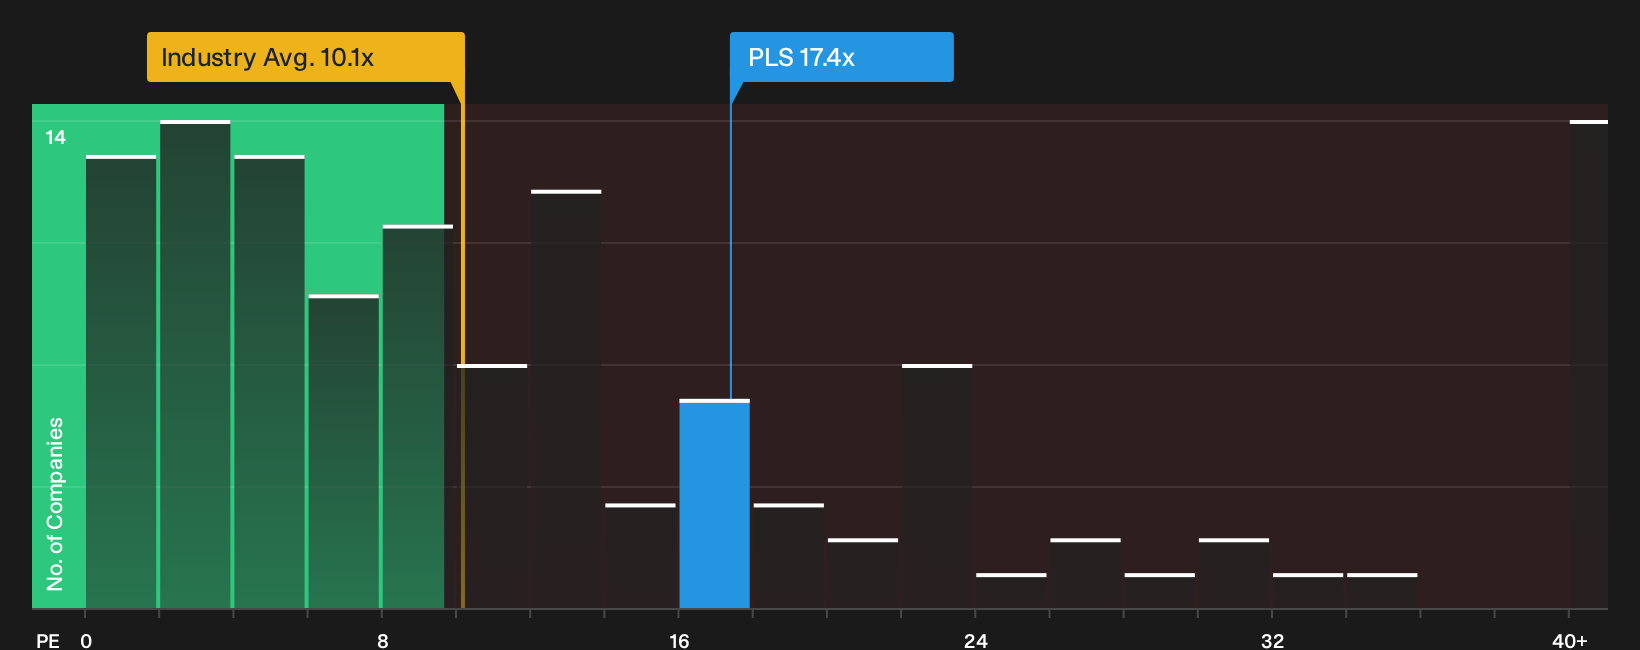
On cash flow work, PLS Group screens as undervalued, yet its A$2.83 share price implies a P/E of 17.4x. That is richer than both the Australian Metals and Mining industry on 10.1x and the stock’s own fair ratio of 13.7x. The gap suggests investors are paying up for earnings that are not forecast to grow quickly. How comfortable are you with that trade off?
For a closer look at what the numbers imply for this price, review the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the mix of optimism and concern around PLS Group feels finely balanced, take that as a cue to review the data yourself and decide where you stand. To see what investors are finding encouraging right now, review the 3 key rewards.
Looking for more investment ideas beyond PLS Group?
Do not stop your research with PLS Group alone. Broaden your watchlist with targeted ideas that match your style before the best setups move without you.
- Spot potential turnaround stories by scanning the 22 elite penny stocks with strong financials that already show healthier financial footing than many peers.
- Anchor your portfolio around sturdier balance sheets by reviewing the list of solid balance sheet and fundamentals (12 results) that could better handle tougher conditions.
- Hunt for under-the-radar potential by checking the 14 high quality undiscovered gems that pair quality fundamentals with limited current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com