
Why Did Qantas Airways (ASX:QAN) Shares Climb Today?
Qantas Airways (ASX:QAN) moved sharply higher after a drop in oil prices eased concerns about future fuel costs, even as the Reserve Bank of Australia pushed its cash rate to 4.85%.
That surge comes after a choppy period for Qantas Airways, where the 90 day share price return fell 10.6% and the year to date share price return declined 9.91%, even though the 3 year total shareholder return is up 95.32% and 5 year total shareholder return is up 84.91%.
Spot under-pressure travel plays that are reacting to the same fuel and rate backdrop as Qantas Airways by scanning our hand picked 6 resilient stocks with low risk scores in a few minutes.Qantas Airways has bounced hard on cheaper fuel and a solid track record, yet the share price is still below recent highs. Has most of the easy upside already played out, or is valuation support still building?
Most Popular Narrative: 17% Undervalued
On the most followed view, Qantas Airways carries a fair value of A$11.42 using a 9.25% discount rate, compared with a last close of A$9.45. This frames the recent rebound as only part of the gap that narrative followers see.
The shift toward higher premium cabin density and ultra long haul flying, including Project Sunrise and wider A350 and 787 deployment, is targeted to lift Qantas International EBIT margin from 4% in FY26 to 10% by FY31. Sunrise alone is expected to add A$400 million of EBIT, which would raise group earnings and potentially support higher returns on capital.
See why 57 investors see Qantas Airways as 17% undervalued.
Result: Fair Value of A$11.42 (UNDERVALUED)
Still, if fuel and carbon charges stay elevated or new aircraft and training costs linger, the bullish Qantas Airways margin story could quickly fray.
Find out about the key risks to this Qantas Airways narrative.
Another View On Qantas Airways: Cash Flows Paint A Harsher Picture
The popular narrative has Qantas Airways looking undervalued against an A$11.42 fair value. However, the SWS DCF model tells a very different story. Through a cash flow lens, Qantas Airways at A$9.45 screens well above an estimated future cash flow value of A$4.63, which flags the stock as overvalued instead. This raises the question of which signal investors might focus on when earnings optimism and cash flow analysis appear to diverge.
For readers who want to see how this cash flow result is built line by line, and how sensitive it is to the moving parts in the Qantas Airways story, Look into how the SWS DCF model arrives at its fair value.
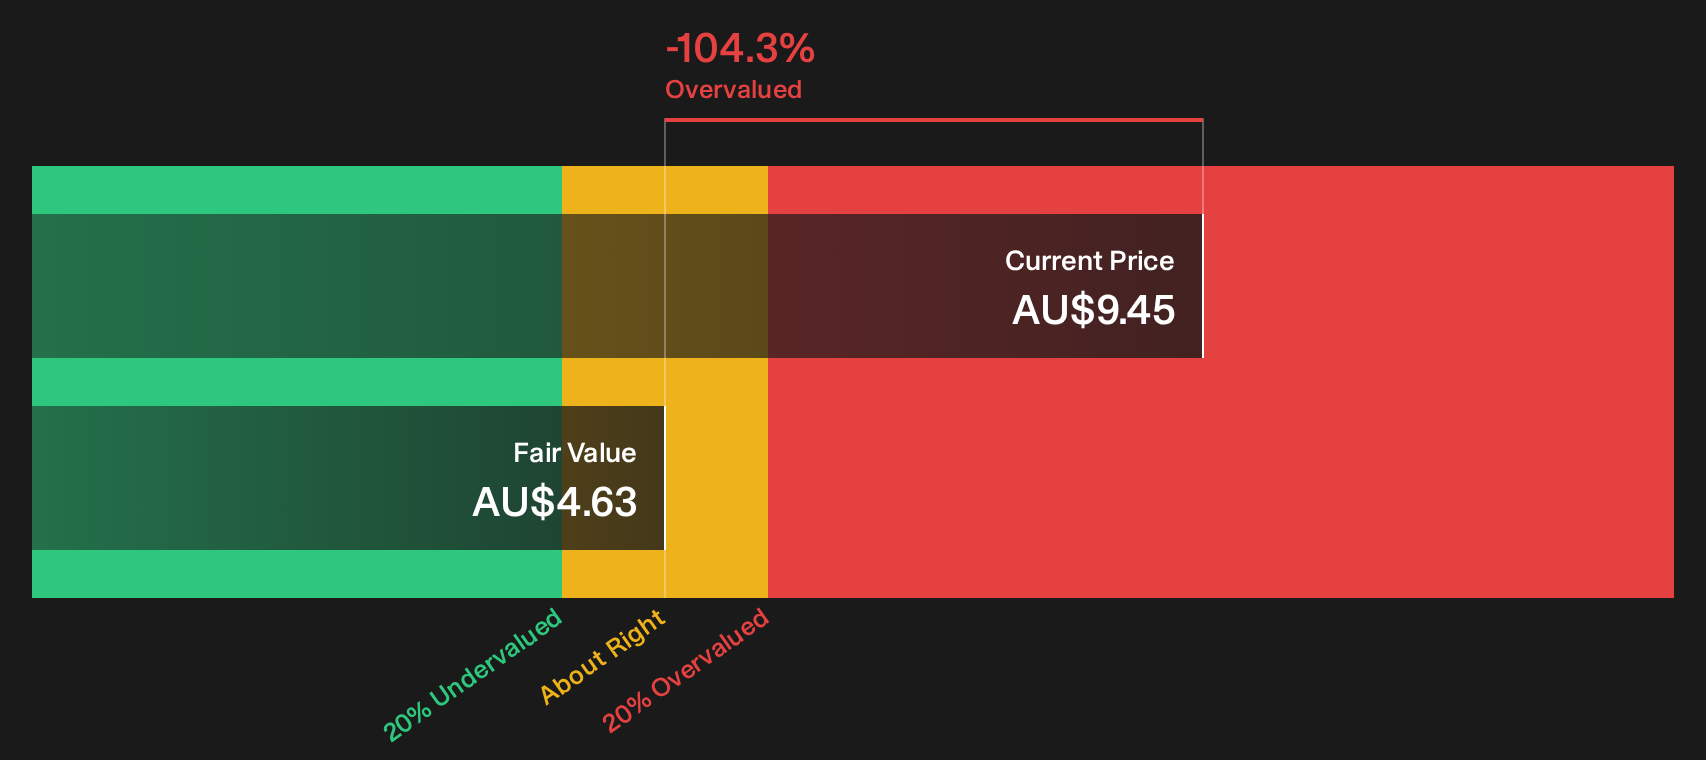
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Qantas Airways for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 5 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by the mix of optimism and doubt around Qantas Airways right now? Act while the facts are fresh and weigh both sides yourself with 3 key rewards and 3 important warning signs.
Looking for more Qantas Airways investment ideas?
If Qantas Airways is on the watchlist, do not stop there. Use the screener to pressure test your thinking and uncover fresh opportunities you might otherwise miss.
- Target resilient potential by reviewing a 6 resilient stocks with low risk scores that could hold up better when conditions turn awkward.
- Hunt for stronger value by scanning a 5 high quality undervalued stocks that may offer more compelling price tags than Qantas Airways today.
- Build a cash focused watchlist by filtering for a 5 dividend fortresses that can keep income flowing while you assess Qantas Airways.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com