
Bond Offer Might Change The Case For Investing In Auckland Airport Shares
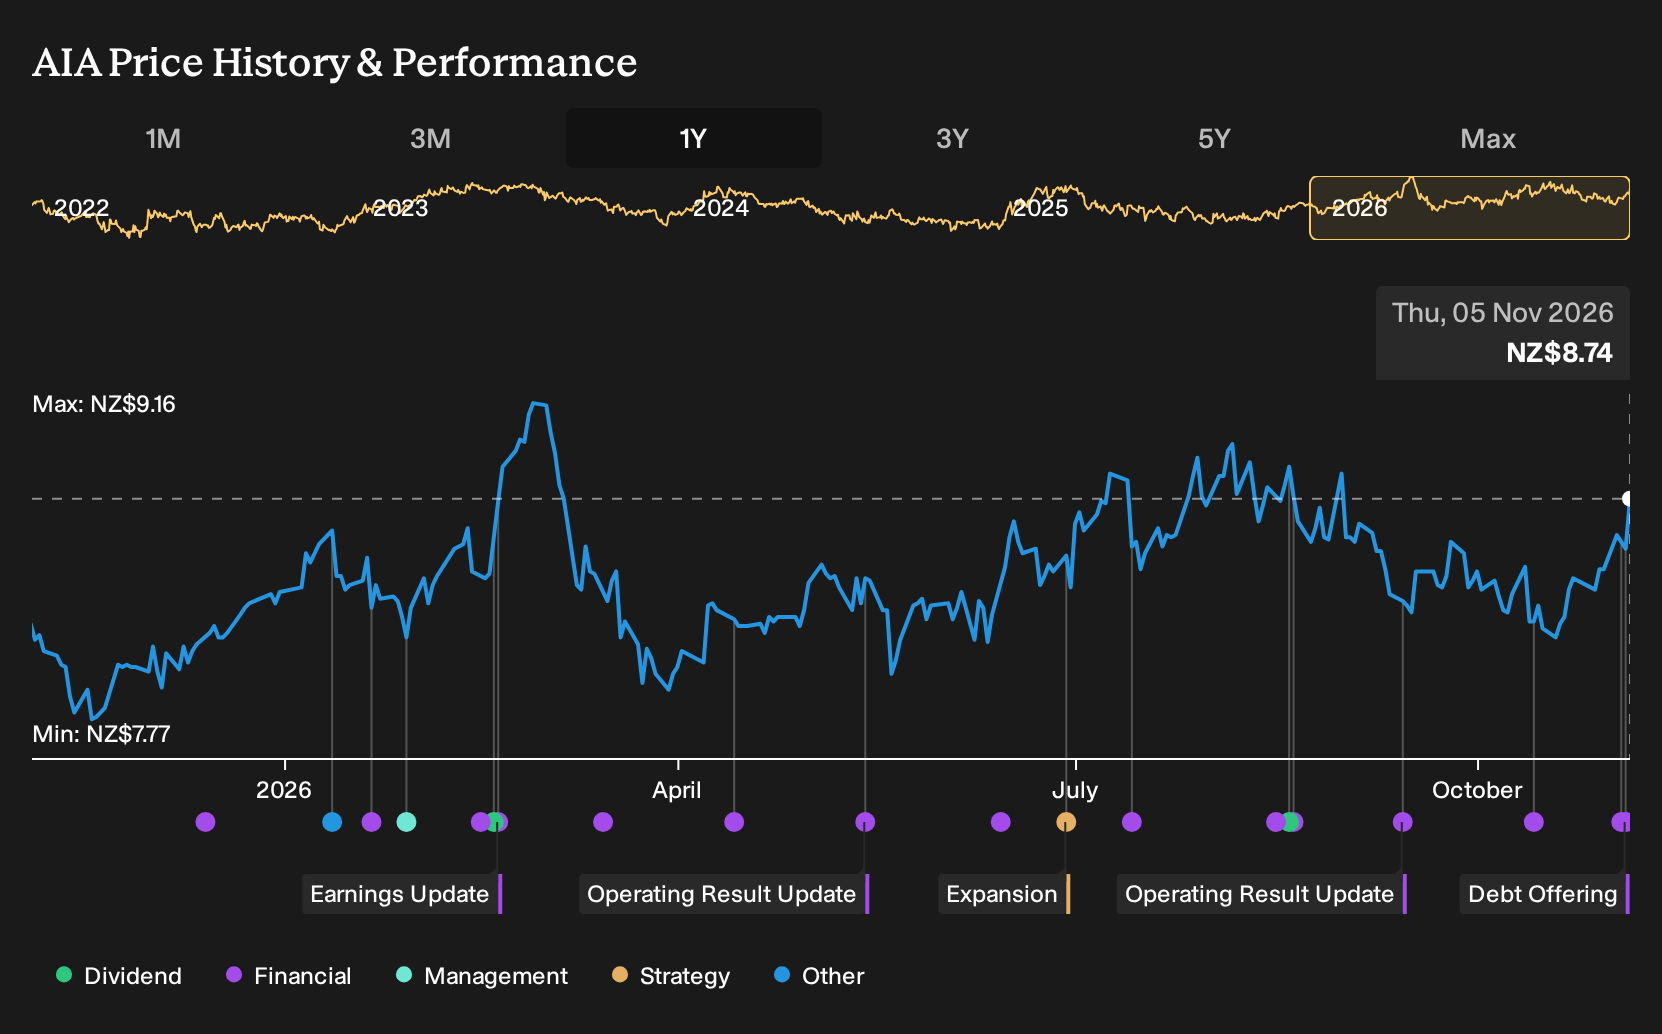
- Auckland International Airport has recently confirmed fixed and floating rate bond offers of up to NZ$350 million, including NZ$100 million of five year fixed rate retail bonds and NZ$100 million of callable floating rate notes maturing in 2031.
- The mix of unsecured, unsubordinated fixed and floating debt across retail, institutional and wholesale channels indicates a defined funding route for Auckland International Airport's multi year capex and balance sheet planning.
- We will now look at how Auckland International Airport's investment narrative is shaped by this multi tranche bond funding programme.
Scan how Auckland International Airport is handling its funding with fresh bond issues, then compare it with other issuers on our list of solid balance sheet and fundamentals (195 results) for potential balance sheet strength and discipline.
Auckland International Airport Investment Narrative Recap
A shareholder in Auckland International Airport needs to believe that high capex on terminals, parking and property can translate into steadier cash generation, even as current earnings carry the weight of higher depreciation. The recent multi tranche bond offers help clarify how those projects may be funded, but do not fundamentally change the near term story.
The key short term swing factor is still passenger volumes after the recent 4% dip in September traffic, and how that flows through aeronautical and retail revenue. The biggest risk remains pressure on margins, with retail income already down 4% in FY26 and depreciation charges stepping up as new assets come online.
The fresh NZ$100 million floating rate notes due November 2031 are the most relevant announcement here. This callable, unsecured, unsubordinated funding sits alongside the five year fixed rate retail bonds and gives Auckland International Airport more clarity on term debt as it progresses the terminal integration and broader infrastructure programme.
For you, the question is whether this funding mix supports execution on core catalysts such as increased international tourism capacity, maturing commercial property income and the car parking platform, without unduly constraining future returns. The higher reliance on external borrowing also means execution risk on capex and any sustained weakness in passenger numbers or retail margins deserves close attention.
Auckland International Airport Forecasts Behind The Funding Plan
Auckland International Airport's narrative projects NZ$1.4b revenue and NZ$403.0m earnings by 2029. This rests on analysts assuming 11.9% yearly revenue growth and an earnings increase of about NZ$68m from NZ$334.7m today.
Uncover why Auckland International Airport's fair value aligns with its current price.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span from NZ$8.65 to NZ$35.29 per share, which is a wide spread for Auckland International Airport. That tells you private investors are running very different scenarios on traffic, retail income and capex execution. Use that diversity to stress test your own view before acting.
Explore 2 other Auckland International Airport fair value estimates, including one that suggests it could be worth just NZ$8.65.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Auckland International Airport research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Auckland International Airport. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Auckland International Airport's overall financial health at a glance.
Looking For More Investment Ideas Beyond Auckland International Airport?
Once you have a view on Auckland International Airport, it helps to line it up against other potential opportunities so you can see where the risk, income and value profile really feels right for you. The Simply Wall St Screener lets you do that quickly by filtering shares based on balance sheet strength, income potential or valuation filters that match your approach.
- For investors who care most about financial resilience, compare Auckland International Airport's funding profile with a list of solid balance sheet and fundamentals (195 results) that already clear strict balance sheet and fundamentals filters.
- If you are hunting for value opportunities, stack your Auckland International Airport thesis against a 195 high quality undervalued stocks that combine quality fundamentals with potentially attractive pricing.
- Those who want income along with staying power can cross check Auckland International Airport against a 208 dividend fortresses that focus on higher yielding payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com