
Gibraltar Industries Stock In Focus After Return To Profit In Third Quarter
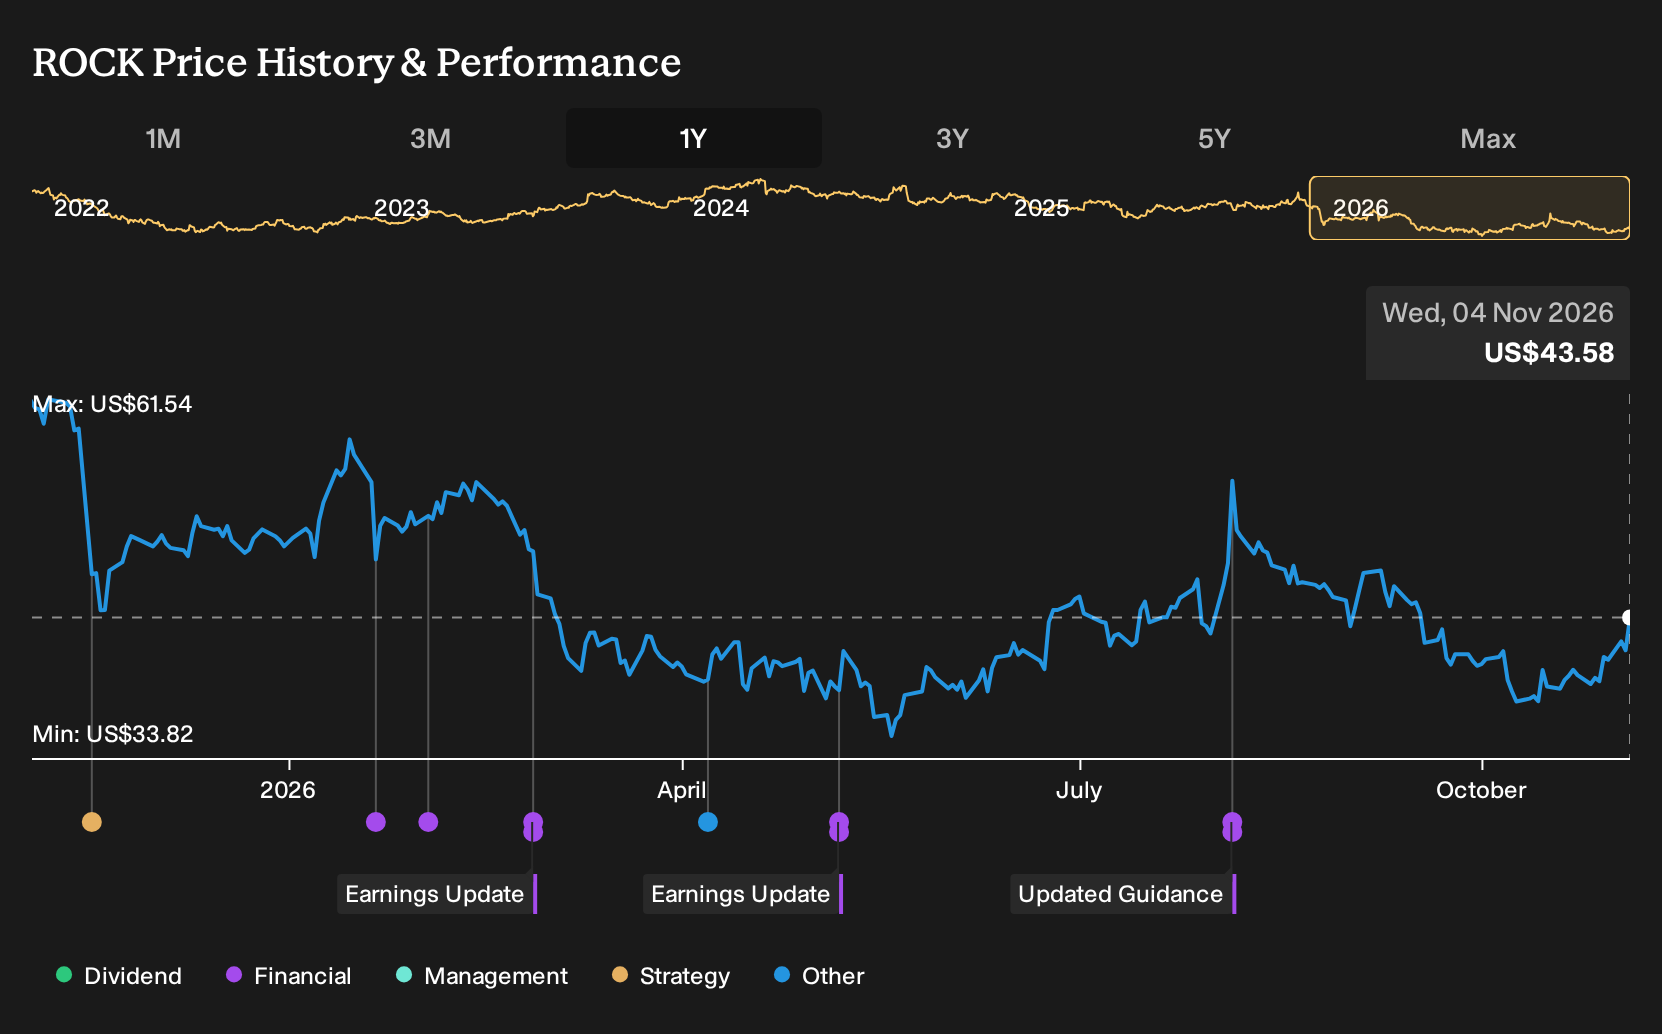
- Gibraltar Industries reported Q3 2026 results, with sales of US$479.57 million, net income of US$11.71 million and basic EPS of US$0.39.
- The combination of sharply higher sales and a shift from prior year loss to profit, alongside lower EPS from continuing operations, points to complex moving parts in Gibraltar Industries' business mix and cost structure.
- We will now look at how Gibraltar Industries' higher third quarter sales and return to profit could reshape its investment narrative.
See how Gibraltar Industries' surge in reported sales and return to profit compares with peers by running the 35 high quality undervalued stocks for potential breakout opportunities with stronger fundamentals.
Gibraltar Industries Investment Narrative Recap
To own Gibraltar Industries, you need to be comfortable with a simplified portfolio that leans heavily into Residential, Agtech, and Infrastructure, and with the OmniMax integration as a central swing factor. The Q3 return to profit and much higher sales show that the reshaped group can generate earnings, but the lower EPS from continuing operations keeps execution in sharp focus.
The key short term catalyst remains synergy capture and margin repair in Residential, especially with roofing demand described as soft and profit margins lower than last year. The biggest risk stays the same. Net debt around US$1.2b and debt not well covered by operating cash flow keep leverage reduction and cash discipline front and center.
The Q3 2026 earnings release is the announcement that matters most here because it updates how those catalysts and risks are playing out in real time. Sales of US$479.57 million and basic EPS of US$0.39 for the quarter, alongside a net income of US$11.71 million after a prior year loss, provide a clearer view of the reshaped portfolio.
At the same time, lower basic EPS from continuing operations versus last year and a nine month net loss of US$47.57 million highlight the pressure points that still need work. For a thesis built on OmniMax synergies, Residential share gains, and a plan to bring net leverage down toward 2.5x, this earnings release sits squarely in the middle of those execution questions rather than resolving them.
What The Current Analyst Narrative Implies For Gibraltar Industries
Gibraltar Industries' narrative projects US$2.2b revenue and US$223.4 million earnings by 2029. That profile assumes 15.7% yearly revenue growth and an earnings increase of about US$163.1 million from US$60.3 million today.
Uncover why Gibraltar Industries' fair value indicates a 73% potential upside to its current price before that discount begins to narrow.
Exploring Other Perspectives
Bullish analysts put debt reduction at the center of the Gibraltar Industries story. Before this earnings release, the most optimistic group was working off revenue near US$2.3b and earnings of about US$182.9 million by 2029, which supported a higher P/E and target price. You can now compare those pre news assumptions with the fresh results and decide which camp you lean toward.
Explore 2 other Gibraltar Industries fair value estimates, including one that suggests up to 256% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment results often come from independent thinking, so consider your own analysis and instincts.
- A great starting point for your Gibraltar Industries research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Gibraltar Industries. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Gibraltar Industries' overall financial health at a glance.
Looking For More Investment Ideas Beyond Gibraltar Industries?
If Gibraltar Industries has sharpened your thinking about balance sheets, earnings quality, and debt, it can be useful to line those insights up against other stocks as well. The Simply Wall St Screener lets you quickly filter for different return profiles and risk levels so you can build a watchlist that actually fits your approach.
- If you want potential mispriced opportunities with solid fundamentals, start by scanning a curated 35 high quality undervalued stocks that already clears basic quality and balance sheet checks.
- If durability matters more to you than excitement, focus on capital preservation using a 31 resilient stocks with low risk scores that filters for businesses with more resilient financial profiles.
- If you prefer steadier cash returns, target income-focused ideas by reviewing a 5 dividend fortresses that screens for higher yielding payouts supported by fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com