
Zymeworks (ZYME) Stock Seems Fully Priced On Its 336% Run
Zymeworks has seen its share price move sharply in recent years, and with fresh licensing money coming in from big pharma, the question now is how well that market value lines up with what its balance sheet actually shows. For anyone tracking this biotech, the real puzzle is whether the current price can be squared with the stock's book value relative to the wider industry.
- Over the past 3 years, Zymeworks has delivered a return of about 3.4x, which puts a lot of weight on whether the underlying equity on its books can support that kind of market enthusiasm.
- The recent Roche agreement for lung cancer candidate ZW209, with upfront, near term and potential milestone payments, may support higher expectations for future assets and cash on Zymeworks' balance sheet over time.
- Your read on Zymeworks is one view; the desks covering it have another. See what analysts think Zymeworks's shares could be worth.
The issue now is whether Zymeworks' current share price is adequately grounded in its book value when set against the industry average.
If you want more options with a similar focus on balance sheets and valuation anchors, a focused stock screen can be a useful next step. You can start with 35 high quality undervalued stocks.
Does Zymeworks Look Pricey on Book Value?
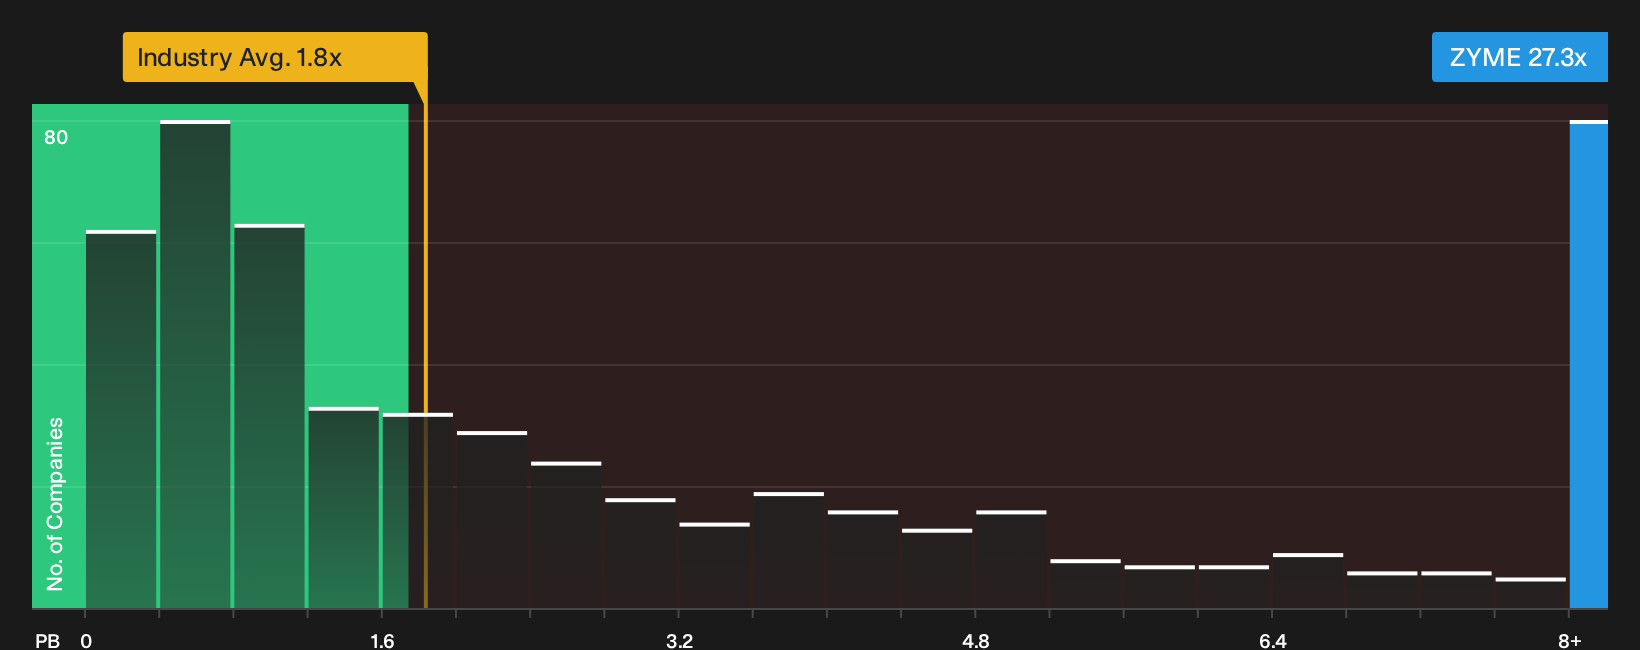
P/B matters for Zymeworks because the story today is still heavily about its intellectual property and cash rather than mature earnings power. The stock trades on a P/B of about 27.3x, using the latest figures, which is far above both the biotech industry average of roughly 1.8x and the peer group near 5.4x. That kind of gap means investors are paying a very high price for each dollar of recorded equity on the balance sheet.
Because the Roche deal around ZW209 has sharpened interest in the pipeline, the market seems willing to assign a rich premium to Zymeworks stock even though the accounting book value remains modest. Against the industry benchmark this P/B screens as overvalued rather than just punchy, and the size of the gap suggests the model is heavily penalising current losses and risk. As a result, the implied fair level is better treated as a warning flag than a precise target. For anyone weighing an entry or exit, the key question is whether the pipeline and licensing outlook justify paying so far above typical sector multiples. Explore the numbers behind Zymeworks's P/B valuation.
The Zymeworks Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Zymeworks valuation puzzle leaves off and explain what kind of future for growth, margins and earnings would need to occur for the shares to be worth meaningfully more or less than they are today, based on frameworks shared on the Community page. Rather than relying on a single multiple or model line, each narrative lays out the assumptions behind its view of fair value so you can track those inputs against actual results over time.
One of the top community narratives on Zymeworks: 25% undervalued
"The key requirement is that Zymeworks successfully converts its partnered pipeline and platforms into durable, high-margin royalty streams and cash flows..."
Discover why this Narrative puts Zymeworks at 25% undervalued.
One more angle on Zymeworks that could shift how you see the stock
Everything so far has focused on today's balance sheet and market multiples, but there is a separate set of analyst projections a few years out that gives you another lens to compare with the current share price. Explore where analysts expect Zymeworks to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com