
Did Deep Net Loss Just Shift Volkswagen's (XTRA:VOW3) Investment Narrative?
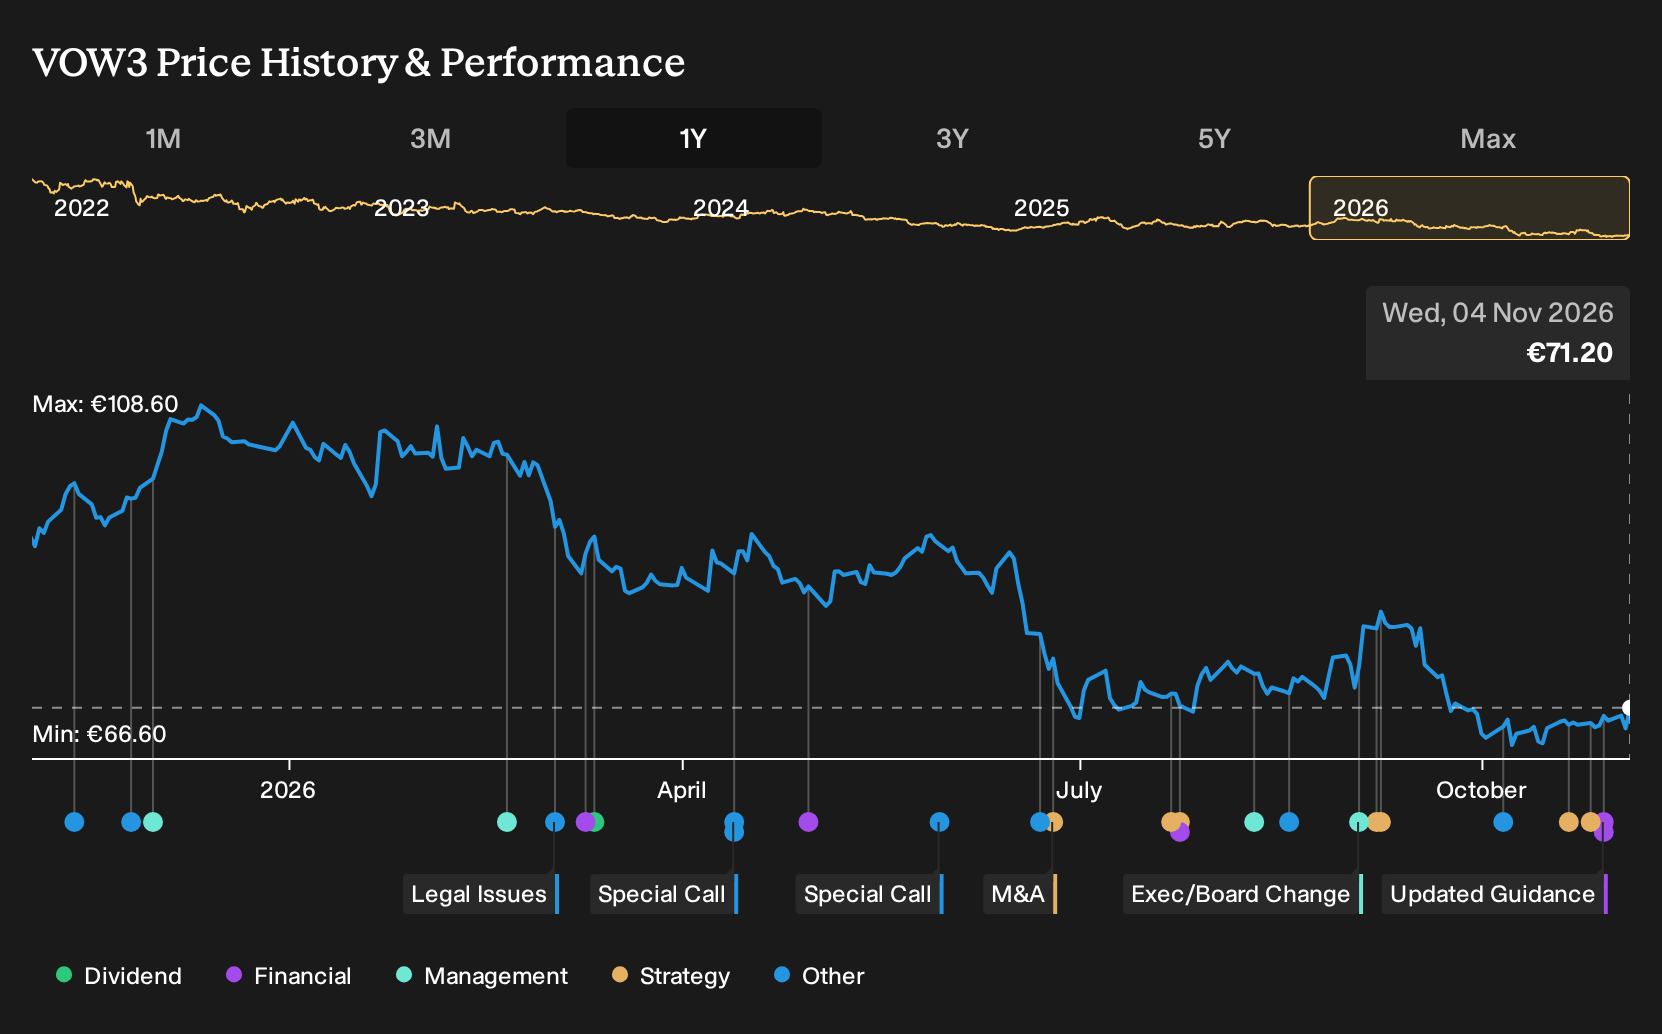
- Volkswagen reported third quarter 2026 sales of €75.3b and a net loss of €4.4b, with nine month figures also showing weaker sales and a loss compared with the prior year.
- The group now guides to around €315b of 2026 sales revenue and an operating margin of up to 1% after roughly €10b of special effects, which highlights pressure on underlying profitability.
- We will now look at how Volkswagen's deep net loss and subdued 2026 margin guidance reshape the broader investment narrative around the group.
Balance these weak Volkswagen figures against stronger stories in the same space by scanning our hand picked 218 resilient stocks with low risk scores, which aim to combine steadier fundamentals with tighter risk profiles.
Volkswagen Investment Narrative Recap
To own Volkswagen here, you need to believe the restructuring-heavy Future Plan 2030 can turn a low margin, capital intensive group into a simpler, higher return auto and services platform. The new 2026 outlook, with sales guided to around €315b and a reported operating margin capped at 1% after roughly €10b of special effects, keeps that execution question front and center.
The key near term swing factor is whether underlying profitability really tracks the roughly 4% margin Volkswagen flags before those special items. The biggest immediate risk is that impairments, China pressure or restructuring friction keep spilling into new charges, which would prolong weak reported earnings and keep confidence in the turnaround fragile.
Among recent moves, the partnership with NXP Semiconductors looks most relevant as you think about catalysts and execution risk. NXP’s S32K5 microcontrollers are slated as a core building block for Volkswagen’s future software defined vehicle architecture, with the first car on that system planned for 2027. This speaks directly to how the group wants to reduce complexity.
If Volkswagen can actually consolidate more vehicle functions into fewer electronic control units, it could support the longer term margin goals embedded in Group Target Picture 2030 by trimming hardware costs and simplifying platforms. The flip side for you as a shareholder is clear execution risk around timing, software integration and capital discipline, particularly while current reported margins and cash coverage of debt and dividends remain under pressure.
Analysts frame the Volkswagen story around revenues of €342.7b and earnings of €12.6b by 2029, based on 2.1% yearly revenue growth and an earnings increase of about €7.4b from current earnings of €5.2b.
Uncover why Volkswagen's fair value indicates a 43% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard into Volkswagen’s overhead cuts as a catalyst. Bullish analysts were pencilling in revenues of about €350.8b and earnings near €20.4b by 2029, before this guidance shock. That is a far more optimistic story than the baseline, and it may now be stress tested. Use it as a prompt to compare several viewpoints yourself.
Explore 6 other Volkswagen fair value estimates, including one that suggests as much as 803% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Volkswagen research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Volkswagen. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Volkswagen's overall financial health at a glance.
Looking For More Ideas Beyond Volkswagen?
If this Volkswagen update has you rethinking your watchlist, it can help to widen the lens and compare it with other businesses that have very different risk and return profiles. The Simply Wall St Screener lets you filter for the mix of quality, value and balance sheet strength that actually fits your style instead of relying on headlines alone.
- For investors who want potential mispricing with fewer quality compromises, scan a curated set of 588 high quality undiscovered gems that pair solid fundamentals with relatively low market attention.
- If capital preservation and resilience matter most to you, focus on companies screened for sturdier finances and consistent metrics through our list of solid balance sheet and fundamentals (195 results).
- Income seekers who care about reliability can zero in on cash return potential by sorting through 208 dividend fortresses that combine higher yields with an emphasis on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com