
Is PROCEPT BioRobotics (PRCT) Undervalued As Higher Sales And Wider Losses Reset Expectations?
PROCEPT BioRobotics (PRCT) just released third quarter and nine month 2026 results, reporting higher sales but a wider net loss, giving investors fresh numbers to reassess the stock.
The earnings release appears to have reset expectations in the short term. A 1-day share price return of 7.39% and a 30-day share price return of 21.55% suggest momentum has picked up after a tough stretch, during which the year-to-date share price return is down 29.58% and the 1-year total shareholder return has fallen 31.48%.
Scan how PROCEPT BioRobotics fits into the broader robotics theme by lining it up against 92 robotics and automation stocks that are also seeing strong interest around automation and surgical technology.
After a sharp bounce in PROCEPT BioRobotics following results that combined stronger sales with heavier losses, the key question now is clear: Does the current valuation still offer more potential upside than risk for new buyers?
Most Popular Narrative: 64% Undervalued
Compared with the last close at $21.66, the most widely followed valuation story on PROCEPT BioRobotics points to a fair value of $60. That gap frames a very different picture to the current market capitalisation of about $1.2b.
I have been an investor in PRCT since before IPO. The wild fluctuations in share price recently make no sense. The sell side analyst who chased the share price up to highs in 2024 (when the price was way too frothy) are doing the same thing now by revising the share price lower and lower, when clearly the company is still doing a great job. The recent downgrade by Leerink, citing PAE as a possible headwind for PRCT growth, is in direct opposition to what Larry Wood (CEO) stated at the last earnings call. To quote Larry Wood, “I don’t think PAE is a headwind for us at all. I think PAE is a big red herring. It’s a procedure that really does not get performed in any volume in Europe. And the reason it doesn’t get performed is because it doesn’t get paid for because it’s not a very good procedure.” So if you believe Larry Wood, then the company has been grossly oversold and looks very very cheap down here. If PRCT hit the Q2 numbers watch all the sheep suddenly revise their target prices back up again. I think fair value is still up at $47. PRCT had a reassessment of how to report handpiece sales versus procedures and therefore there was a shortfall on revenue. Clearly they could have stuck with the old model and revenue would have been better. Larry is doing a great job of making reporting a direct reflection of procedures being done. If the numbers are delivered, watch this thing fly.
See why 6 investors see PROCEPT BioRobotics as 64% undervalued.
The narrative, according to Betsareoff, applies a discount rate of 7.56% to future cash flows, which is relatively restrained for a loss-making medical equipment stock. That approach, paired with an assumed profit margin of about 12.94% and a future P/E of 24.66, goes a long way toward explaining how a fair value of $60 can emerge against a current loss of $109.76m on $337.34m in annual revenue.
There is a clear gap between this storyline and other reference points that readers may track. The same data set shows PROCEPT BioRobotics trading only about 2.7% below an analyst price target of $22.25, and our DCF model currently suggests the share price is above an estimate of $19.88, even though the narrative still concludes the stock is undervalued on its own assumptions.
For anyone weighing these signals, the tension sits between strong revenue growth forecasts of 16.21% per year and a business that is not expected to reach profitability over the next three years. That mix helps explain why the narrative leans on a long runway of growth and eventual margins, while the DCF check and current losses keep near term expectations more restrained.
Result: Fair Value of $60 (UNDERVALUED)
Still, PROCEPT BioRobotics relies on ongoing acceptance of Aquablation procedures and HYDROS system uptake, while continued net losses could pressure sentiment if cash needs rise.
Find out about the key risks to this PROCEPT BioRobotics narrative.
Another View: PROCEPT BioRobotics Looks Expensive On Sales
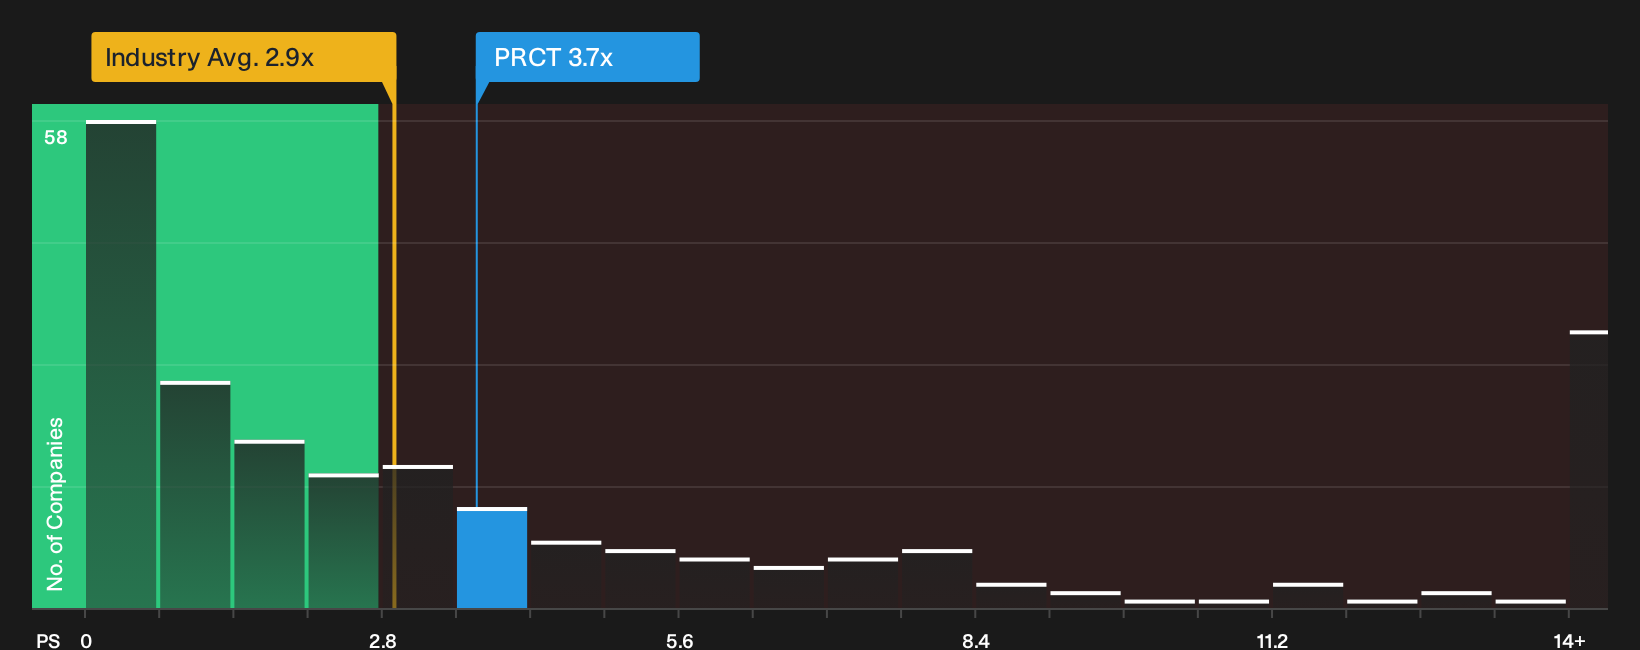
The big narrative pegs PROCEPT BioRobotics as materially undervalued; however, the current P/S of 3.7x tells a tougher story. That level sits above the US Medical Equipment industry at 2.8x, the peer average at 3.6x, and a fair ratio of 3x that the multiple could drift toward if sentiment cools.
For investors, that mismatch suggests less margin for error. If revenue growth or profitability timing disappoints, the share price may have to do more work to justify a richer sales multiple, which raises the question of how much patience the market will show from here.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of bullish and cautious views on PROCEPT BioRobotics feels finely balanced, consider acting promptly, reviewing the numbers yourself, and weighing both sides of the story with the 1 key reward and 1 important warning sign.
Looking For More Investment Ideas Beyond PROCEPT BioRobotics?
If PROCEPT BioRobotics has you rethinking where the best risk rewards might sit, do not stop with a single ticker. Cast the net wider using focused stock shortlists built from objective data.
- Target potential mispricings by scanning a curated pool of high quality companies that look cheap on fundamentals through the 35 high quality undervalued stocks.
- Strengthen capital preservation by focusing on financially resilient businesses using the list of solid balance sheet and fundamentals (24 results).
- Get in early on potential future leaders by reviewing a hand picked set of lesser known stocks through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com