
Where Does Rush Street Interactive (RSI) Valuation Stand After Q3 Earnings And Reaffirmed Guidance?
Rush Street Interactive (RSI) put fresh numbers on the table with its Q3 2026 earnings release, reporting revenue of US$385.9 million and net income of US$11.8 million, and reaffirming full year revenue guidance.
Despite reaffirmed guidance and Q3 growth, sentiment around Rush Street Interactive has cooled. The share price is down 41% over the past month and 51% over three months, even though the three year total shareholder return sits well above 100%.
Scan how Rush Street Interactive compares with other consumer services stocks under heavy selling pressure and improving fundamentals by reviewing the hand picked 35 high quality undervalued stocks in this space.
Rush Street Interactive shares have dropped sharply while analyst estimates and fair value models remain much higher. The gap between the US$12.35 price and those valuation ranges is where the real story starts.
Most Popular Narrative: 47% Undervalued
The most followed valuation story around Rush Street Interactive pegs fair value at about $23.21, compared with the latest close at $12.35. That gap rests on a view that the business can compound its online casino and sports betting footprint while absorbing higher tax and regulatory friction.
The digitalization of entertainment is accelerating migration from offline to online gaming, and with record-high monthly active users (MAUs) growing over 30% in North America and 40%+ in Latin America, Rush Street Interactive is well-positioned to capture this expanding addressable market, supporting sustained future revenue growth.
Ongoing legalization and regulatory acceptance of online sports betting and iGaming in North America and Latin America, evidenced by strong launches and growth in new markets like Delaware, Alberta (pending), and Mexico, provides a clear pathway for robust revenue expansion and geographic diversification in future periods.
See why 22 investors see Rush Street Interactive as 47% undervalued.
Result: Fair Value of $23.21 (UNDERVALUED)
Still, two pressure points could derail that Rush Street Interactive story: Colombia tax changes and slower North American user momentum if competition keeps intensifying.
Find out about the key risks to this Rush Street Interactive narrative.
Another View: Rush Street Interactive Through The P/E Lens
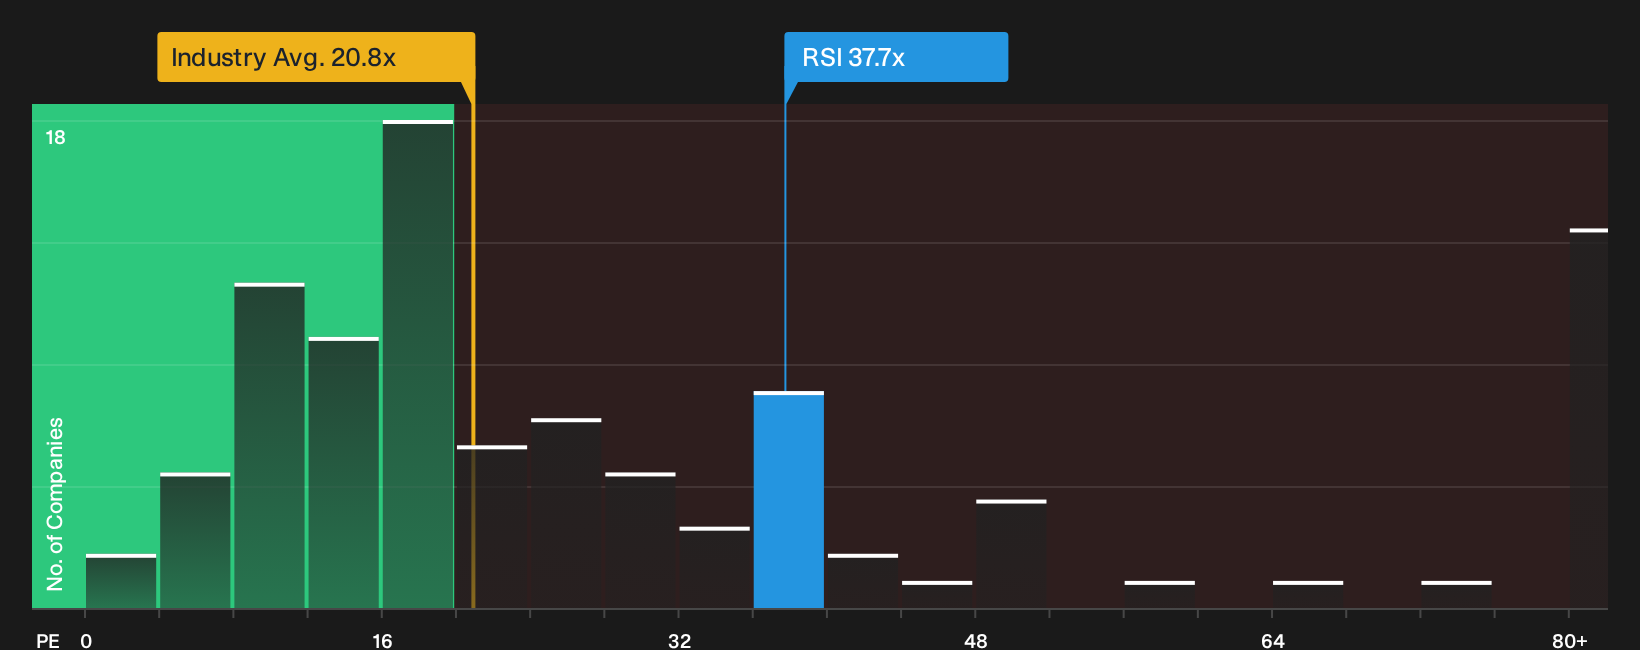
There is a very different story when Rush Street Interactive is viewed through its P/E ratio. The stock trades at 37.7x earnings, above both the US Hospitality industry at 20.4x and its own fair ratio of 33.5x. That premium suggests investors are already paying up, so how much margin of safety is really left?
To unpack what this price gap might mean for risk and opportunity, it helps to see how the current multiple compares to the underlying earnings profile in more detail, which you can do through the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Feeling that this Rush Street Interactive story is skewed either too positive or too pessimistic? Act quickly, review the underlying drivers yourself, and then weigh them against the 3 key rewards.
Looking for more Rush Street Interactive style ideas?
If the Rush Street Interactive setup has you thinking about what else the market might be mispricing, do not stop here. Target a few focused screens and you might find opportunities that others overlook.
- Hunt for quality at a discount by checking the 35 high quality undervalued stocks that blend solid business profiles with prices that lag underlying fundamentals.
- Prioritize staying power over excitement and scan the 31 resilient stocks with low risk scores where balance sheets and risk scores aim to keep drawdowns in check.
- Spot tomorrow's potential leaders early by reviewing the 19 high quality undiscovered gems before they sit on everyone else's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com