
Independence Realty Trust (IRT) Shares Climbed, What Is Driving Fresh Attention?
Why Independence Realty Trust is back in focus
Independence Realty Trust (IRT) returned to investors’ radar after reporting third quarter 2026 earnings and trimming full year profit guidance, which has put fresh attention on how the apartment REIT is balancing growth and expectations.
Recent gains have started to rebuild some momentum around Independence Realty Trust, with a 1-day share price return of 4.32% and a 7-day move of 6.92% after its earnings release and merger updates. However, the 90-day share price return is down 9.01%, and the 1-year total shareholder return is slightly negative at 0.71%.
Compare how Independence Realty Trust stacks up against a hand picked group of resilient real estate and income focused stocks using our 31 resilient stocks with low risk scores for potential steadier return profiles.
Bulls point to Independence Realty Trust’s earnings beat, merger scale and improving leasing metrics. Bears focus on trimmed profit guidance and a share price still down year to date. Which side does the current valuation favour in the period ahead?
Most Popular Narrative: 19% Undervalued
Against a last close of $15.45, the most followed narrative for Independence Realty Trust points to a fair value of $19.14, which implies a sizeable gap that analysts link to how the REIT’s markets, balance sheet actions and rent drivers interact over time.
The tapering of new multifamily supply and a 43% year-over-year reduction in deliveries projected for IRT's Sun Belt-focused markets in 2026 positions the company for a reacceleration of rent growth and stronger occupancy as demand continues to outpace incoming inventory, which should drive future revenue and NOI growth.
See why 0 investors see Independence Realty Trust as 19% undervalued.
Result: Fair Value of $19.14 (UNDERVALUED)
Still, the narrative can crack if Sun Belt oversupply keeps pressuring rents or if asset sales, which are used to fund portfolio shifts, deliver weaker than expected returns.
Find out about the key risks to this Independence Realty Trust narrative.
Another View on Independence Realty Trust’s Valuation
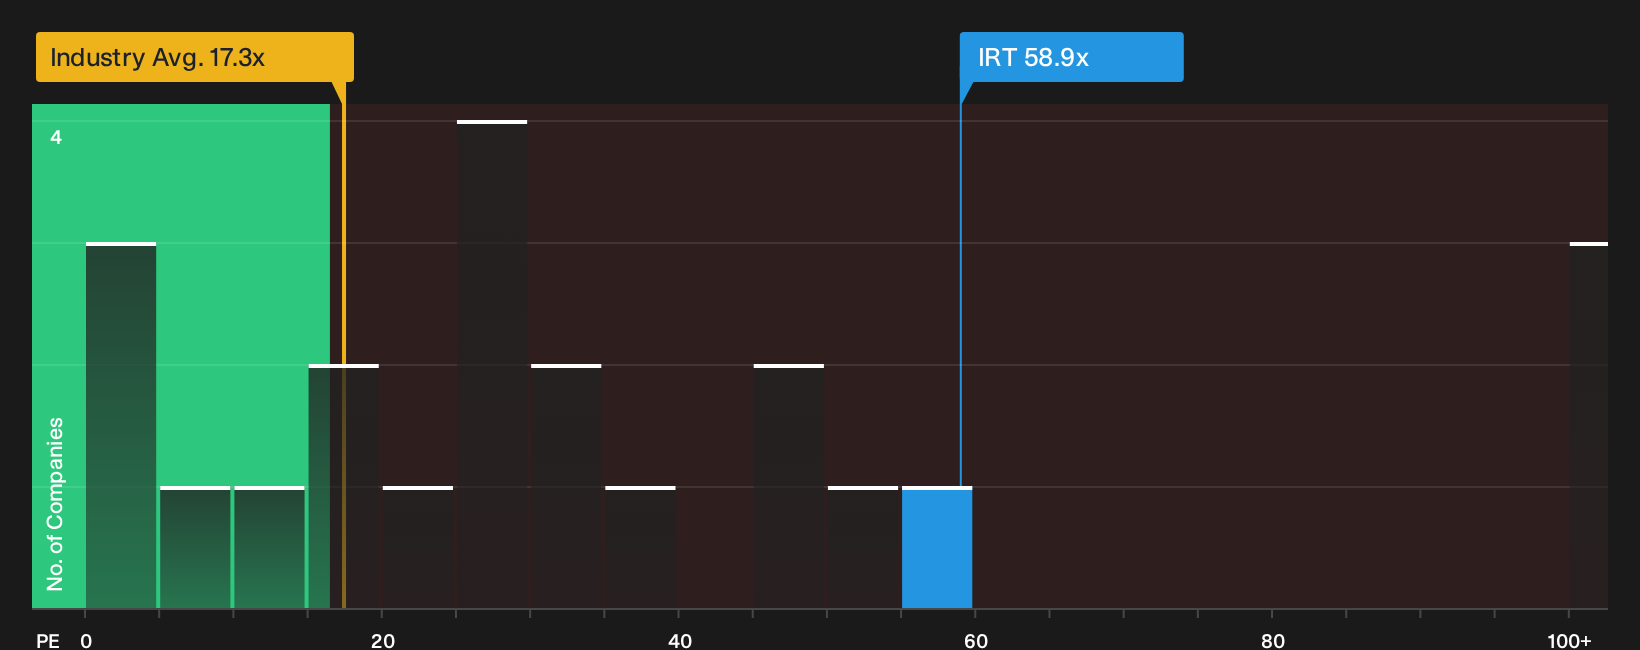
The fair value story for Independence Realty Trust looks very different once the focus shifts to earnings multiples. On a P/E of 58.9x versus a fair ratio of 27.1x, the stock trades at more than double the level the regression model suggests the market could move toward over time.
That premium also stretches beyond the Global Residential REITs average of 16.4x and the peer group on 24.5x. This points to meaningful valuation risk if sentiment cools or earnings slip. The key question for investors is what would need to go right for this rich multiple to hold.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Plenty of signals around Independence Realty Trust point in different directions, so use this as a prompt to move quickly and test the numbers yourself. To weigh up both the concerns and the potential upside in one place, start with the 2 key rewards and 4 important warning signs.
Looking for more investment ideas beyond Independence Realty Trust?
If Independence Realty Trust has sharpened your focus on valuation, do not stop here, because missing other opportunities could mean leaving potential returns on the table.
- Target resilient balance sheets and steady fundamentals through a curated list of solid balance sheet and fundamentals (24 results) that can help you stress test quality beyond headline metrics.
- Hunt for quality at a discount by scanning the 35 high quality undervalued stocks that filters for stocks combining strong fundamentals with prices that lag underlying business strength.
- Build a cash flow focused watchlist using the 5 dividend fortresses that highlights companies pairing higher yields with an emphasis on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com