
3 Consumer Bank Stocks Facing New Washington Pressure
When Washington suddenly turns up the heat on Wall Street, large consumer banks move from background noise to front-page story. A Congress controlled by Democrats, fresh talk of tougher rules on fees and lending, and the prospect of bank CEOs facing the cameras all create a live test for U.S. Large Banks with Significant Consumer-Facing Businesses. This article explains what that shift could mean and highlights three stocks most exposed to this political jolt, each positioned in a different way.
The three stocks in focus are just a sample of what this political turn could mean for U.S. Large Banks with Significant Consumer-Facing Businesses, and the full screen surfaced 9 more companies with equally compelling stories that will not all fit into one article. To see the broader field and identify which large consumer banks best match your own risk and policy views, head straight into the U.S. Large Banks with Significant Consumer-Facing Businesses screener.
Hancock Whitney (HWC)
Hancock Whitney fits this screen as a regional lender that operates close to households and small businesses, where policy on fees, overdrafts and consumer credit can quickly show up in day-to-day results, and where management is actively trying to tilt the story toward expansion.
"Hancock Whitney plans to continue its program of hiring revenue producing bankers, with 42 net new hires already in place by the first half of 2026 toward a goal of 50 additions for the year."
What happens to that hiring push if one unseen pressure on profitability or efficiency shifts more sharply than management expects?
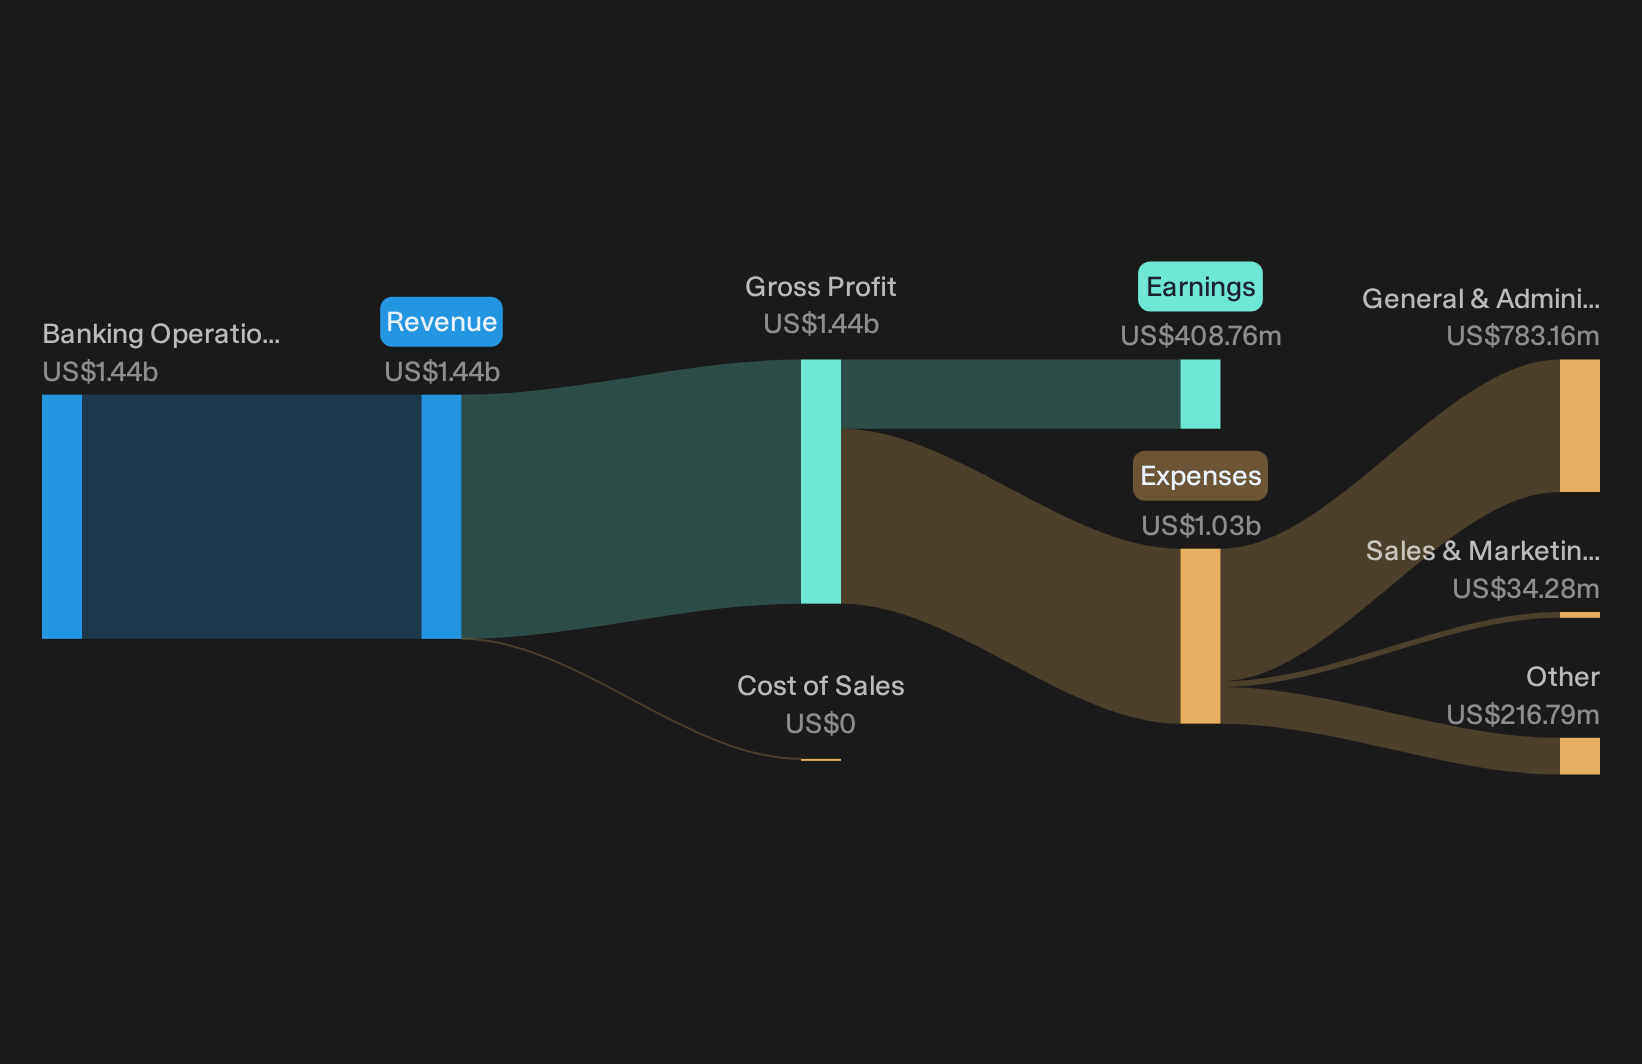
Hancock Whitney is a regional financial holding company focused on traditional and online banking for retail, small business and commercial clients across the United States, generating about US$1.4b from banking operations and carrying a market value near US$5.8b.
That pressure point sits at the center of Hancock Whitney’s story, and the full narrative for Hancock Whitney shows how fee rules, hiring plans and capital allocation could be quietly decoupling.
Glacier Bancorp (GBCI)
Glacier Bancorp is another clear fit for this consumer banking screen, with a footprint built around everyday deposits, mortgages and loans that tie its fortunes closely to household finances and any policy shift that touches them.
Glacier Bancorp is a U.S. bank holding company that runs a full service retail and commercial banking franchise for individuals, small businesses and local institutions, with a market value of about US$6.4b.
"Continued repricing of Glacier Bancorp’s loan and securities books, combined with the removal of $440 million of higher cost Federal Home Loan Bank advances and lower total funding costs that moved from 1.52% in Q4 2025 to 1.33% in Q2 2026, is expected to keep widening net interest margin and support future earnings."
What really matters from here is how one quiet shift in the balance between funding costs and loan yields ultimately steers that margin story.
That margin question is exactly where the full narrative for Glacier Bancorp shows whether Glacier Bancorp’s repricing story is quietly accelerating, or if funding shifts are masking new risks.

American Express (AXP)
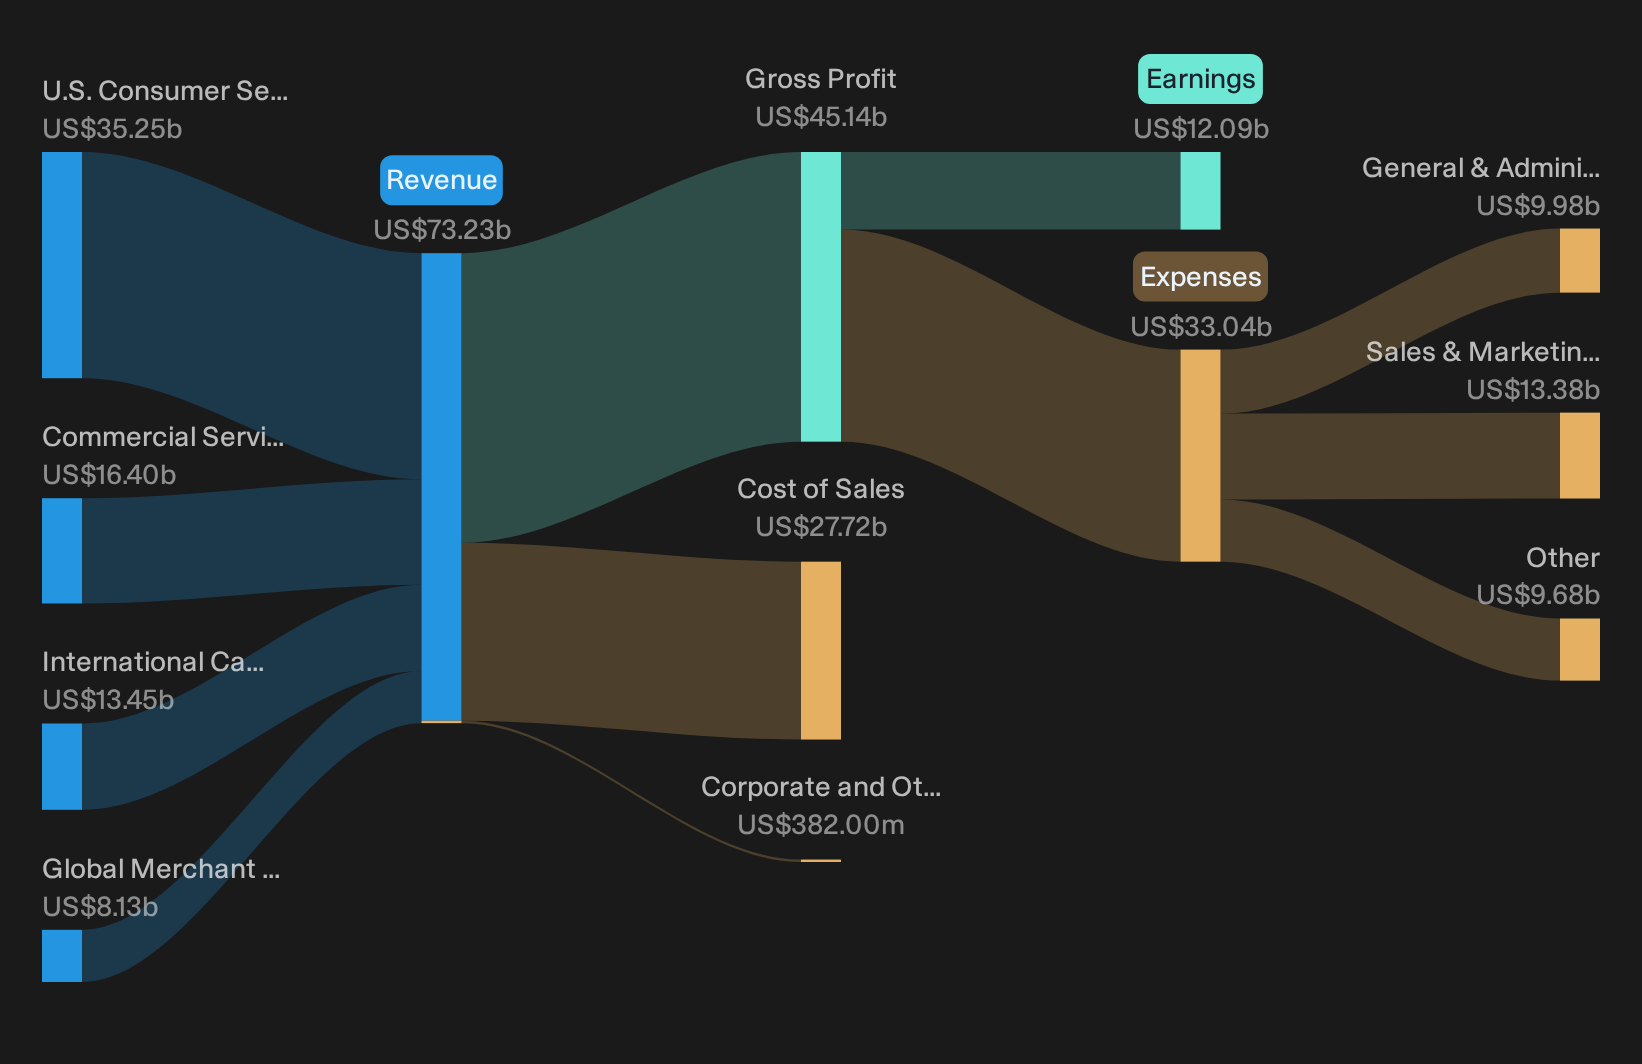
American Express is the purest consumer-facing story in this screen, with credit cards, lending and payments all tied directly to household spending and any rules that touch how those products are priced or policed.
"American Express disclosed in its second-quarter filing that it expects to face an enforcement action concerning its anti-money-laundering compliance programs. Civil penalties may follow."
What really matters now is how one unresolved outcome around that issue feeds back into the economics of its premium card and payments model.
That feedback loop is exactly where the full narrative for American Express shows whether American Express is quietly accelerating its premium model or letting compliance risks stall future momentum.
Seeking Alternatives Before The Crowd
Markets move fast. Fresh opportunities can gain breakout momentum while you watch from the sidelines. Consider these curated ideas while they are still under the radar for now and get in early.
- Spot cash rich businesses that are not flying yet by scanning the list of solid balance sheet and fundamentals (24 results) before others catch the same balance sheet strength story.
- Hunt for early momentum in companies quietly building real AI profits with the 40 profitable AI stocks that aren't just burning cash while expectations are still catching up.
- Position ahead of a potential build out in critical infrastructure by checking the 41 power grid technology and infrastructure stocks while valuations still reflect yesterday’s grid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com