
Carter's (CRI) Stock Looks About Right As Shares Sit 62% Lower
Carter's has delivered mixed share-price results over the past few years, and the question now is whether the current valuation really lines up with what its earnings justify. With the stock trying to find its footing after a long slide, the key issue for you is how much of the recent corporate reshuffle and profit focus is already reflected in the price.
- Carter's stock has fallen 61.8% over 5 years, which puts the spotlight on whether the current earnings profile can support even this lower level.
- The refreshed leadership structure that tightens links between product, commercial decisions and operations may support more consistent profitability, which matters directly for how you think about the earnings multiple.
- Your read on Carter's is one view; the desks covering it have another. See what analysts think Carter's's shares could be worth.
The issue now is whether the earnings power of Carter's really backs up where the stock trades today.
If you are weighing whether Carter's current P/E feels fair after a 61.8% share price decline over 5 years, it can help to compare that decision with 35 high quality undervalued stocks.
Is Carter's Fairly Priced on Earnings?
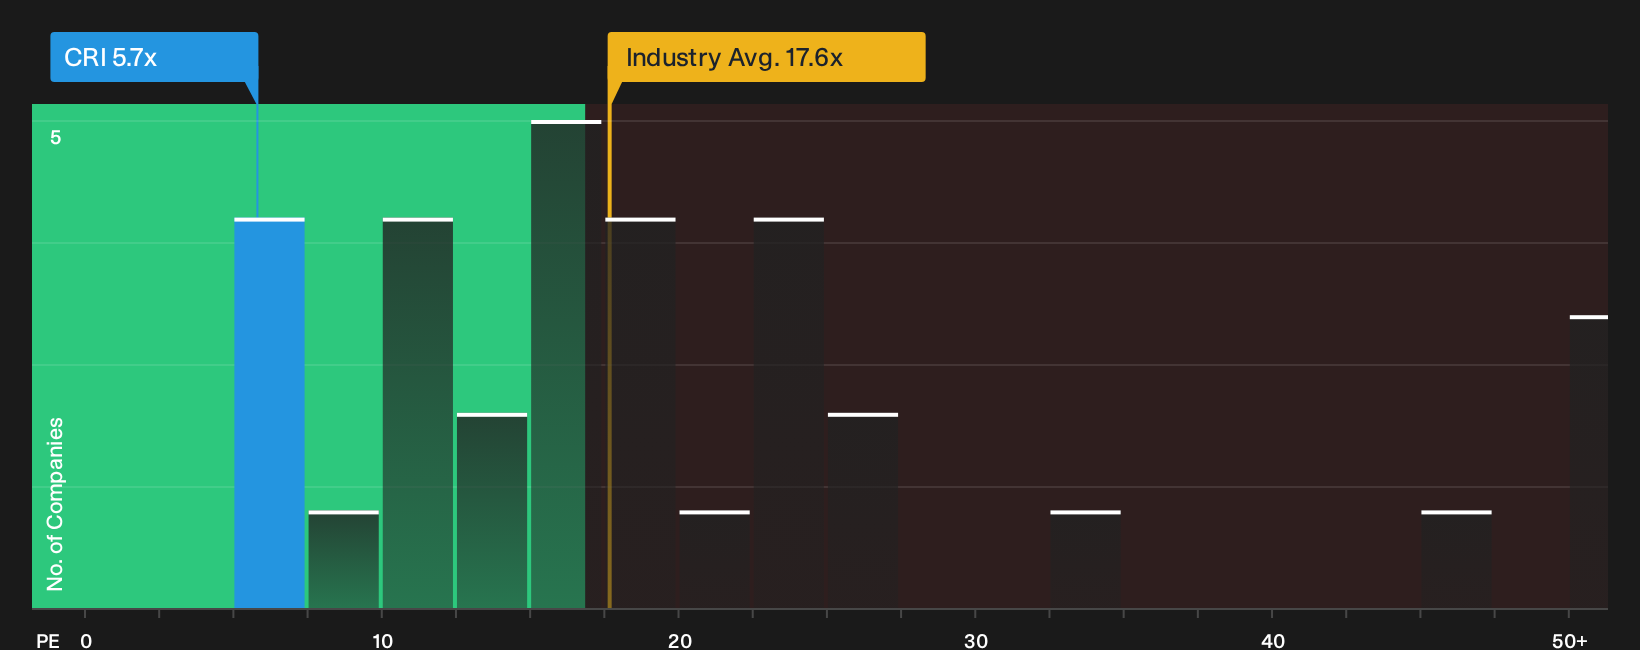
A P/E lens fits Carter's because investors usually anchor children’s clothing brands to their earnings power. On that score, the stock trades on a P/E of 5.7x, which is well below both the peer group on 14.4x and the wider luxury industry on 17.6x. The bespoke fair P/E from the model sits close to the current level, so the multiple lines up broadly with what you would expect once Carter's size, margins and risk profile are taken into account.
Because management recently reshaped the leadership team and is talking more about profit focus after mixed Q3 results, the gap to sector valuations hints that the market still prices Carter's with a fair amount of caution despite the low headline multiple. If you are weighing whether that caution is warranted, the key question is how confident you feel that the current earnings base, and the reshuffle around it, can be sustained over time. Explore the numbers behind Carter's's P/E valuation.
The Carter's Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Carter's P/E puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the stock to be worth materially more or materially less than today’s price. Each scenario ties a fair value to a clear story about potential catalysts and setbacks so you can track over time which version of events is actually playing out on the Community page.
Community views on Carter's are split between those who see upside from brand and digital work and those who think tariff and wholesale risks already cap the story.
Bull case: 12% undervalued
"Expanding consumer centric branding at Carter's, including higher marketing spend in 2026, collaborations such as Disney and Umbro, and campaigns like Watch Them Glow and Dadfirmations aimed at Gen Z and higher income parents, is expected to support higher average unit retail and potentially more resilient revenue growth..."
Discover why this Narrative puts Carter's at 12% undervalued.
Bear case: 12% overvalued
"While e-commerce comps are growing at a double digit rate with AI tools supporting profitable online operations, Carter's trimmed full-year 2026 net sales guidance and expects Q3 2026 sales to be flat year over year..."
Explore why this Narrative puts Carter's at 12% overvalued.
One more Carter's question before you make a move
There is one piece still missing from the Carter's picture, which is how professional analysts currently map out its earnings profile over the next few years compared with where the shares trade today. Explore where analysts expect Carter's to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com