
IMAX (NYSE:IMAX) reports upbeat Q3 2026
Premium cinema technology company IMAX (NYSE:IMAX) reported Q3 2026 results exceeding the market’s revenue expectations, with revenue up 63.7% year on year to $174.6 million. Its non-GAAP profit of $2.21 per share was significantly above analysts’ consensus estimates.
For more on IMAX, read our free full research report.
IMAX (IMAX) Q3 2026 highlights:
- Revenue $174.6 million vs S&P analysts’ consensus estimates of $163.3 million (63.7% year-on-year growth, 6.9% beat)
- Adjusted EPS $2.21 vs S&P analysts’ consensus estimates of $1.02 (significant beat)
- Adjusted EBITDA $187.7 million vs analysts’ consensus estimates of $93.24 million (108% margin, significant beat)
- Operating margin 42.9%, up from 27.2% in the same quarter last year
- Free cash flow margin 48.2%, down from 51.4% in the same quarter last year
- Market capitalization $2.84 billion
“What IMAX achieved goes beyond simply a ‘great quarter’ and transcends the many records we shattered in the period. What we believe we are witnessing is an awakening to the power and potential of our platform to impact global culture, unlock new commercial opportunities, and inspire a new level of demand and awe in audiences around the world,” said Rich Gelfond, CEO of IMAX Corporation.
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can have short-term success, but a top-tier one grows for years.
With $484 million in revenue over the past 12 months, IMAX is a small player in the business services space, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and numerous distribution channels. On the positive side, it can grow faster because it has more room to expand.
IMAX grew its revenue at a strong 19.1% compounded annual growth rate over the last five years, showing demand was higher than at many business services companies.
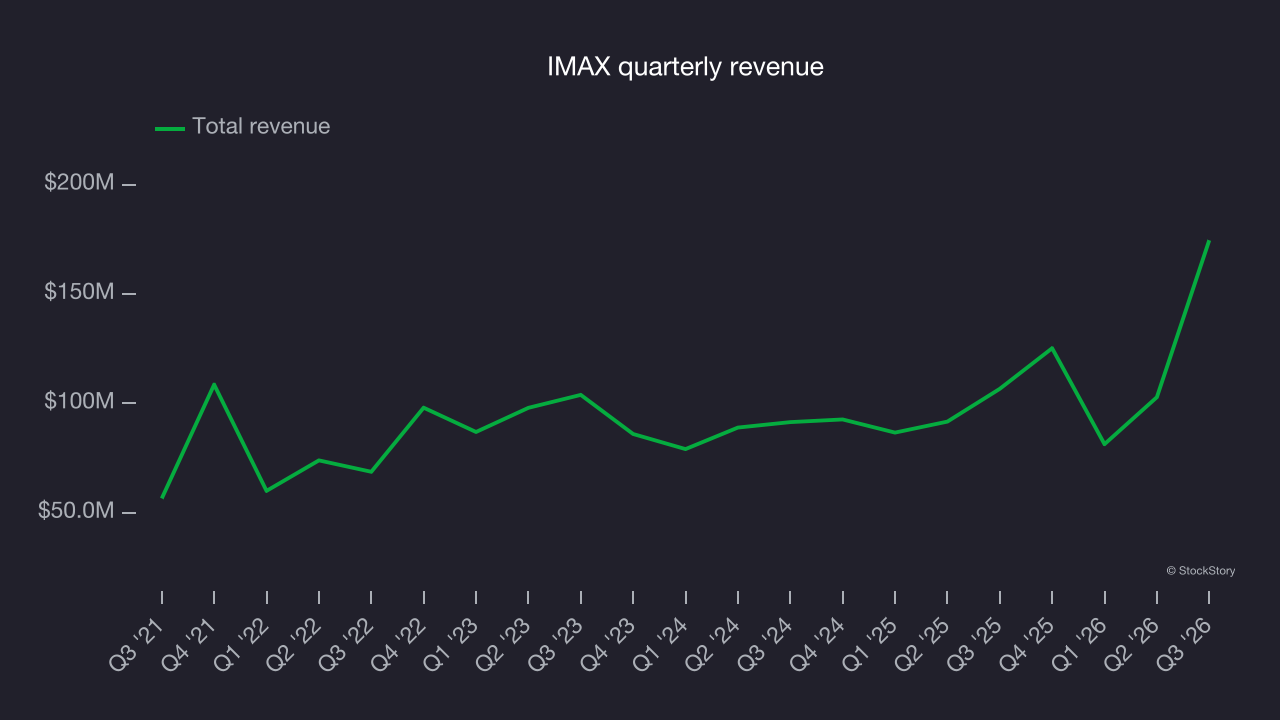
Long-term growth matters most, but within business services, a half-decade historical view may miss recent innovations or disruptive industry trends. IMAX’s annualized revenue growth of 18.3% over the last two years aligns with its five-year trend, suggesting its demand was predictably strong. 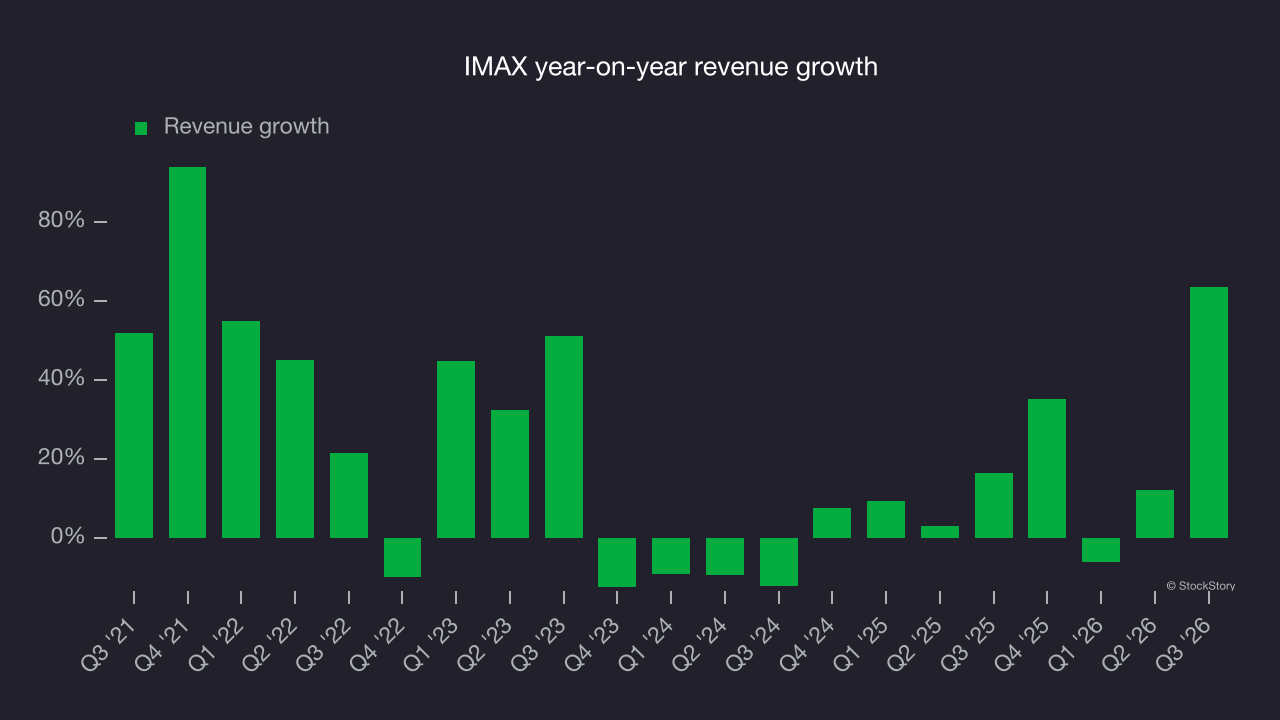
This quarter, IMAX reported year-on-year revenue growth of 63.7%, and its $174.6 million in revenue beat Wall Street’s consensus estimates by 6.9%.
Looking ahead, sell-side analysts expect revenue to decline by 3% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and suggests its products and services will see some demand headwinds. Still, the company is tracking well in other measures of financial health.
Adjusted operating margin
IMAX has been an efficient company over the last five years. It was one of the more profitable businesses in the business services sector, with an average adjusted operating margin of 16.5%.
Looking at the trend in its profitability, IMAX’s adjusted operating margin rose by 24.6 percentage points over the last five years, as its revenue growth provided substantial operating leverage.
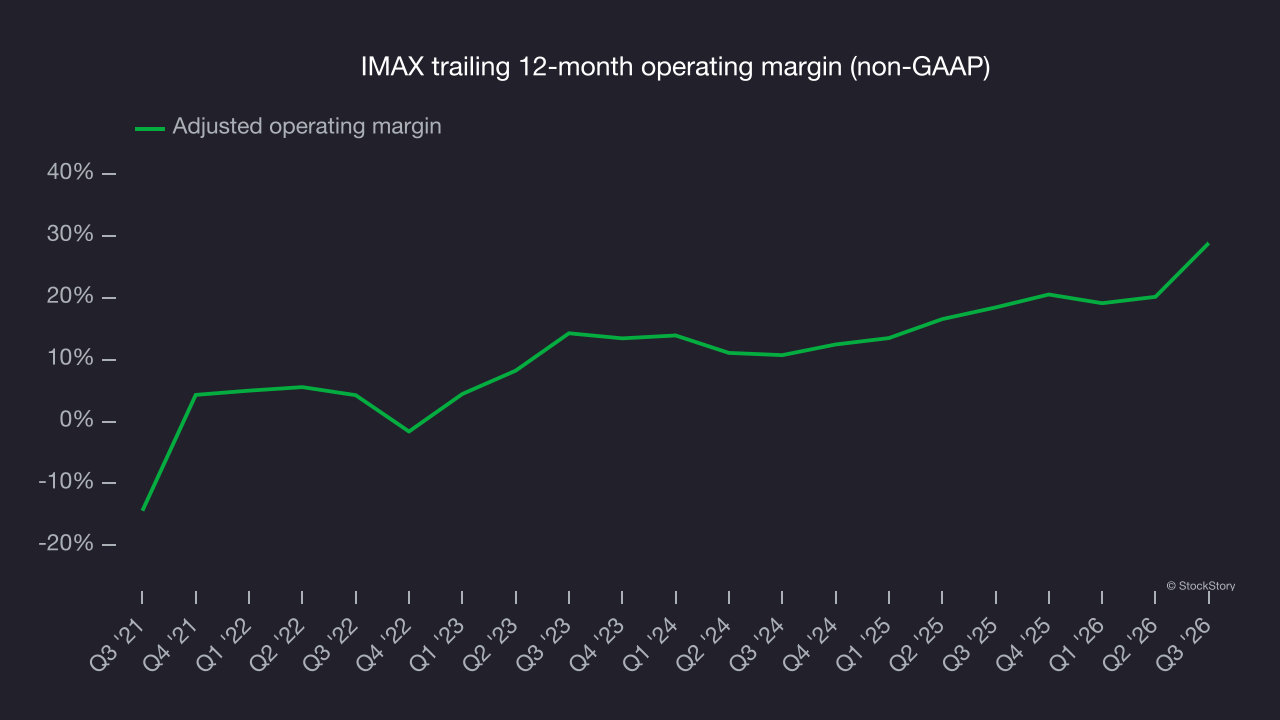
This quarter, IMAX generated an adjusted operating margin of 48.5%, up 21.3 percentage points year on year. This was a positive development, showing improved efficiency.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
IMAX’s full-year EPS flipped from negative to positive over the last five years. This is a good sign and shows it’s at an inflection point.
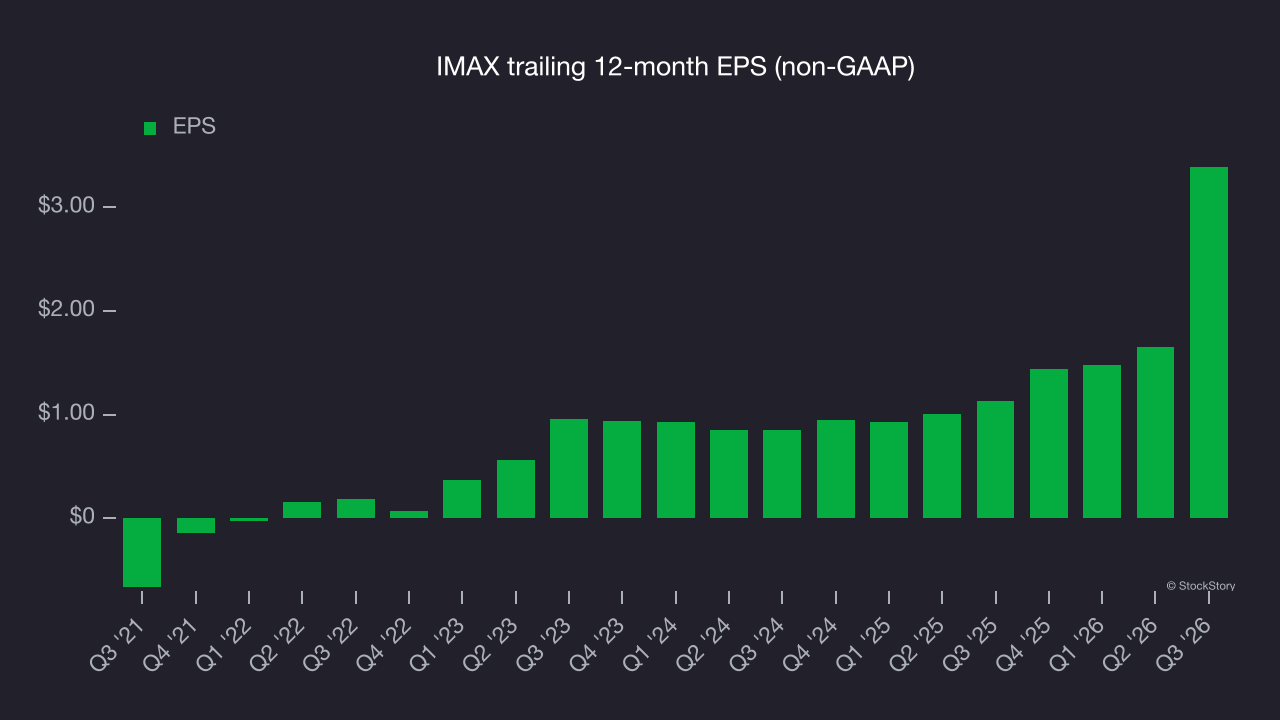
As with revenue, we analyze EPS over a shorter period to check for changes in the business.
IMAX’s EPS grew at a rapid 99.7% compounded annual growth rate over the last two years, higher than its 18.3% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
Diving into IMAX’s quality of earnings can give us a better understanding of its performance. IMAX’s adjusted operating margin has expanded over the last two years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, IMAX reported adjusted EPS of $2.21, up from $0.47 in the same quarter last year. Adjusted EPS easily cleared analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects IMAX’s full-year EPS to shrink by 35.5% from $3.39 to $2.19, according to S&P.
Key takeaways from IMAX’s Q3 results
IMAX’s wide revenue beat stood out in a quarter that also saw EPS top analysts’ consensus estimates. Those results made for a strong quarter with clear positives. Shares rose 3.4% to $53.53 immediately after the results.
IMAX reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. That decision requires considering its valuation, business quality and latest quarterly results. For more on IMAX, read our full research report here (it’s free).