
Monarch Casino & Resort (MCRI) Earnings Beat And Dividend Put Fair Value Back In Focus
Monarch Casino & Resort (MCRI) just paired a fresh quarterly earnings release with a new cash dividend of $0.30 per share, putting both profitability and direct shareholder payouts in focus for investors.
Despite the earnings beat and dividend announcement, Monarch Casino & Resort’s share price has eased around 5% over the past month and about 9% over the last quarter. It still carries a 17.8% year to date share price gain and a 24.1% total shareholder return over the past year, which hints at longer term momentum that has cooled near the recent US$113.13 level as investors reassess growth potential and risk after a strong multi year run.
Scan how Monarch Casino & Resort’s mix of earnings strength and fresh dividends compares with other potential opportunities by reviewing the 35 high quality undervalued stocks currently drawing attention.
After Monarch Casino & Resort’s pullback from recent highs, the tension is clear. Are you looking at a late stage story, or a still reasonable entry point on the current valuation?
Preferred P/E of 17.3x for Monarch Casino & Resort: Is it justified?
On simple earnings terms, Monarch Casino & Resort changes hands at a P/E of 17.3x, while the SWS DCF model points to a fair value near $195.02 versus the latest $113.13 close. That mix of signals puts the current tag in an interesting middle ground where earnings and cash flow views do not fully line up.
The P/E ratio measures how much investors are paying for each dollar of profit. For a hospitality operator like Monarch Casino & Resort, this gauge ties directly to how the market weighs its casino and resort earnings power against peers that share similar cyclical and capital intensive traits.
Relative measures are helpful here. The stock trades on a 17.3x P/E compared with the US Hospitality industry average of 20.4x and a peer group average of 18.1x. This suggests the equity is priced lower than comparable companies on reported earnings. Yet the estimated fair P/E of 14.9x implies the current multiple is richer than the level the fair ratio work points to. This is a range the market could eventually converge toward if sentiment cools.
Explore the SWS fair ratio for Monarch Casino & Resort.
Result: Price-to-earnings of 17.3x (ABOUT RIGHT)
DCF outputs tell a different story. The SWS DCF model indicates a fair value of $195.02, which sits well above the $113.13 market price and lines up with the separate statement that the shares trade roughly 42% below that internal estimate of value. This approach projects Monarch Casino & Resort’s future cash flows and discounts them back to today using a required return to estimate what those streams might be worth now.
For a business tied to destination gaming and hospitality, cash generation and capital intensity matter a lot. The DCF view suggests the current quote does not fully reflect the company’s earnings track record, high quality profit profile, and 20.2% return on equity, even with forecasts that point to revenue growth of 1.8% a year and earnings growth of 4.7% a year.
Look into how the SWS DCF model arrives at its fair value.
Still, Monarch Casino & Resort’s reliance on just two US properties and a single domestic revenue base leaves the story exposed to regional shocks and regulatory changes.
Find out about the key risks to this Monarch Casino & Resort narrative.
Another View: SWS DCF Model Points Higher For Monarch Casino & Resort
The earnings multiple gives one story for Monarch Casino & Resort. The SWS DCF model gives another. On that cash flow view, an estimated fair value of $195.02 against the recent $113.13 level suggests the shares may be undervalued on longer term cash generation.
For investors, that kind of gap can cut both ways. It can point to opportunity if the cash flows materialise as expected, or to risk if the projections and discount rate prove too optimistic once conditions change.
Look into how the SWS DCF model arrives at its fair value.
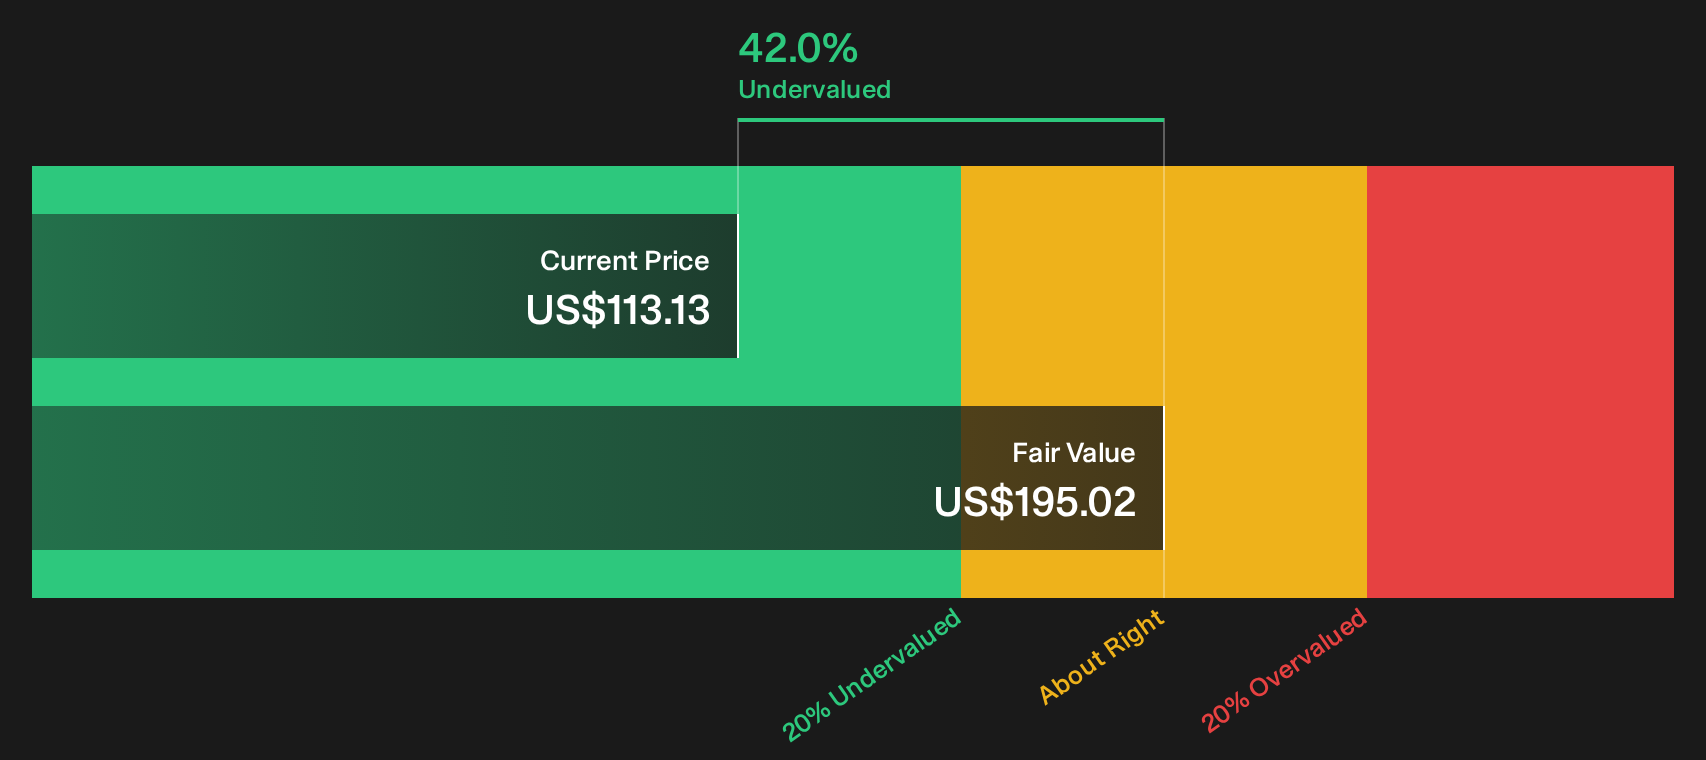
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Monarch Casino & Resort for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Monarch Casino & Resort’s value story. If you want to move fast and make your own call, start with the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Monarch Casino & Resort?
If Monarch Casino & Resort has your attention, do not stop there. Cast a wider net and compare a few curated shortlists that match different investing angles.
- Target sturdier balance sheets and steadier fundamentals by scanning a carefully filtered list of solid balance sheet and fundamentals (24 results) that keeps weaker profiles off your radar.
- Hunt for potential value opportunities by reviewing a hand picked 35 high quality undervalued stocks that combines quality metrics with pricing gaps the market has already set.
- Spot underfollowed opportunities early by checking a focused 19 high quality undiscovered gems before attention and capital crowd into the same tickers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com