
Is Butterfly Network (BFLY) Undervalued As Earnings Improve And Guidance Rises?
Butterfly Network earnings and guidance move into focus
Butterfly Network (BFLY) is back on investors’ radar after third quarter results showed higher revenue year over year, a smaller net loss, and an increase in full year revenue guidance.
Butterfly Network’s share price has swung sharply this year, with a 1-day share price return of 5.78% after the earnings and guidance update, set against a 30-day share price decline of 27.83% and an 80.53% year to date gain. The 1-year total shareholder return of 169.72% and the very large 3-year total shareholder return near 7x point to strong longer term momentum that recent volatility has not fully erased.
Scan other health-focused AI plays showing similar earnings momentum by zeroing in on the hand-picked 38 healthcare AI stocks that match Butterfly Network's blend of medical technology and software-driven tools.
Butterfly Network now appears to be a stronger medical imaging business based on recent results and guidance. The key question is whether the stock already reflects that progress or still offers valuation upside.
Most Popular Narrative: 39% Undervalued
Butterfly Network closed at $6.77, while the most followed narrative anchors fair value around $11.17, which puts a spotlight on how future high margin revenue shapes that gap.
The main thing that has to go right is that Butterfly Network converts its high-margin Embedded deals, Home and Community Care rollout and enterprise contracts into durable, recurring revenue that offsets softer core POCUS and international trends, while managing dilution risk.
The current valuation implies the share price does not fully reflect this narrative’s view that Butterfly Network is undervalued and that the company’s progress on high-margin Embedded growth, improving gross margins and reduced adjusted EBITDA losses could matter more than recent insider selling and international softness.
See why 39 investors see Butterfly Network as 39% undervalued.
Result: Fair Value of $11.17 (UNDERVALUED)
Still, sustained softness in core POCUS and international revenue, together with potential dilution from the US$150m equity program, could challenge the perception that Butterfly Network is undervalued.
Find out about the key risks to this Butterfly Network narrative.
Another View On Butterfly Network’s Valuation
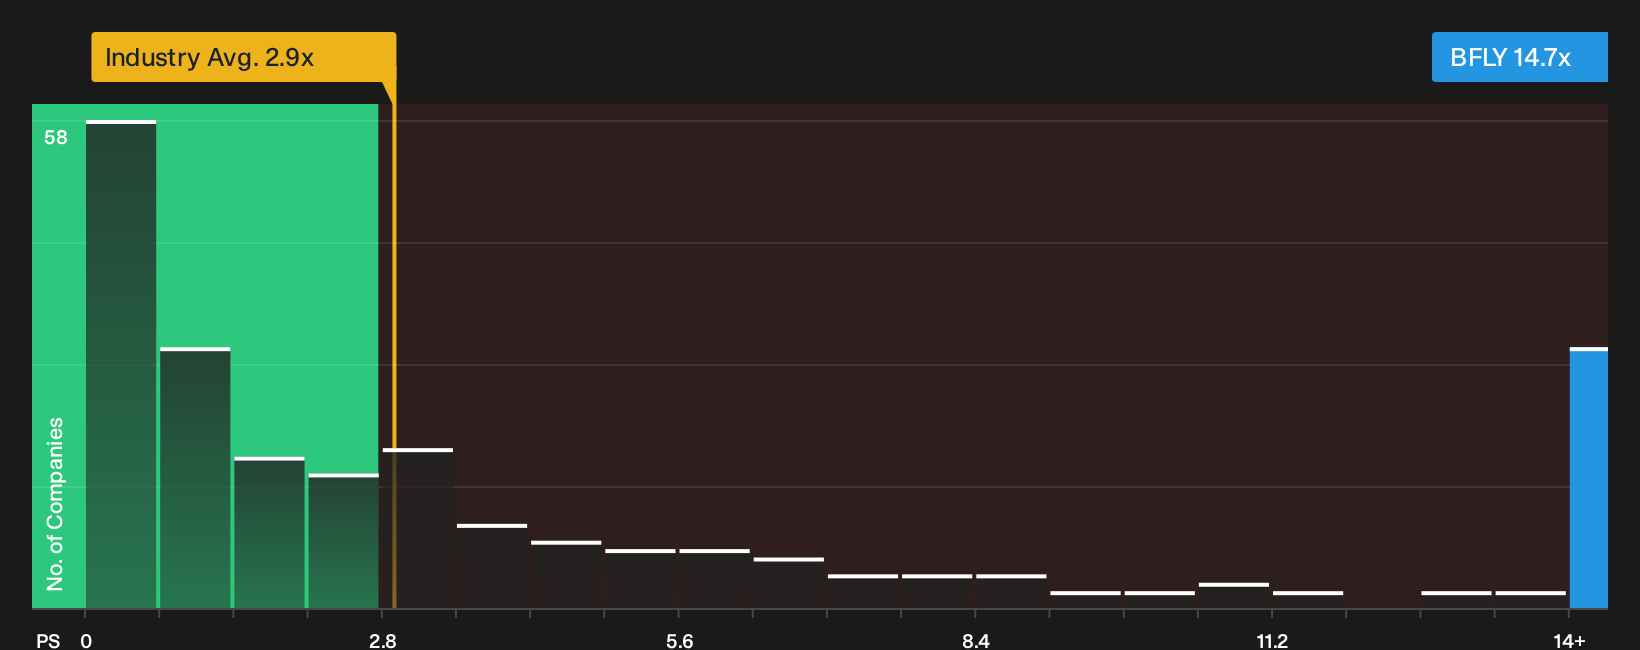
The story changes when the focus shifts from fair value to what investors are actually paying for Butterfly Network’s revenue today. The stock trades on a P/S of 14.7x, compared with 2.9x for the US Medical Equipment industry, 3.4x for peers, and a fair ratio of 3.6x that the market could move toward over time. That gap points to meaningful valuation risk if sentiment cools or revenue expectations reset.
Before leaning too heavily on any single multiple, it can help to zoom out and see what the numbers say in context of earnings quality, growth and cash flows. See what the numbers say about this price — find out in our valuation breakdown.
For a clearer visual on how the current pricing stacks up against the sector, take a look at the relative P/S picture here:
Next Steps
If the mixed signals around Butterfly Network leave you torn, that is the point. This is a stock where both risk and upside sit in clear view. To weigh that balance for yourself, start with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Butterfly Network?
If Butterfly Network has your attention, do not stop there. Broaden your watchlist now and give yourself more options before the next wave of moves hits.
- Target potential mispricing by scanning a curated 35 high quality undervalued stocks that filters for quality companies where fundamentals and current pricing appear out of sync.
- Strengthen your defence by reviewing a 31 resilient stocks with low risk scores focused on resilient businesses with lower risk scores that can help steady a volatile portfolio.
- Get ahead of the crowd by tracking a 19 high quality undiscovered gems that highlights under-followed companies with solid underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com