
DoorDash (DASH) Earnings Put Instacart In Focus, Is It Still Below Fair Value?
DoorDash earnings spark fresh focus on Instacart deal
DoorDash (DASH) just reported third quarter results that put fresh attention on its planned Instacart acquisition, combining a strong delivery business with a pending move deeper into online grocery.
Short term traders have reacted quickly, with DoorDash posting an 8.33% 1 day share price return and a 10.94% 7 day share price return after the earnings release and Instacart headlines. However, the 90 day share price return is down 8.17% and the year to date share price return is down 9.65%, while the 3 year total shareholder return of 134.93% points to much stronger longer term momentum than the recent pullback implies.
Scan beyond DoorDash and compare the performance and balance sheet strength of other delivery and online grocery players with our curated list of solid balance sheet and fundamentals (24 results).
DoorDash now combines rising profits with a headline Instacart deal and a sharp rebound in the share price. The business looks strong. Is the current tag on the stock just as solid?
Most Popular Narrative: 22.5% Undervalued
Against a last close of $198.59, the most widely followed narrative pegs DoorDash fair value at about $256 per share. This puts the recent rally in the context of a larger earnings story driven by grocery, subscriptions and advertising.
Expansion of DoorDash into grocery and other new verticals, where this segment is currently the fastest growing and is guided to reach gross profit positivity in the second half of 2026, points to additional revenue and gross margin contribution that is not yet fully reflected in earnings.
See why 80 investors see DoorDash as 23% undervalued.
Result: Fair Value of $256.26 (UNDERVALUED)
Still, this bullish DoorDash story can be knocked off course if regulatory costs rise further or if grocery customers push back hard on higher delivery fees.
Find out about the key risks to this DoorDash narrative.
Another View: DoorDash Looks Expensive On Earnings
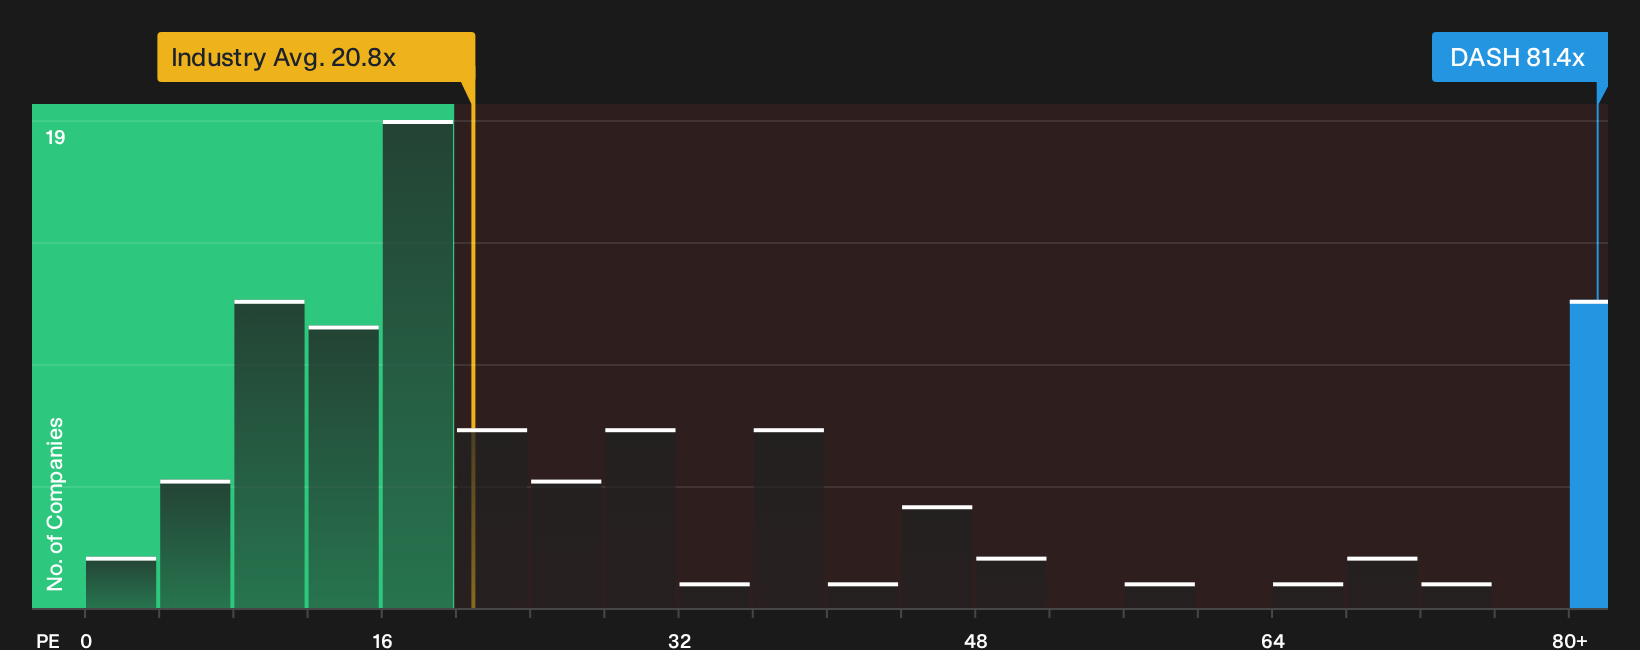
The story changes when you switch from fair value models to simple earnings multiples. DoorDash trades on a P/E of 81.4x, compared with 20.8x for the US Hospitality industry, 28x for peers and a fair ratio of 51.2x, which signals meaningful valuation risk if sentiment cools.
For investors who lean on earnings multiples, that gap raises a blunt question. Is the DoorDash premium a cushion for future growth or a thin layer of optimism that could compress quickly if expectations reset?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed views on DoorDash's valuation so far. If the balance between potential upside and risk seems narrow, act promptly, review the data carefully, and weigh the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond DoorDash?
Do not stop at DoorDash. Broaden your watchlist with other clear, data backed opportunities that match how you like to build a portfolio.
- Target quality and value together by scanning companies that pair strong fundamentals with attractive pricing through the 35 high quality undervalued stocks.
- Strengthen your income stream by reviewing potential high yield opportunities with defensible payouts via the 5 dividend fortresses.
- Dial down portfolio stress and focus on resilience by assessing companies with steadier risk profiles through the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com