
PHINIA (PHIN) Raises 2026 Outlook As Strong Results Put Valuation Back In Focus
PHINIA (PHIN) moved after the company raised its 2026 guidance and released third quarter numbers, giving investors fresh data on revenue, earnings and how the business is tracking against prior expectations.
Recent trading shows PHINIA’s momentum picking up, with a 1-day share price return of 4.08% and a 7-day move of 24.36% at a last close of US$71.73. However, the 90-day share price return declined 4.22%. The 3-year total shareholder return of 212.13% underscores how strongly longer term holders have been rewarded as investors reassess growth prospects and risk after the raised 2026 guidance and third quarter update.
Scan how PHINIA compares with other manufacturers showing strong price and earnings momentum by checking the hand picked 19 high quality undiscovered gems now catching investor attention.
PHINIA now screens as a solid, profitable industrial supplier with raised 2026 goals and a sharp recent rally. The real tension is whether that quality is already fully reflected in the current share price.
Most Popular Narrative: 19% Undervalued
PHINIA’s most followed narrative anchors fair value at $88.20 against the latest close of $71.73, which points to a material valuation gap while still tying everything back to cash generation and capital returns.
Disciplined cash generation and capital allocation, including raised 2026 free cash flow guidance to a range of US$210 million to US$250 million, capex held below the 4% of sales target and sizeable buybacks since the spin, creates scope for further per share earnings impact and potential re rating of PHINIA’s cash flow profile.
See why 9 investors see PHINIA as 19% undervalued.
The central narrative uses a 9.76% discount rate and arrives at a fair value of $88.20, which is about 19% above the current share price. That gap exists alongside analyst expectations for earnings to grow 10.45% per year and current net income of $189.0m on $3.62b of revenue.
Supporters of this view often focus on PHINIA’s mix of higher margin aftermarket activity, alternative fuel programs and prior buybacks, while critics highlight high debt levels, lower than 20% Return on Equity and slower expected revenue and earnings growth than the broader US market.
On balance, the prevailing narrative frames PHINIA as trading below an internally consistent fair value that already incorporates more modest revenue growth assumptions and a reduced profit margin outlook compared with earlier estimates.
Result: Fair Value of $88.20 (UNDERVALUED)
Still, PHINIA’s reliance on internal combustion technology and management’s lower 2026 margin outlook could both undermine this undervalued thesis if pressures persist.
Find out about the key risks to this PHINIA narrative.
Another View: PHINIA Through The P/E Lens
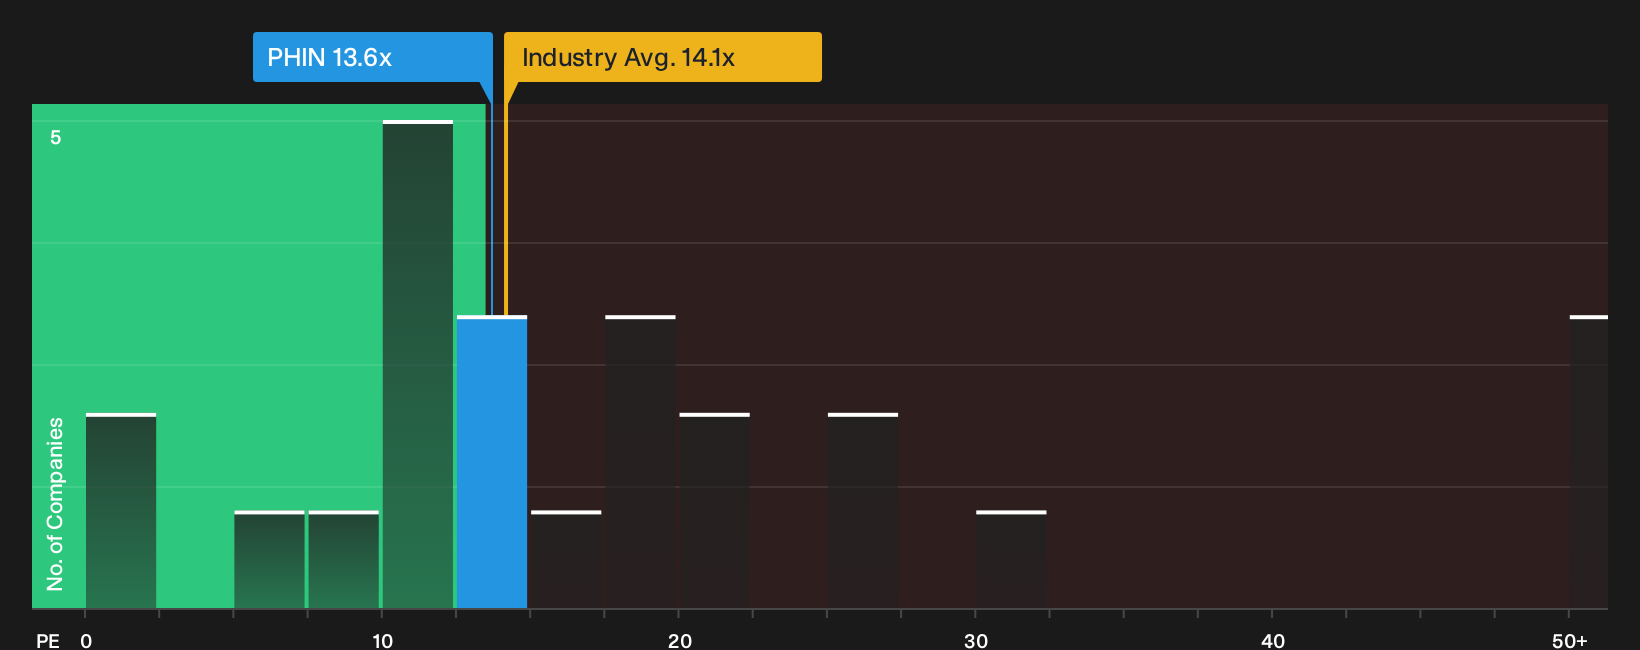
A second look at PHINIA swaps cash flow models for a simple earnings multiple. The stock trades on a P/E of 13.6x, above its fair ratio of 12.8x and the 12.7x peer average, yet below the US Auto Components group on 15.1x. That mix hints at some valuation risk if sentiment cools before earnings catch up. Is this a modest premium worth paying or a signal to be more cautious on the upside already implied?
To see how this earnings based view stacks up against a fuller valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on PHINIA so far or leaning one way already? Act while the data is fresh, review both the concerns and the upside, then weigh the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond PHINIA?
If PHINIA has sharpened your focus on quality, do not stop there. Fresh ideas now can shape the next leg of your portfolio’s journey.
- Target potential mispricing by scanning companies that look cheap on both quality and valuation using the 35 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses that appear in the 5 dividend fortresses.
- Dial down portfolio stress by filtering for companies that pass the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com