
Tidewater (TDW) Stock May Be Reasonably Priced As Earnings Support Improves
Tidewater has delivered a powerful multi year run, and the recent pullback now puts a sharper spotlight on whether the current share price still lines up with what its earnings can support. With the stock closing at US$73.54, the key issue is how much of the past gains can be justified by the underlying profit stream.
- Over the past 5 years, Tidewater has produced a very large total return, which raises the question of how much earnings strength is already baked into the valuation.
- The business model relies heavily on converting operating performance into cash that can service its asset base, which may support or limit how much investors are willing to pay for each dollar of profit.
- The analysts covering Tidewater have run their own numbers. See what analysts think Tidewater's shares could be worth.
The issue now is whether Tidewater's recent price, after a sharp multi year climb and shorter term declines, is adequately supported by its earnings profile.
If you are comparing Tidewater with other ideas that also depend on what earnings can justify, a focused screener of 35 high quality undervalued stocks can be a helpful next step for research.
Is Tidewater a Bargain on Earnings?
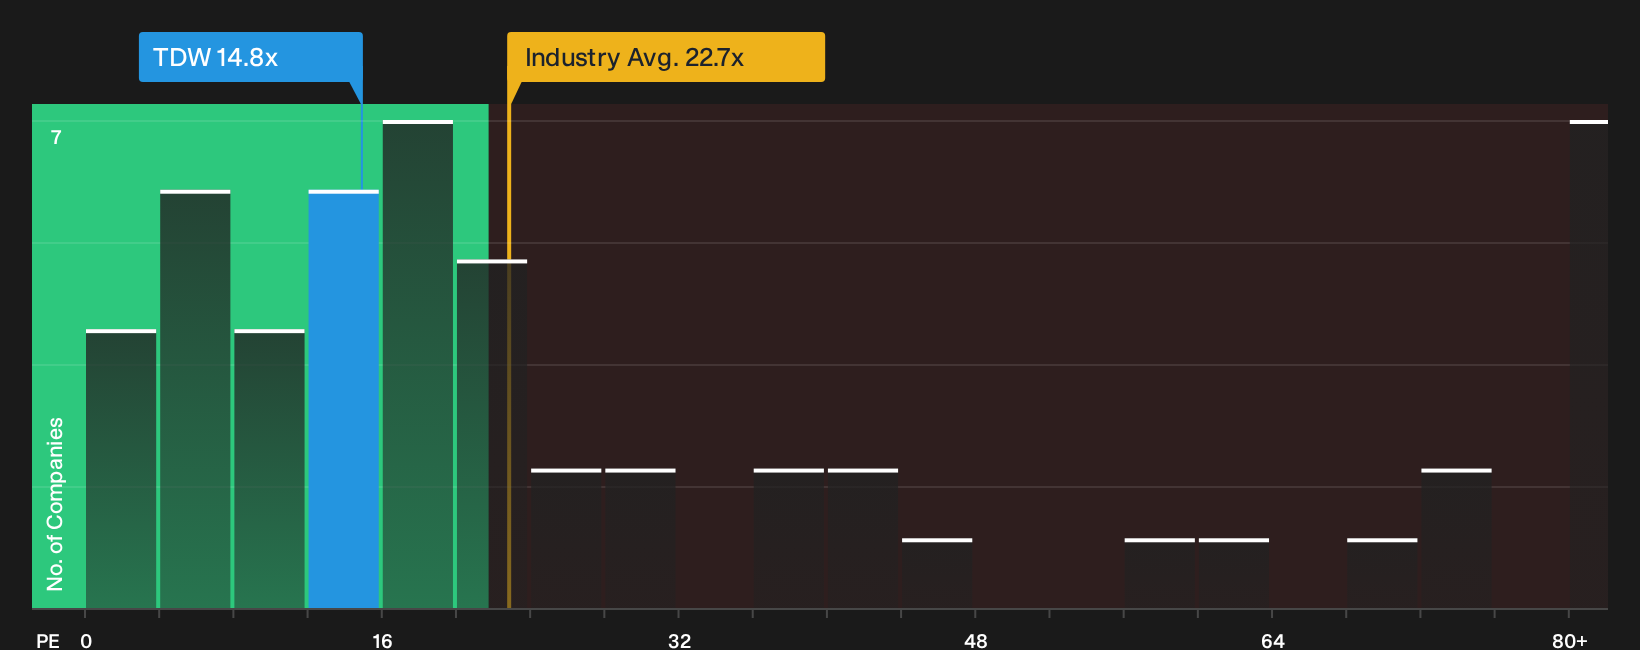
The P/E ratio fits Tidewater because investors often judge an earnings focused business by how many dollars they are paying for each dollar of profit. At the current share price, Tidewater trades on a P/E of about 14.8x, which is well below the Energy Services industry average of roughly 22.7x and also under the broader peer group near 32.4x.
The fair value framework, which adjusts for Tidewater's own growth profile, margins, size and risk, points to a higher P/E as a reference level than where the stock trades today. That gap suggests the market is pricing the shares more cautiously than this tailored yardstick implies, so holders have to decide whether that discount reflects genuine business risk or simply low expectations that earnings could cover over time. Explore the numbers behind Tidewater's P/E valuation.
The Tidewater Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Tidewater pick up where the valuation puzzle leaves off. They set out the specific earnings, margin and growth paths that would need to hold for the stock to look meaningfully cheaper or more expensive than today. Each view links its number to a clear stance on how Tidewater's growth, profitability and risk profile could evolve, giving you a reference point you can revisit as fresh results and new information come through.
Community views on Tidewater are split between tight vessel supply powering more earnings and conflict linked costs eating into that potential.
Bull case: 22% undervalued
"The current narrative that Tidewater is undervalued implies the share price does not fully reflect the earnings power suggested by recent cash flow..."
Discover why this Narrative puts Tidewater at 22% undervalued.
Bear case: 8% overvalued
"Bearish analysts expect Tidewater to face margin pressure as conflict related operating costs tied to Middle East exposure and elevated drydock spending offset tight vessel supply..."
Explore why this Narrative puts Tidewater at 8% overvalued.
Before deciding on Tidewater, there is one more signal to review
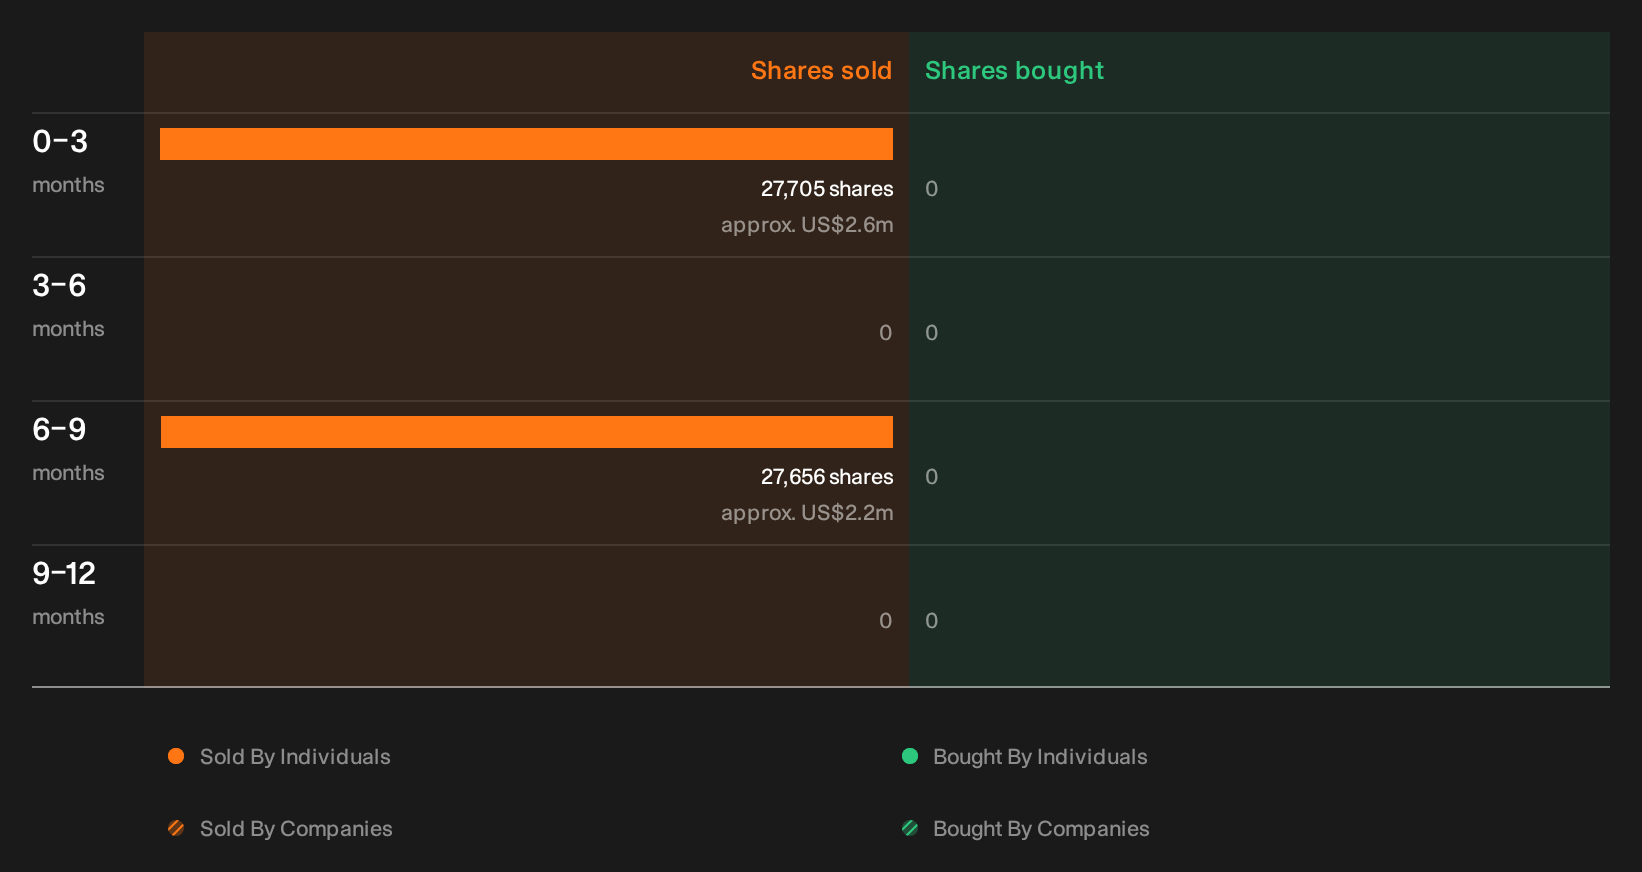
Tidewater's checks have highlighted recent selling activity by people inside the business, and the identities, sizes and possible read throughs are still for you to inspect directly. See the recent insider selling flagged for Tidewater.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com