
Dana (DAN) Stock May Be A Bargain Despite Its 119% Run
Dana Incorporated has delivered a powerful share price run in recent years, yet the latest pullback puts fresh focus on a simple question for investors: Is the current valuation that the market is placing on Dana stock properly grounded in the level of sales the business is generating?
- Over the past 3 years the share price has climbed 118.7%, which puts Dana's current valuation under a spotlight and raises the stakes for how its revenue base is judged.
- Recent updates around stronger commercial vehicle demand, a higher sales outlook in the range of US$7.75b to US$7.85b, and increased share repurchases can all influence how investors weigh the relationship between the stock price and future top line potential.
- There is a second opinion on Dana worth weighing. See what analysts think Dana's shares could be worth.
The issue now is whether the price investors are paying for Dana today is adequately supported by the scale and trajectory of its sales.
If you are considering whether Dana's recent pullback leaves sufficient sales support for the share price, it can be useful to compare that question across 35 high quality undervalued stocks.
Is Dana a Bargain on Sales?
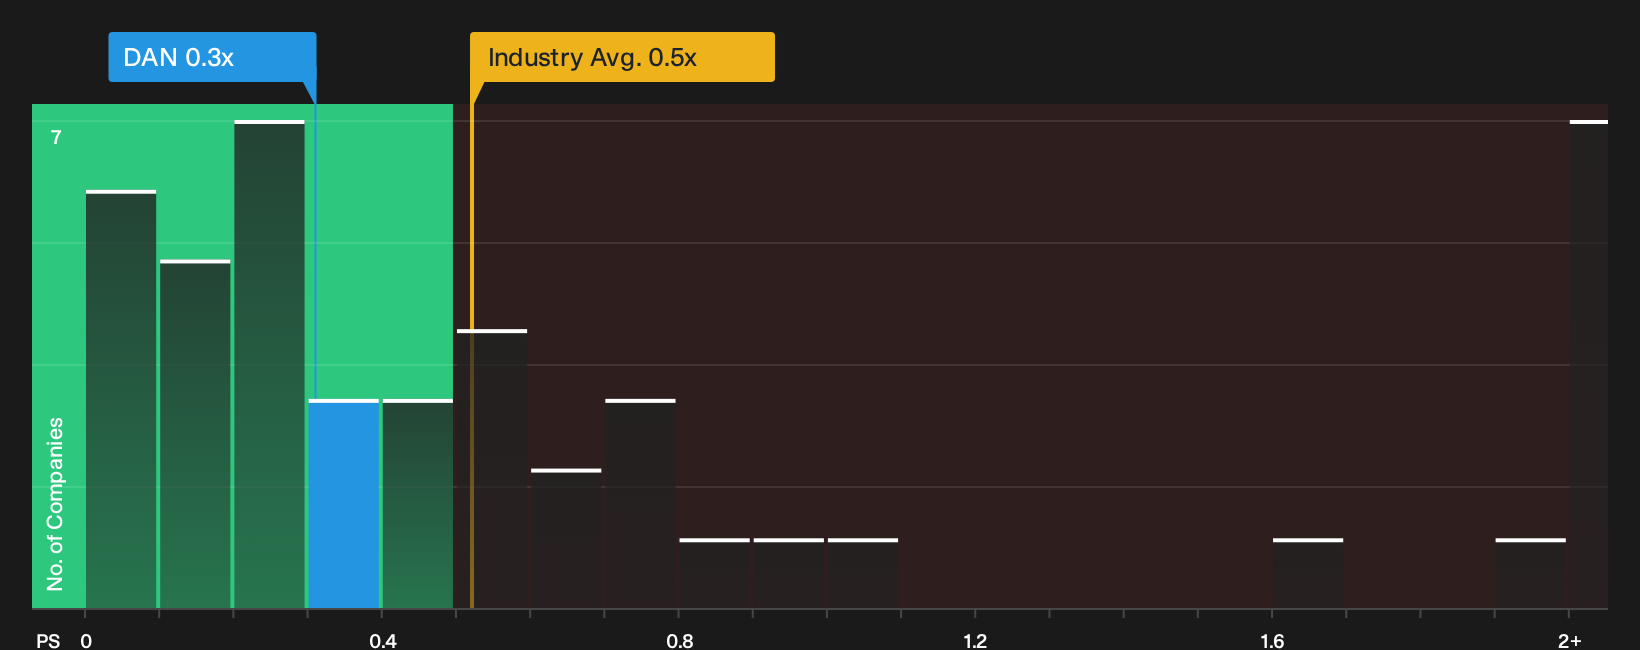
P/S works reasonably well for Dana because the headline debate is how much investors are paying for each dollar of revenue. On that yardstick, the stock trades on a P/S of about 0.3x. The wider Auto Components group runs closer to 0.5x on this metric and the peer set in the data is just under 0.6x, so the market currently prices Dana’s sales at a lower tag than many rivals.
That gap also shows up against a more tailored benchmark. The P/S level implied by Dana’s fair ratio, which adjusts for the firm’s growth profile, margins, size and risk, sits above the current 0.3x reading, so the shares screen as undervalued on this model. Because management has recently raised the 2026 sales outlook and increased share repurchases, the discount on P/S persists even after those updates. Explore the numbers behind Dana's P/S valuation.
The Dana Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S debate for Dana leaves off and spell out which assumptions on growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's price on the Community page. Instead of a single output from a ratio or valuation model, Narratives set out the future path that number relies on so you can watch over time whether Dana's progress lines up with it.
One of the top community narratives on Dana: 26% undervalued
"Long running cost reduction programs delivered US$35 million of quarterly savings and are planned to total US$325 million…"
Discover why this Narrative puts Dana at 26% undervalued.
Dana's price tag is only one piece of the decision
Valuation checks tell only part of the story for Dana, because the research also highlights specific risk factors that investors may want to weigh carefully before going any further. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com