
Lowe's Stock In Focus After Sales Outlook Cut
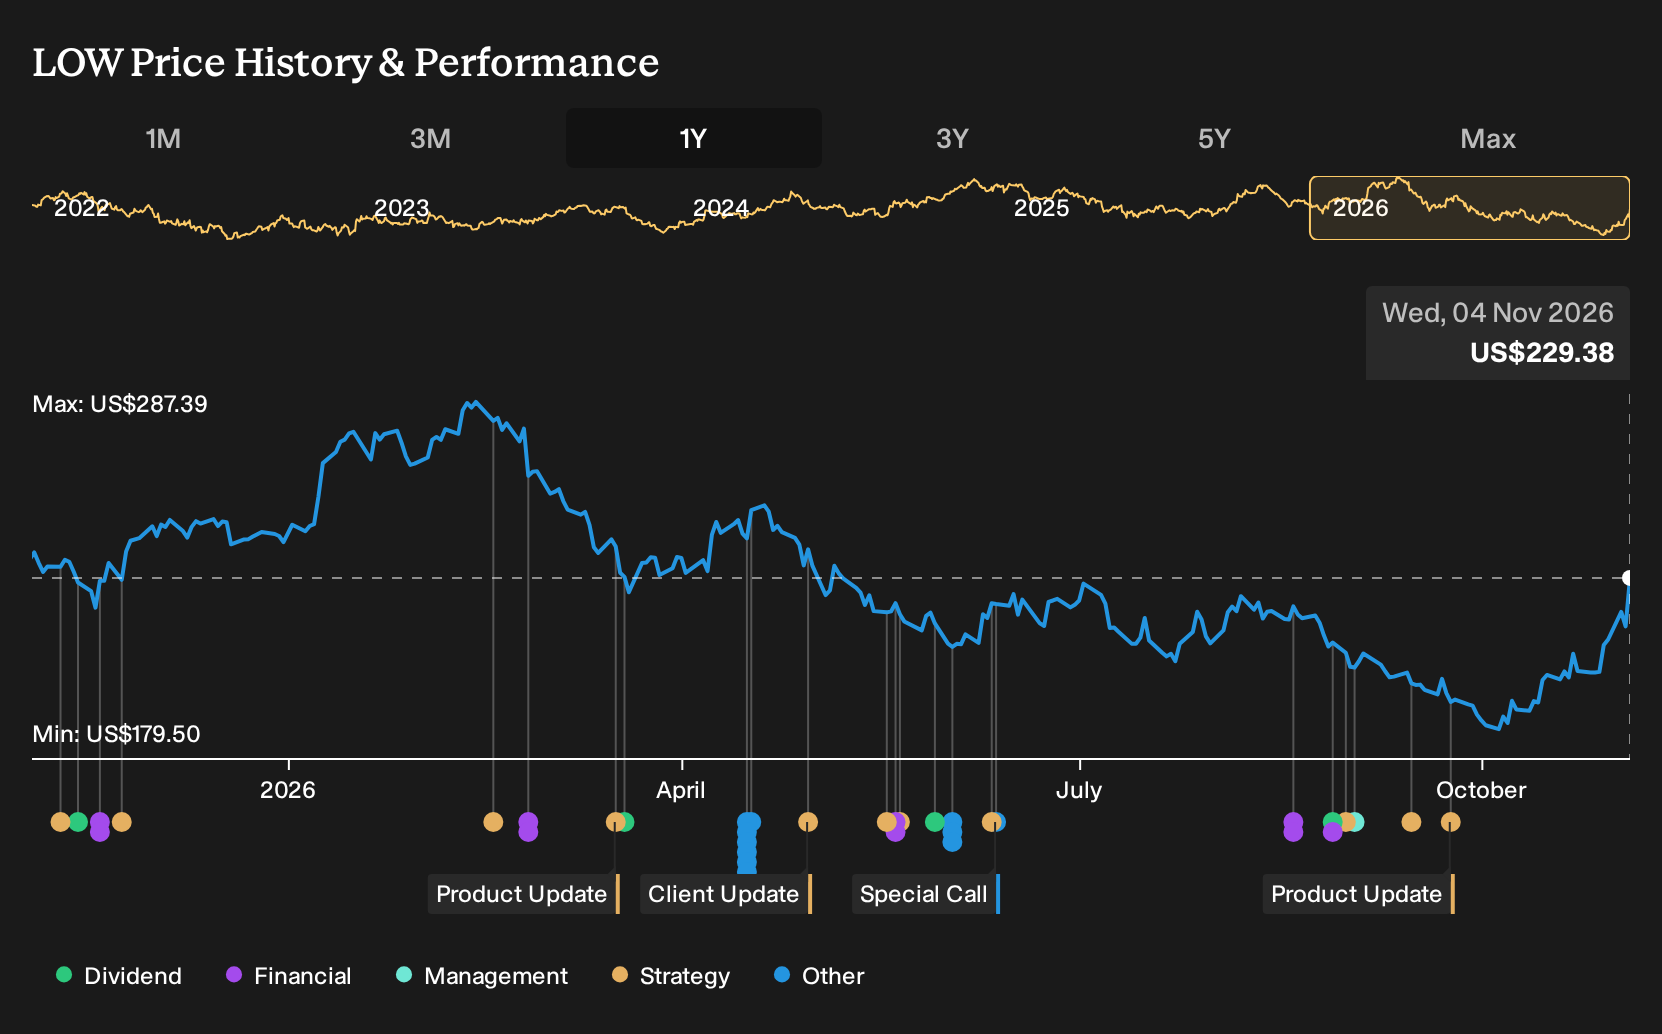
- Lowe's Companies management cut its full year 2026 sales outlook to about US$92b, pointing to softer consumer demand and ongoing housing market weakness that is weighing on its builder focused supply operations in the second half of the fiscal year.
- The reduced sales guidance shifts attention to how Lowe's balances weaker big ticket project demand with cost discipline, productivity programs, and its Pro and builder channels, which now face a tougher backdrop than assumed in earlier guidance.
- The focus now turns to how Lowe's investment narrative holds up when full year sales guidance moves lower on softer demand and housing trends.
Compare Lowe's Companies with other retailers facing similar housing and consumer demand pressures by scanning our hand picked list of solid balance sheet and fundamentals (24 results), which may better fit your risk tolerance.
Lowe's Companies Investment Narrative Recap
To own Lowe's Companies, you need to be comfortable with a home improvement chain leaning on Pro customers, digital channels, and the FBM and ADG acquisitions while end market demand feels softer. The cut to about US$92b of 2026 sales guidance keeps the immediate catalyst focused on execution. Investors will likely watch whether productivity programs and mix management support margins even if large projects stay slow.
The biggest operational risk right now is that housing turnover and big ticket projects remain muted, which would pressure both comparable sales and earnings tied to builder supply. Integration of FBM and ADG, plus the associated debt load, adds another layer of execution risk. The lowered outlook raises that risk slightly, but it does not, on its own, rewrite the long term expansion thesis.
The upcoming November 18, 2026 earnings release looks like the key checkpoint for this new guidance. It is the first detailed update since management reset sales expectations and moved operating margin and adjusted EPS guidance to the bottom of the prior range. That update will likely provide a clearer read on how Pro demand, commercial mix, and digital contribution are tracking against the US$92b revenue view.
In the short term, this same report may also clarify how Lowe's Companies is handling higher leverage tied to FBM, especially when adjusted debt to EBITDA sits around 3.0x and the goal is 2.75x by mid 2027. If progress on margins and cash generation appears steady, that would support the existing catalyst narrative around acquisitions and productivity. If not, the balance between expansion and balance sheet risk could become a more pressing issue for shareholders.
Lowe's Companies' narrative projects US$99.5b in revenue and US$7.8b in earnings by 2029. This is based on analysts' forecast of 3.2% yearly revenue growth and an earnings increase of about US$1.2b from US$6.6b today.
Uncover how Lowe's Companies' fair value indicates a 10% potential upside to its current price before sentiment around Lowe's Companies potentially closes that discount.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community cluster between about US$228.82 and US$255, which puts Lowe's Companies only modestly above or below where some private investors see balance. Those views still pre date the sales downgrade and cautious guidance, so you may want to weigh them against housing sensitive risks, leverage questions, and the upcoming earnings report before forming your own stance.
Explore 3 other Lowe's Companies fair value estimates, including one that suggests it could be worth just $228.82.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Lowe's Companies research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Lowe's Companies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate Lowe's Companies' overall financial health at a glance.
Looking for more investment ideas beyond Lowe's Companies?
If the Lowe's Companies story leaves you wanting a broader watchlist, you can cast the net wider using the Simply Wall St Screener to find businesses that better match your style, time horizon, and risk appetite.
- If you want potential upside without stretching your comfort on quality, consider a curated set of value focused opportunities through the 35 high quality undervalued stocks.
- If resilience matters more than rapid gains, weigh steadier opportunities using the 31 resilient stocks with low risk scores to spot businesses with more measured risk profiles.
- If you are hunting for under followed ideas with solid fundamentals, broaden your search with the 19 high quality undiscovered gems and build a watchlist that is not limited to household tickers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com