
Huron Consulting Group (HURN) Stock Looks Reasonable Following Its 225% Five Year Run
Huron Consulting Group has delivered a powerful long term share price run, and the recent pullback puts a fresh spotlight on whether earnings still support where the stock trades today. With that history in the background, the question now is how much of the business's current and expected profit is already embedded in the valuation.
- Over the past 5 years the stock has gained 225.2%, which makes the link between its earnings profile and market price especially important for anyone thinking about valuation today.
- Recent company updates pointed to higher profit expectations and a larger share repurchase program, which can influence how much investors are willing to pay for each dollar of current and future earnings.
- Your read on Huron Consulting Group is one view; the desks covering it have another. See what analysts think Huron Consulting Group's shares could be worth.
The stock's next move may depend on whether Huron Consulting Group's current share price is well aligned with what its earnings justify right now.
If you want a wider set of ideas with a similar earnings focused angle to Huron Consulting Group, a good next step is to scan the 35 high quality undervalued stocks.
Is Huron Consulting Group Fairly Priced on Earnings?
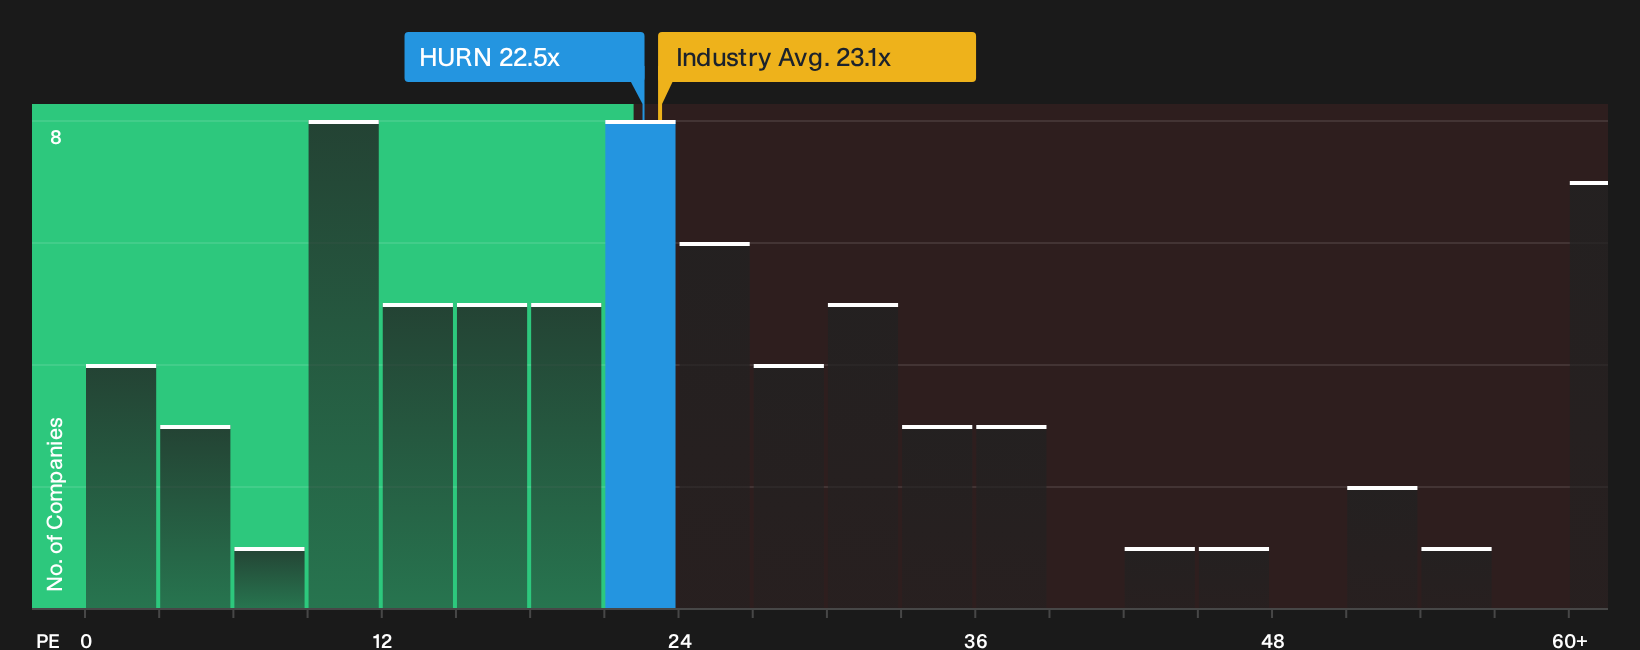
The P/E ratio is a sensible way to frame Huron Consulting Group because earnings remain the key yardstick for how this consulting business creates value for shareholders. From this perspective, the stock trades on a P/E of 22.5x, which is slightly below both the Professional Services industry average of 23.1x and the peer group at 23.5x. The modelled fair P/E, which reflects factors such as Huron’s profit profile, sector, size and risk, is very close to where the shares currently change hands.
Because the latest guidance lift and buyback expansion in 2026 have already pushed earnings expectations higher, the fact that Huron Consulting Group trades only a touch under these broader benchmarks suggests the market is not assigning a steep premium or a deep discount on current earnings. The present P/E indicates that investors are paying a going rate for each dollar of profit, so the key judgment is whether you think those earnings are durable and well supported over time. Explore the numbers behind Huron Consulting Group's P/E valuation.
The Huron Consulting Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Huron Consulting Group act as the missing link between the valuation puzzle above and the underlying expectations for growth, profitability and earnings quality that would need to play out for the stock to be worth significantly more or meaningfully less than today’s price. Instead of stopping at a single ratio or model output, Narratives describe the future that figure relies on so you can watch how the actual business performance lines up with those assumptions over time on the Community page.
Community views on Huron Consulting Group are split between those who see more value in its long term earnings power and others who think expectations already look full.
Bull case: 14% undervalued
"Huron Consulting Group ongoing shift toward outcomes-based, fixed-fee and recurring contracts, which reached 67% of revenue before reimbursable expenses by 2025, is increasing exposure to higher margin managed services and contingent-fee work..."
Discover why this Narrative puts Huron Consulting Group at 14% undervalued.
Bear case: 8% overvalued
"Although Huron Consulting Group is seeing strong client interest in AI related work, concerns that AI tools could automate portions of advisory workflows and enable clients to internalize more analytics may limit pricing power on AI enabled projects..."
Explore why this Narrative puts Huron Consulting Group at 8% overvalued.
For Huron Consulting Group, price is only one piece of the decision
Valuation can look reasonable on the surface while separate red flags sit in the background, so it is worth checking what recent risk checks are signalling before deciding how comfortable you feel with Huron Consulting Group. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com