
CTS (CTS) Raised Guidance, Is It A Bargain Or Fully Priced?
CTS (CTS) reported higher basic and diluted earnings per share for the third quarter and first nine months of 2026, and also raised its full-year sales guidance into a slightly higher range.
CTS shares trade at US$61.91 after a small one-day decline. However, the year-to-date share price return of 41.19% and 1-year total shareholder return of 43.54% point to strong underlying momentum that recent earnings and raised sales guidance help explain.
Compare CTS's momentum and earnings backdrop with a hand picked group of quality opportunities in the 19 high quality undiscovered gems to see what else is quietly gaining traction in this corner of the market.
CTS has rallied hard, yet the stock still trades below the average analyst target while one fair value gauge points to a premium. Which side of that gap appears to be closer to reality?
Most Popular Narrative: 12% Undervalued
CTS closed at $61.91, while the most followed narrative pegs fair value at $70.67. As a result, the story leans toward an undervalued setup built on mix shift and margins rather than a simple momentum trade.
The company's continued diversification into high growth end markets such as medical, industrial, and aerospace and defense, now reflected in diversified end markets contributing 59% of revenue and growing faster than transportation, supports the case that CTS can keep lifting revenue and sustaining higher gross margins.
Structural increases in automation, device connectivity, and industrial digitalization, evidenced by industrial sales of US$40 million in Q2 2026 with a book to bill of 1.11, position CTS's sensing and control products to capture additional orders that can add to revenue and EBITDA over time.
See why 3 investors see CTS as 12% undervalued.
Result: Fair Value of $70.67 (UNDERVALUED)
Still, softer transportation demand and ongoing cost pressures from materials and tariffs could challenge the upbeat CTS margin story that analysts are leaning on.
Find out about the key risks to this CTS narrative.
Another View: CTS Through The DCF Lens
The popular CTS narrative points to a fair value of $70.67, yet the SWS DCF model puts future cash flow value at $52.20. That suggests the stock trades above this cash flow based estimate. How comfortable are you paying a premium if growth or margins settle below expectations?
For readers who want to see how the cash flow math stacks up against the current share price, take a closer look at the Look into how the SWS DCF model arrives at its fair value..
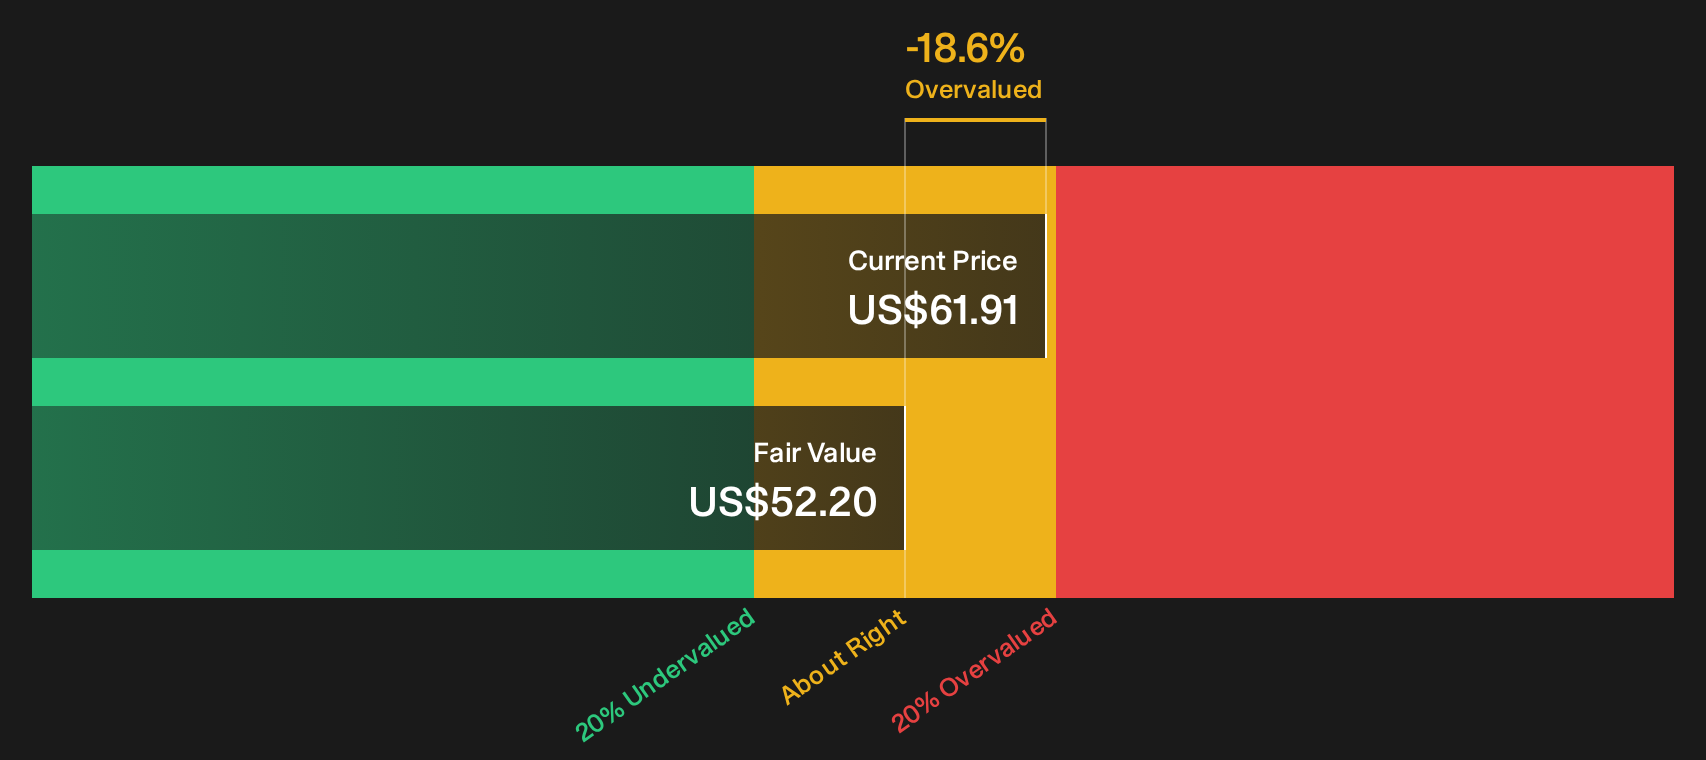
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CTS for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
The debate around CTS's value story is clear enough, yet the real edge comes from engaging with the numbers yourself and moving quickly to test your own thesis. If you want a concise snapshot of what optimists are already focused on, start with the 3 key rewards.
Looking for more CTS investment ideas?
If you only stop at CTS, you risk missing other opportunities quietly lining up strong fundamentals, yields, and upside potential across the market.
- Spot potential mispricing early by scanning the 35 high quality undervalued stocks that pair solid business quality with compressed expectations.
- Build a sturdier income stream by reviewing the 5 dividend fortresses that combine higher yields with consistent payout records.
- Sleep easier through volatility by focusing on the 31 resilient stocks with low risk scores that score well on financial strength and downside protection.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com