
Can RPC (RES) Justify Its Valuation Following A Revenue Gain And Impairment Led Loss?
RPC (RES) just posted third quarter 2026 results that combined higher sales with a swing to a net loss, as a large noncash impairment at Pintail Wireline hit earnings.
RPC shares trade at US$5.90, with a 7 day share price return that has fallen 12.33% and a 30 day share price return that is down 3.28%. However, the year to date share price return is up 6.69% and the 1 year total shareholder return is 12.05%, pointing to fading short term momentum after a stronger run that has included regular dividends and the latest quarter’s impairment driven loss.
Scan beyond RPC’s latest quarter and compare it with other oilfield service and energy contractors using our curated list of 19 high quality undiscovered gems as a reference set.
RPC now pairs a fresh impairment driven loss with a share price that has cooled after a solid year long run. The key question is whether that reset leaves enough upside to justify taking on the current set of risks.
Most Popular Narrative: 10% Undervalued
RPC closed at $5.90, while the most followed narrative points to a fair value of $6.54. That gap raises the question of whether today’s price already reflects the company’s push into newer technology and cleaner service lines.
The shift toward a more diversified service mix, boosted by value-added offerings and recent acquisitions (like Pintail in wireline), reduces revenue volatility and broadens exposure to growth geographies within North America. This supports improved top line stability and earnings growth versus historical cyclicality.
Continued investment in natural gas-powered pressure pumping equipment and other efficient, cleaner service lines directly addresses future demand for environmentally friendlier drilling solutions. This positions RPC to benefit from long-term client preference for lower-emission and high-efficiency operations, which can support pricing and market share gains and lift net margins.
See why 7 investors see RPC as 10% undervalued.
The valuation work behind that $6.54 figure rests on a discount rate of 7.31% and a view that earnings and margins can improve from current loss making levels. Analysts in this narrative expect revenue growth in the low single digits each year, with profit margins rising from just above zero into the mid single digit range over the coming years. That combination, together with a future P/E multiple of about 15x on projected 2029 earnings, underpins the conclusion that the stock is trading below the estimated fair value.
What matters for you is whether those ingredients feel reasonable. The thesis leans on RPC’s adoption of higher efficiency tools, its broader service offering across pressure pumping, wireline and rentals, and the ability of a $1.3b business with an established international footprint to support higher utilization and steadier profitability than in past cycles. It also assumes that competitive pressure, customer spending patterns and capital needs do not erode the margin improvement that the model builds in.
Result: Fair Value of $6.54 (UNDERVALUED)
Still, the thesis around RPC weakens quickly if pricing pressure in pressure pumping and wireline compresses margins, or if customer spending softens because of macro or commodity shocks.
Find out about the key risks to this RPC narrative.
Another View: What RPC’s Cash Flows Say
The first narrative leans on earnings forecasts and a future P/E to suggest RPC might be undervalued around $5.90. A different lens, our SWS DCF model, points the other way, with an estimated future cash flow value of $4.47, implying the shares trade above that level. Which lens do you trust more when cash and earnings tell different stories?
Look into how the SWS DCF model arrives at its fair value.
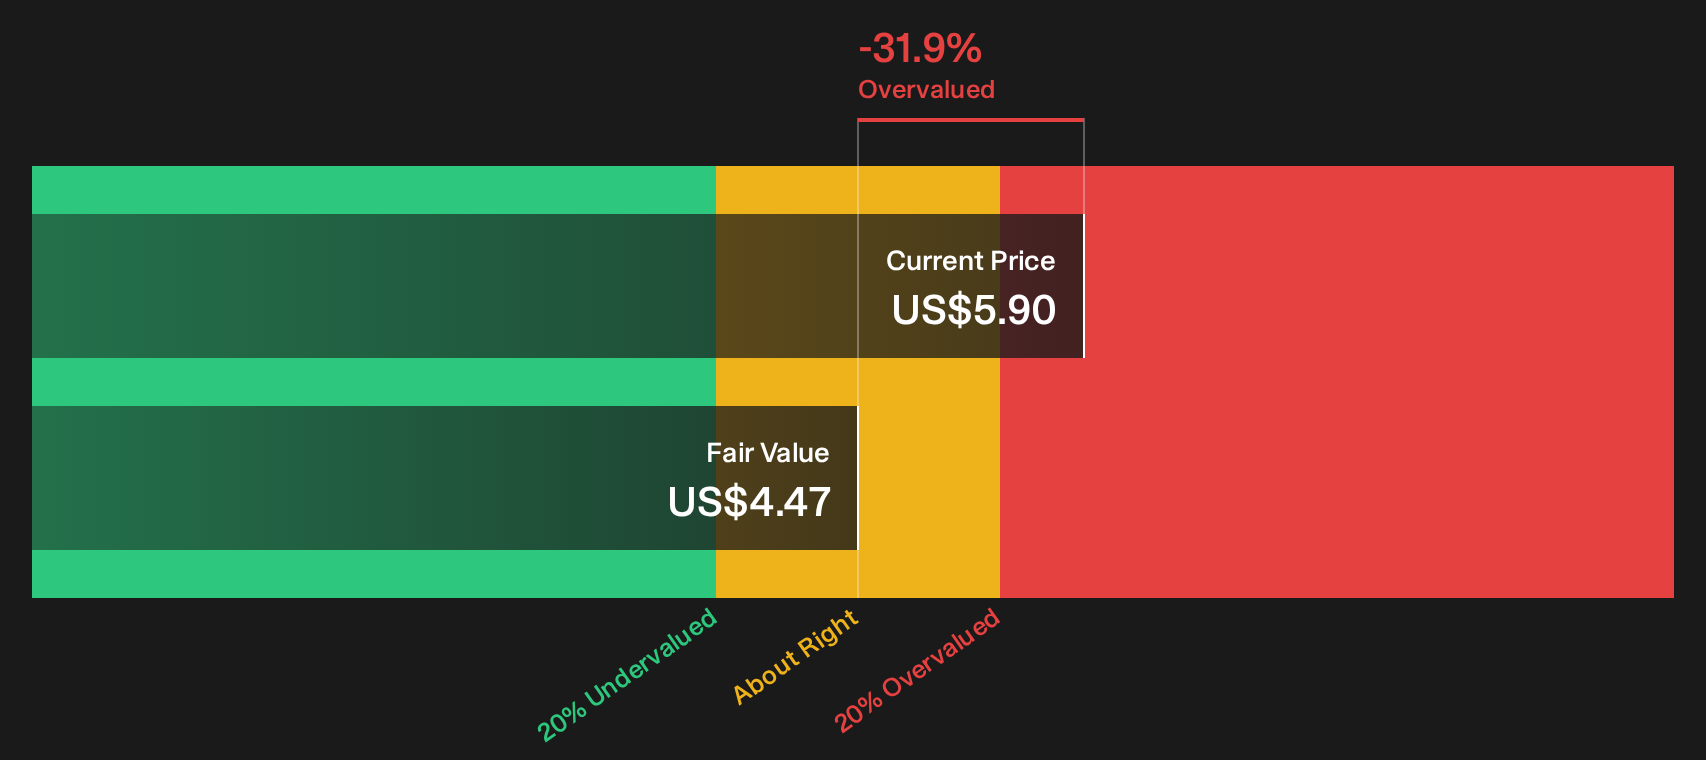
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out RPC for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed signals around RPC leave you uneasy, move quickly from headline impressions to hard numbers and form your own stance. To weigh both sides of the debate, review the 2 key rewards and 1 important warning sign.
Looking for more RPC investing ideas beyond this stock?
If RPC leaves you on the fence after these mixed signals, you may want to broaden your watchlist with fresh ideas so you are not relying on a single story.
- Target potential mispricings by scanning a curated pool of quality candidates through the 35 high quality undervalued stocks.
- Strengthen your defensive side by reviewing companies highlighted in the 31 resilient stocks with low risk scores.
- Build a more dependable income stream by assessing opportunities in the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com