
Is Incyte (INCY) Undervalued On Trial Progress And Raised Sales Guidance?
Incyte (INCY) has just put its oncology pipeline and financial guidance in the spotlight, with fresh trial data on KRAS G12D and MSS colorectal cancer therapies, along with a higher full year sales outlook for 2026.
Investors have been leaning into this story, with Incyte’s share price up 4.47% on the day of the news and a 21.13% year-to-date share price return, while the 3-year total shareholder return of 133.91% points to momentum that has already been building for some time.
Scan how Incyte’s oncology momentum compares with other financially solid healthcare names by checking the curated list of solid balance sheet and fundamentals (24 results) in the same space.
The latest pop in Incyte looks tied to concrete trial readouts and raised sales guidance, rather than a simple mood swing in the market. How much of that is already embedded in the current valuation?
Most Popular Narrative: 6% Undervalued
On the numbers, Incyte’s most followed valuation story puts fair value at $131.08, a touch above the latest $122.85 close. This frames the recent rally as still inside that narrative cushion rather than fully pricing it in.
The upcoming launches and label expansions of therapies like Opzelura, povorcitinib and Niktimvo in indications such as atopic dermatitis, vitiligo, hidradenitis suppurativa and GVHD remain a key driver for Incyte, with updated 2026 guidance pointing to higher total net sales of US$5.13 to 5.26b and Opzelura net sales of US$1.05 to 1.10b, which helps frame expectations for future revenue and earnings.
See why 58 investors see Incyte as 6% undervalued.
Result: Fair Value of $131.08 (UNDERVALUED)
Still, this story can change quickly if key oncology or MPN trials underperform, or if higher R&D and deal costs put more pressure than expected on Incyte’s margins.
Find out about the key risks to this Incyte narrative.
Another View on Incyte’s Valuation
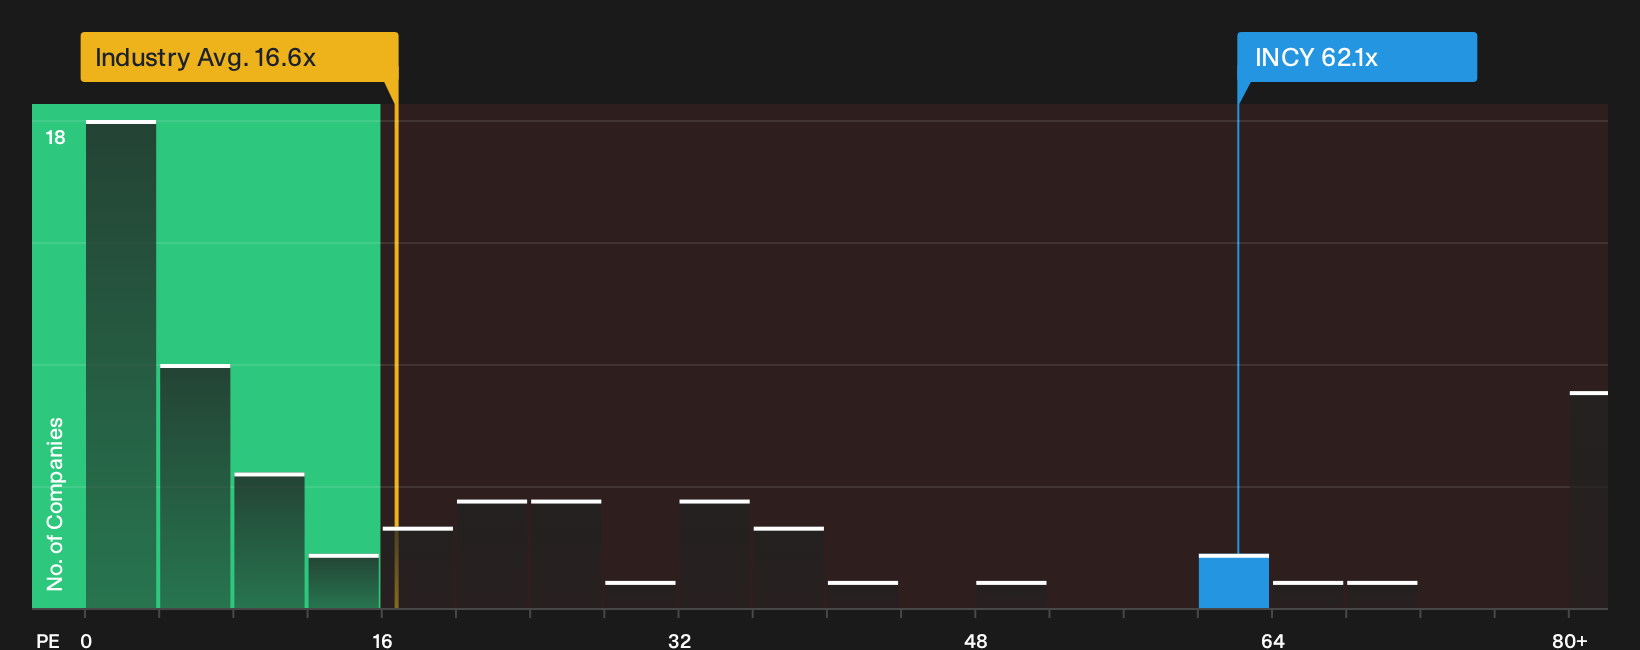
There is a catch. While the fair value story points to Incyte trading about 26% below intrinsic value, the market is currently paying a P/E of 62.1x, compared with 16.6x for the US Biotechs industry, 18.4x for peers, and a fair ratio of 25.8x. That gap suggests investors are already accepting meaningful valuation risk if execution slips at all.
To pressure test that richer earnings multiple against the underlying numbers, take a closer look at how the current price lines up with our fair ratio work. This work breaks down where the P/E might move toward over time in the full valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Incyte’s valuation and risk profile call for your own judgment, not just a headline read. Consider your options while sentiment is still forming and walk through the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Incyte?
If Incyte has your attention, do not stop there. Broaden your watchlist with a few focused stock ideas that target different styles of opportunity.
- Supercharge your hunt for quality by reviewing a list of solid balance sheet and fundamentals (24 results) that puts balance sheet strength and fundamentals front and center.
- Target resilient potential by scanning a 31 resilient stocks with low risk scores that filters for companies with sturdier risk profiles.
- Get ahead of the crowd by tracking a 19 high quality undiscovered gems that focuses on under-the-radar businesses with strong underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com