
Capri Holdings (CPRI) Stock Looks Undervalued Even After Its Sharp Rebound
Capri Holdings has just delivered a sharp share price rebound alongside upbeat earnings commentary, which puts a fresh spotlight on a simple question for you as an investor: After such a volatile few years, is today's valuation still in line with what the business is actually earning?
- Over the past 5 years the stock has fallen about 66.4%, which puts pressure on the case that Capri Holdings' current price is now better aligned with its earnings power.
- The recent earnings surprise, margin improvement and lower net debt may support expectations that Capri Holdings can convert more of its sales into sustainable profit, which matters directly for how much investors are willing to pay for each dollar of earnings.
- The analysts covering Capri Holdings have run their own numbers. See what analysts think Capri Holdings's shares could be worth.
The issue now is whether Capri Holdings' recent share price, after that rebound, is justified by the earnings the business is currently generating.
Capri Holdings has just delivered a sharp share price rebound alongside upbeat earnings commentary, which puts a fresh spotlight on a simple question for you as an investor: After such a volatile few years, is today's valuation still in line with what the business is actually earning?
- Over the past 5 years the stock has fallen about 66.4%, which puts pressure on the case that Capri Holdings' current price is now better aligned with its earnings power.
- The recent earnings surprise, margin improvement and lower net debt may support expectations that Capri Holdings can convert more of its sales into sustainable profit, which matters directly for how much investors are willing to pay for each dollar of earnings.
- The analysts covering Capri Holdings have run their own numbers. See what analysts think Capri Holdings's shares could be worth.
The issue now is whether Capri Holdings' recent share price, after that rebound, is justified by the earnings the business is currently generating.
If you are weighing Capri Holdings against other potential ideas, it can help to line it up beside companies in our value focused screen of 35 high quality undervalued stocks.
Is Capri Holdings a Bargain on Earnings?
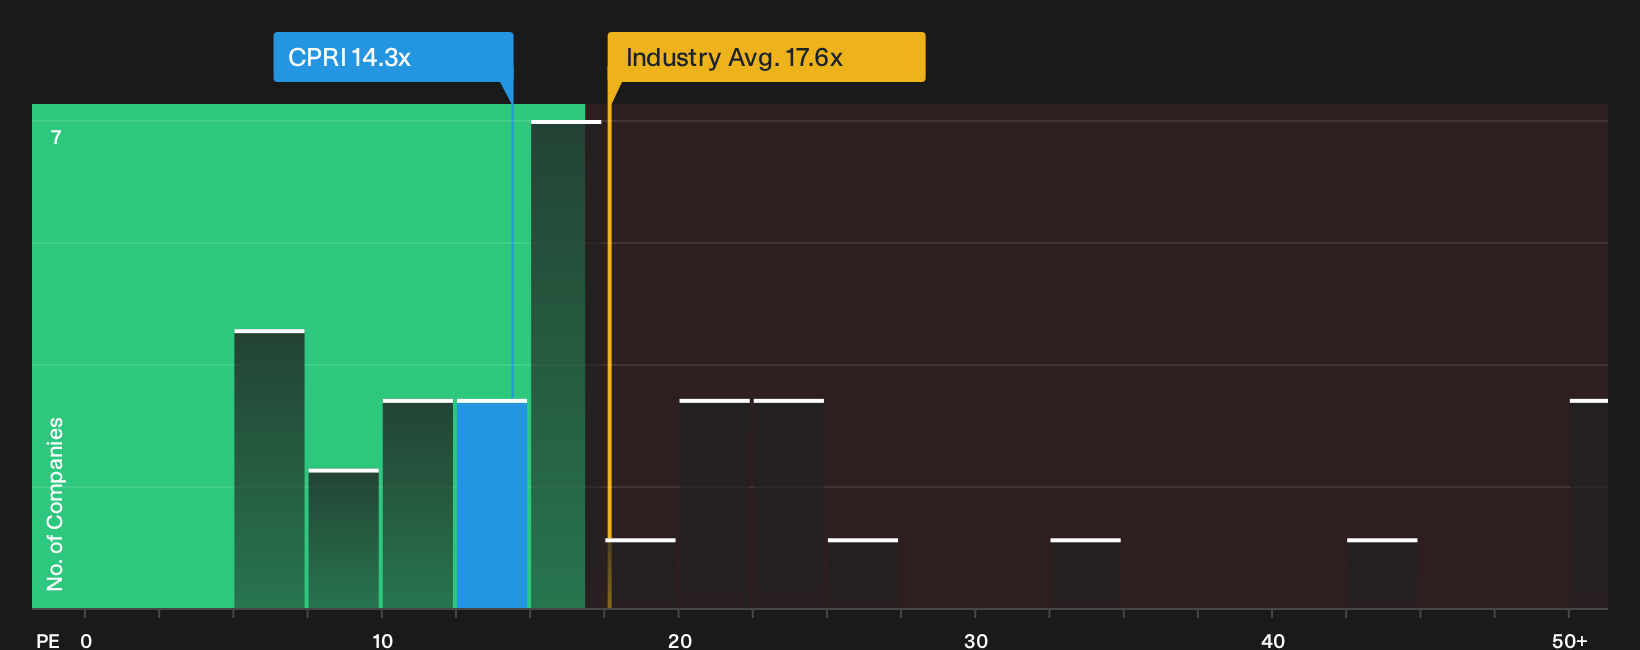
The P/E ratio suits Capri Holdings because earnings are the core yardstick investors are watching after the latest results surprise. Capri’s stock trades on roughly 14.3x earnings, which is below the Luxury industry average of about 17.6x and under the broader peer group closer to 19.2x. For a reader, that points to the market applying a lower price tag per dollar of profit than many comparable luxury stocks.
The Fair Ratio model, which blends factors such as Capri Holdings' profitability profile, sector, size and risk, implies a higher P/E than the current level, so the shares screen undervalued on this framework. Because the recent Q2 earnings beat lifted confidence but still leaves the P/E at a discount to those benchmarks, the current pricing suggests investors are not fully crediting the earnings power implied by that update. Explore the numbers behind Capri Holdings's P/E valuation.
The Capri Holdings Narrative: What Would Justify Today's Price?
Narratives for Capri Holdings pick up where the valuation puzzle leaves off and spell out which combinations of future growth, profitability and earnings outcomes would need to hold for the stock to trade meaningfully above or below today's level. Each view is framed as a thesis about Capri Holdings' long term earning power that you can revisit over time, rather than a one off snapshot. They are available on Simply Wall St's Community page.
Community views on Capri Holdings split between a patient turnaround story and a market that has already priced in most of the repair work.
Bull case: 6% undervalued
"Sequential improvement in full-price store traffic, reduced discounting, and growing success of new product launches, supported by data-driven marketing and influencer engagement, signal effective brand revitalization…"
Discover why this Narrative puts Capri Holdings at 6% undervalued.
Bear case: 18% overvalued
"Capri is leaning into digital channels, larger customer databases and social platforms to target younger consumers, yet the cut to FY27 revenue guidance from about US$3.525b to US$3.4b due to Michael Kors inventory delays, softer EMEA demand and FX shows that better targeting has not offset these shocks…"
Explore why this Narrative puts Capri Holdings at 18% overvalued.
Before acting on Capri Holdings' valuation, there is one more angle to check
Price and earnings only tell part of the story for Capri Holdings, since Simply Wall St's broader review has also flagged specific areas of concern that deserve your own closer look. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com