
Genesis Energy (GEL) Slides Following Its Pullback While Fair Value Stays In Focus
Genesis Energy (GEL) has posted revenue of US$1.83b and net income of US$24.59m. The partnership is valued at about US$1.76b with a unit price of US$13.26 as of early November 2026.
The recent move in Genesis Energy’s unit price tells a cautious story. The share price has fallen about 8% over the last session and is down roughly 17% year to date, while the 3 year total shareholder return of about 36% still reflects a stronger longer term payoff profile.
Scan beyond Genesis Energy’s recent pullback and compare it with a handpicked 35 high quality undervalued stocks designed to highlight businesses where price and fundamentals tell a different story.
For Genesis Energy, the recent slide in unit price contrasts with a 3 year total return that still looks healthy. Is most of the payoff already booked, or does the current valuation leave meaningful upside on the table?
Preferred P/E of 65.9x: Is it justified?
On simple price tags, Genesis Energy does not look cheap. The units last closed at $13.26 and the business trades on a P/E of 65.9x, far above both its own recent pullback and the kind of earnings multiple many midstream peers carry.
The P/E ratio compares what the market is willing to pay today for each dollar of current profit. For a partnership like Genesis Energy, which has just moved into profitability and reports net income of $24.59m on $1.83b of revenue, this metric can be heavily influenced by accounting items and one off gains. A small earnings base can make the multiple look very large even if the enterprise value is not extreme in absolute terms.
Context matters here. GEL is described as expensive based on its 65.9x P/E versus a 10.2x average for its peers and 12.3x for the broader US oil and gas group. That gap is wide. It implies the market is putting a much richer price on each dollar of current earnings than it does for similar businesses, even though recent revenue is reported to have declined 5.4% year on year and large one off items of $32.3m have affected the latest results to 30 June 2026.
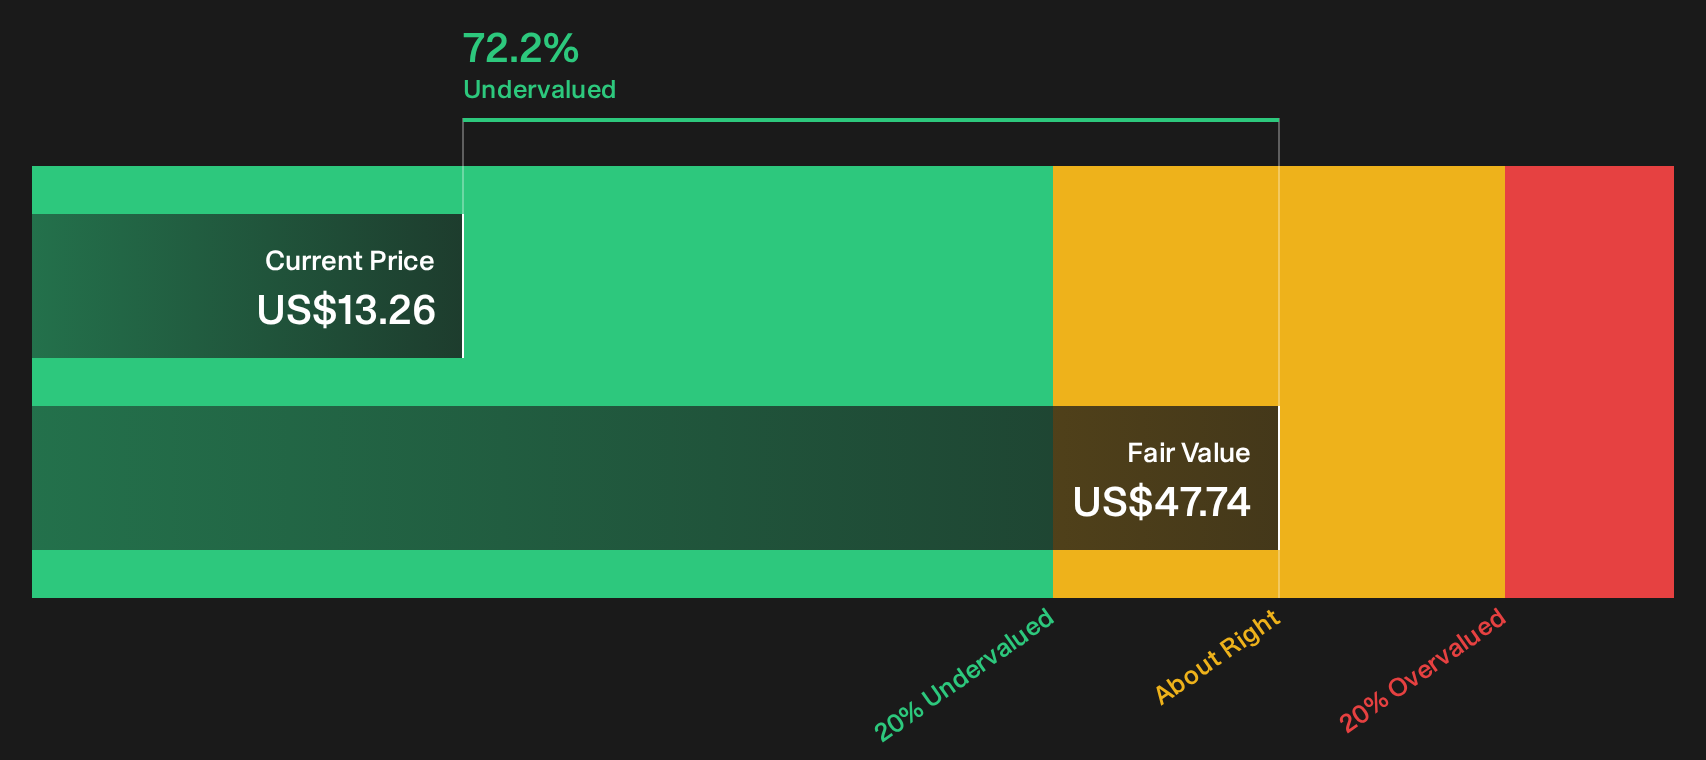
Against that richer earnings multiple, Simply Wall St’s DCF model paints a very different picture. The units at $13.26 are described as trading at a 72.2% discount to an estimated future cash flow value of $47.73. The DCF approach projects future cash flows, then discounts them back using a required rate of return, so the output is sensitive to assumptions about volume, pricing and reinvestment across Genesis Energy’s offshore pipelines, marine transport fleet and onshore logistics network.
For a midstream partnership that has recently become profitable, leans on higher risk funding and reports that dividend payments are not fully covered by earnings, this split between a rich P/E and a low DCF price can flag how accounting profit and cash flow expectations diverge. Investors comparing Genesis Energy with its sector peers would need to weigh whether the current level of reported earnings, which is affected by one off items, is a fair base for judging value or whether cash flow based estimates offer a more consistent yardstick.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 65.9x (OVERVALUED)
Still, the narrative can unravel quickly if revenue continues to drift lower or if distributions remain uncovered by earnings and force a reset in investor expectations.
Find out about the key risks to this Genesis Energy narrative.
Another View: Genesis Energy through the DCF lens
While the P/E of 65.9x makes Genesis Energy look expensive on current earnings, the SWS DCF model points in the opposite direction. At a unit price of $13.26, GEL is described as trading at a 72.2% discount to an estimated future cash flow value of $47.73.
This kind of gap can hint at opportunity if the cash flows arrive as expected. It also highlights real risk if forecasts prove too optimistic for a business carrying higher risk funding and uncovered distributions. Which lens do you trust more for GEL: accounting profit today or projected cash generation over time?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Genesis Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Genesis Energy can feel confusing, so move quickly and check the full spread of data before the story shifts again. To weigh those concerns against the potential upside, start with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Genesis Energy?
If Genesis Energy has you thinking harder about price versus fundamentals, do not stop here. Broader context from other opportunities can sharpen every decision you make.
- Target resilience by focusing on balance sheet strength and steady fundamentals through a curated list of solid balance sheet and fundamentals (24 results).
- Spot potential mispricing by scanning a 35 high quality undervalued stocks that blends quality markers with discounted valuations.
- Prioritise income stability by reviewing a 5 dividend fortresses built around higher yields and robust payout support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com