
Graham Corporation (NYSE:GHM) misses Q3 CY2026 sales expectations
Industrial fluid and energy systems manufacturer Graham Corporation (NYSE: GHM) missed Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q2 2027), but revenue rose 5.7% year on year to $69.76 million. On the other hand, the company’s outlook for the full year was close to analysts’ consensus estimates with revenue guided to $290 million at the midpoint. Its non-GAAP profit of $0.52 per share was 21.3% above analysts’ consensus estimates.
For more on Graham Corporation, read our free full research report.
Graham Corporation (GHM) Q3 CY2026 highlights:
- Revenue $69.76 million vs S&P analysts’ consensus estimates of $71.07 million (5.7% year-on-year growth, 1.8% miss)
- Adjusted EPS $0.52 vs S&P analysts’ consensus estimates of $0.43 (21.3% beat)
- Adjusted EBITDA $10.3 million vs analysts’ consensus estimates of $8.10 million (14.8% margin, 27.2% beat)
- Revenue guidance The company reconfirmed its revenue guidance for the full year of $290 million at the midpoint
- EBITDA guidance $37.5 million at the midpoint for the full year, above analysts’ consensus estimates of $36.88 million
- Operating margin 8.4%, up from 6.2% in the same quarter last year
- Free cash flow margin 63.8%, up from 14.3% in the same quarter last year
- Backlog $561.3 million at quarter end, up 12.2% year on year
- Market capitalization $816 million
Graham’s president and chief executive officer, Matthew J. Malone, stated, “Our second quarter results reflect strong execution across the business, highlighted by growth in Defense and Space, significant margin expansion and continued momentum across our end markets. Our record backlog of $561 million provides strong visibility into future growth and reinforces our confidence in the long-term opportunities ahead.”
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can deliver a good quarter or two, but many enduring ones grow for years. Over the last five years, Graham Corporation grew its revenue at a strong 19.8% compounded annual growth rate. Its growth surpassed the average industrials company and shows its offerings resonate with customers.
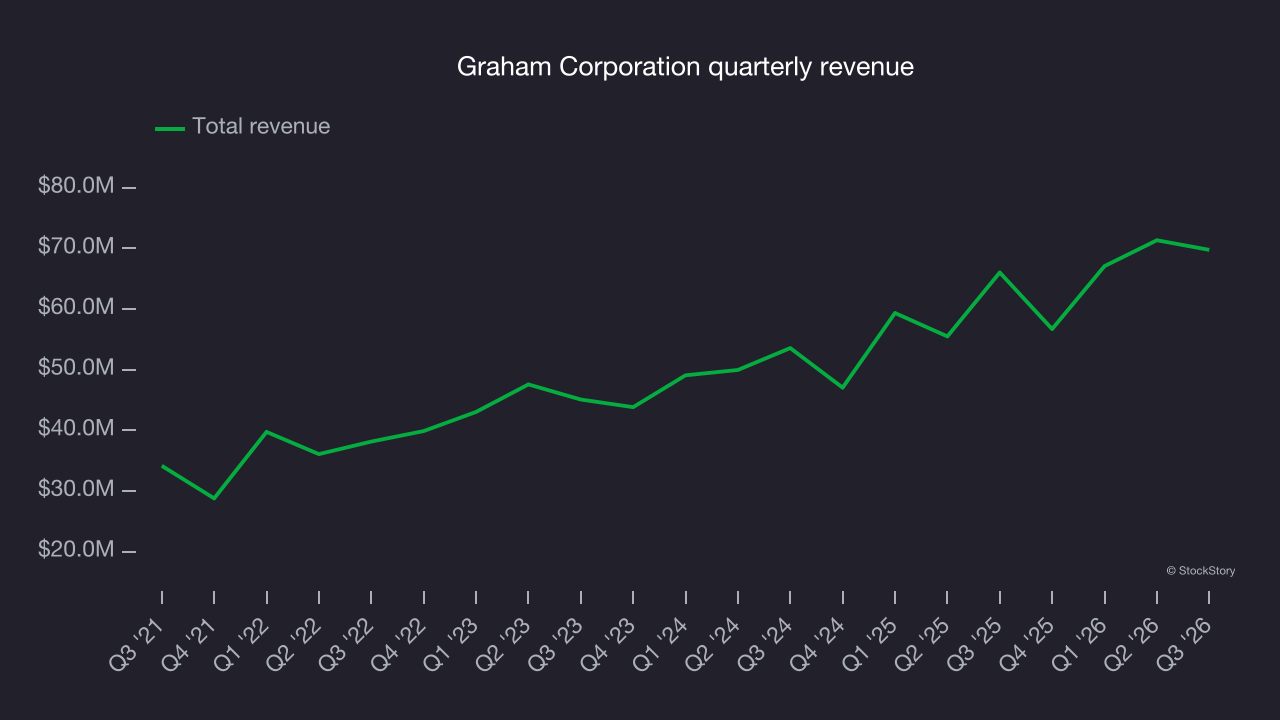
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Graham Corporation’s annualized revenue growth of 16.1% over the last two years is below its five-year trend, but the results still suggest healthy demand. 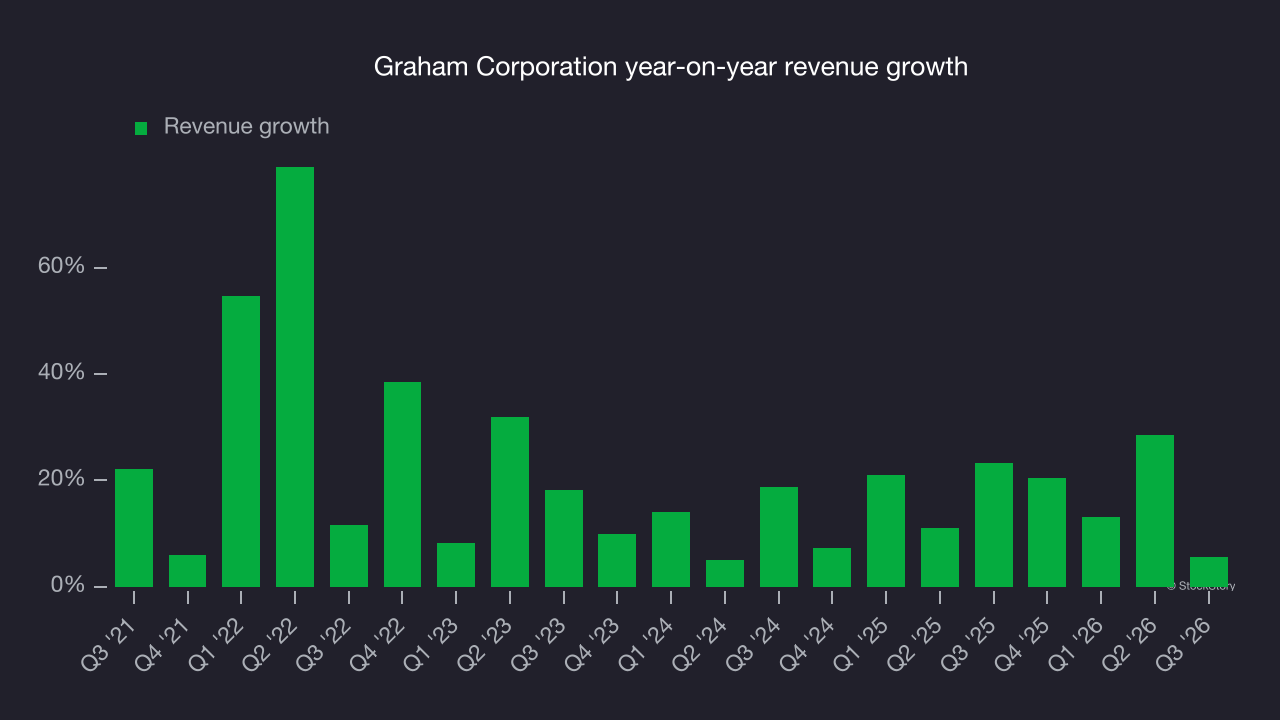
The company’s backlog, or the value of its outstanding orders that have not yet been executed or delivered, provides more detail on its revenue dynamics. Graham Corporation’s backlog reached $561.3 million in the latest quarter and averaged 22.5% year-on-year growth over the last two years. Backlog growth outpaced revenue growth, indicating that the company accumulated more orders than it could fulfill and deferred revenue to the future. This could imply elevated demand for Graham Corporation’s products and services but raises concerns about capacity constraints. 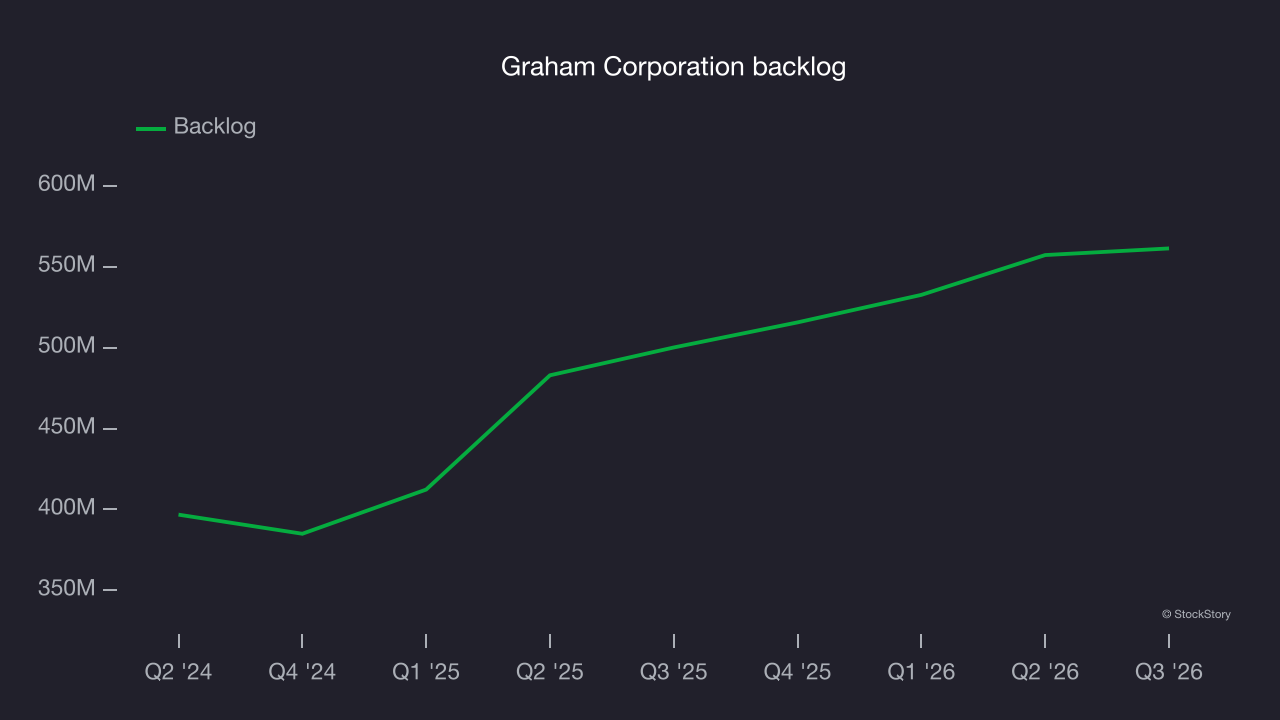
This quarter, Graham Corporation’s revenue grew by 5.7% year on year to $69.76 million, missing Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 17.1% over the next 12 months, according to S&P, similar to its two-year rate. This strong growth projection implies the market sees success for its products and services.
Operating margin
Graham Corporation was profitable over the last five years but held back by its large cost base. Its average operating margin of 3.8% was weak for an industrials business. That outcome is unsurprising given its low gross margin baseline.
On the positive side, Graham Corporation’s operating margin rose by 8.2 percentage points over the last five years, as its revenue growth provided substantial operating leverage.
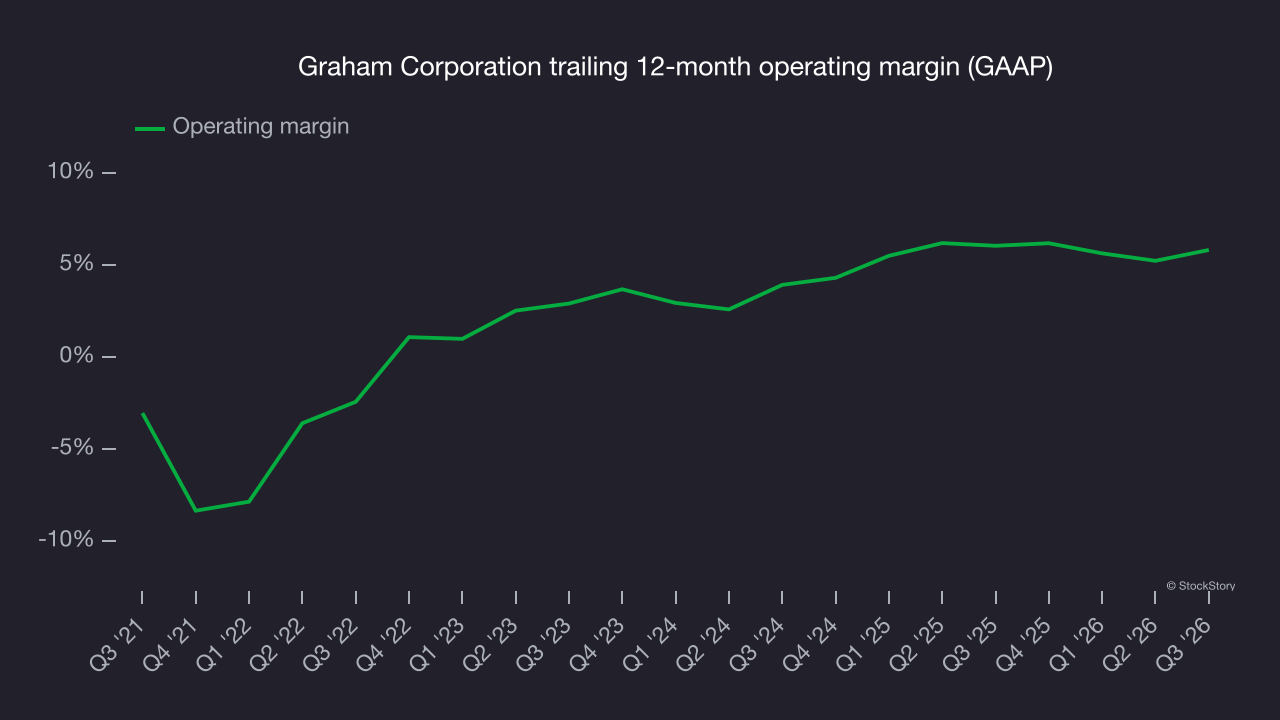
In Q3, Graham Corporation generated an operating margin of 8.4%, up 2.2 percentage points year on year. Its gross margin expanded more than its operating margin, indicating that leverage on its cost of sales was the primary driver of the recent efficiency gains.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Graham Corporation’s full-year EPS flipped from negative to positive over the last five years. This is a good sign and shows it’s at an inflection point.
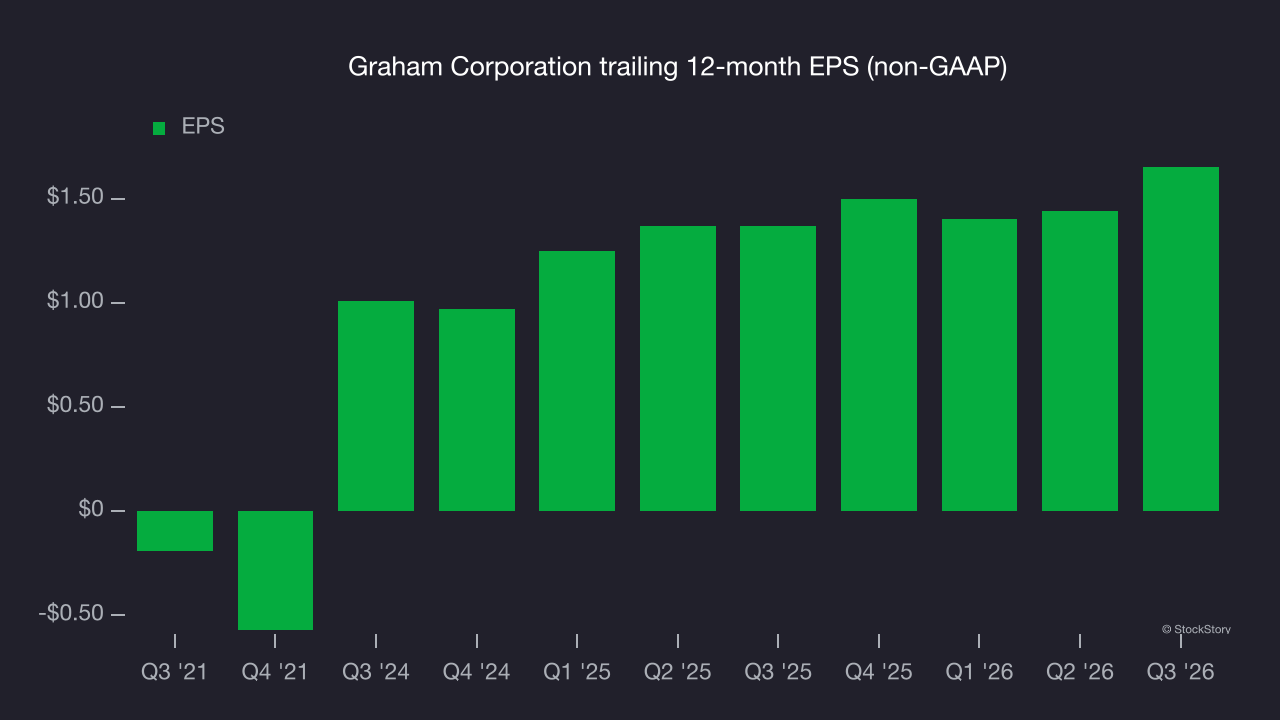
As with revenue, examining EPS over a shorter period can reveal changes in the business.
Graham Corporation’s EPS grew at a strong 27.8% compounded annual growth rate over the last two years, higher than its 16.1% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
A closer look at Graham Corporation’s quality of earnings can clarify its performance. Graham Corporation’s operating margin has expanded over the last two years. This was the most relevant factor (aside from the revenue impact) behind its higher earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, Graham Corporation reported adjusted EPS of $0.52, up from $0.31 in the same quarter last year. This result easily cleared analysts’ consensus estimates. Over the next 12 months, Wall Street expects Graham Corporation’s full-year EPS to grow 22.9% from $1.65 to $2.03, according to S&P.
Key takeaways from Graham Corporation’s Q3 results
Graham Corporation’s Q3 results were mixed, with a sizable EBITDA beat and EPS above Wall Street’s consensus estimates providing key positives. But revenue missed consensus, and full-year revenue guidance was in line with expectations. Shares remained flat at $69.80 immediately after the release.
Graham Corporation reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. An investment decision should also consider valuation and business quality alongside the latest earnings. For more on Graham Corporation, read the full research report here (it’s free).