
US stock outlook | The three major stock index futures had mixed ups and downs Wall Street debated whether AI stocks had oversold and both fell after Qualcomm and Arm's results
Pre-market market trends
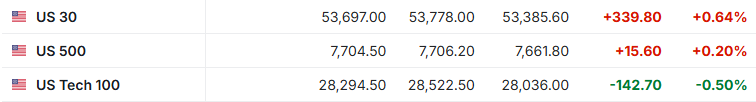
1. Before the US stock market on November 5 (Thursday), futures for the three major US stock indexes had mixed ups and downs. As of press release, Dow futures were up 0.64%, S&P 500 futures were up 0.20%, and NASDAQ futures were down 0.50%.
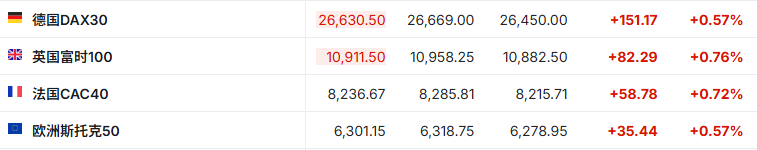
2. As of press release, the German DAX index had risen 0.57%, the UK FTSE 100 had risen 0.76%, France's CAC40 had risen 0.72%, and the European Stoxx 50 had risen 0.57%.
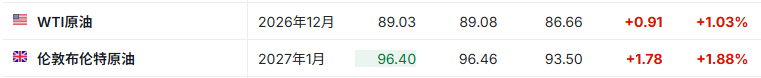
3. As of press release, WTI crude oil rose 1.03% to $89.03 per barrel; Brent crude rose 1.88 percent to $96.40 per barrel.
Market news
The number of US layoffs in October fell 71% year on year, the lowest in the same period since 2023. According to data from the job placement company Challenger, Gray & Christmas Inc., US companies announced 43,994 layoffs last month, down 71% from the same period last year. In the same period last year, the number of October layoffs announced by US companies hit a record high in more than 20 years. According to Challenger data, US employers also said last month that they plan to hire nearly 445,000 people, a year-on-year increase of 57%, the highest level since at least 2009 in October. The growth in recruitment programs was driven entirely by staffing requirements during the peak holiday shopping season.
US Republicans will start voting to impeach Defense Secretary Hegseth as soon as next week. According to reports, many US Republican lawmakers and allies blamed US Secretary of Defense Hegseth for losing the election. They believe Hegseth played a major role in persuading Trump to attack Iran without an exit strategy or a plan to manage the inevitable political consequences. Currently, leaders within the Republican Party, and many of their colleagues, are still unwilling to directly blame Trump for their plight. House Republicans are expected to vote directly to impeach Hegseth within a few days.
The Houthis are demanding 51 billion US dollars, and Saudi Arabia faces difficult choices in seeking a cease-fire. According to reports, after the Houthis attacked Saudi oil tankers in the Red Sea and occupied the strategically important Mander Strait, Saudi Arabia took the initiative to engage with the Houthis in an attempt to understand what costs would have to be paid in order to end the hostilities through negotiations. The response given by the other party was: 51 billion dollars.
Demand for AI servers was strong, and Hon Hai's October revenue surged 46% year over year. Hon Hai announced a 46% year-on-year increase in revenue in October, reaching NT$1.31 trillion (US$39.7 billion), reflecting continued progress in global AI infrastructure construction, and market demand for Nvidia servers is still strong. Analysts said Hon Hai is expected to continue its strong growth momentum in the fourth quarter. Revenue in September increased 38% year over year to a record NT$1.16 trillion, driving third-quarter revenue growth of 47% to NT$3.03 trillion, exceeding market expectations by 7%. With the gradual increase in Vera Rubin shipments and favorable seasonal factors in the IT industry, Hon Hai's growth momentum is expected to continue into the fourth quarter.
Wall Street debated whether AI stocks were oversold, and Goldman Sachs claimed that the Democratic Party won the election or counterpromoted capital spending. In response to the sharp decline in AI concept stocks, institutional opinions were divided. Goldman Sachs believes that AI stocks have been “sold out” recently, valuations have declined markedly, and the position structure has improved after election uncertainty has subsided. Instead, it may prompt tech giants to speed up data center investments ahead of schedule to avoid future regulatory changes; J.P. Morgan suggests concerns about AI financing and commercialization or limits the short-term rebound. At the market level, as the election comes to an end, the high volatility reflected by VIX may be difficult to sustain. If volatility falls rapidly, major indices with nearly half of the AI weight are expected to benefit.
The market digested the midterm election results, and US Treasury yields fell to an eight-week low. On Thursday, long-term US bond yields fell to an eight-week low as investors believed that after the Democratic Party's overall victory in the US midterm elections, fiscal restraints may tighten, thereby benefiting the bond market. According to Tradeweb data, US bond yields for various maturities have generally declined. Among them, 10-year and 30-year US Treasury yields hit eight-week lows of 4.837% and 5.229%, respectively, and then rebounded slightly, but remained declining on the same day. After two-year US Treasury yields fell to a two-month low on Wednesday, the latest trading level was slightly above this low.
Individual stock news
Arm (ARM.US)'s net revenue and profit both exceeded expectations, and the guidance for the next quarter was lackluster and fell nearly 4% before the market. Arm announced its latest financial report for the quarter ending September. Revenue of US$1,443 million increased 27% year over year and adjusted net profit of US$566 million increased 36% year over year, all exceeding Bloomberg's agreed expectations; operating profit margin of 44.2%, licensing and other revenue of US$773 million rose 50% year on year to record high for the same period, and data center royalty doubled again year on year as a core highlight. However, the company's revenue guidance for the next quarter is about US$1.47 billion. Although it is higher than analysts' average expectations of US$1.4 billion, it falls short of some expectations of the highest value of US$1.5 billion, and authorized revenue is also slightly lower than expected. The guideline “only slightly exceeded expectations” disappointed investors. Combined with weak customer Qualcomm's performance outlook, Arm fell nearly 4% before the market.
Qualcomm (QCOM.US) Q4 revenue exceeded expectations, but mobile phone chips plummeted 26%, falling nearly 9% before the market. Qualcomm announced post-market results for the fourth quarter of fiscal year 2026 (ending September 27) on November 4: non-GAAP revenue of US$10.442 billion fell 7% yoy, and non-GAAP earnings of US$2.17 per share fell 28% yoy, all slightly exceeding Wall Street expectations. By business, mobile phone chip revenue plummeted 26% year over year to 5.137 billion US dollars, which was the biggest drag; automotive chip revenue surged 89% year over year to 1.99 billion US dollars, setting a single-quarter record, and IoT revenue increased 4%, partly hedging the contraction of mobile phones. What is really straining the market is guidance: the company expects EPS of 2.15-2.35 US dollars next quarter (median value of 2.25 is lower than the expected 2.32), and warns that supply chain costs such as wafers, encapsulation, and storage will “rise across the board”. At one point, the stock price plummeted by nearly 9% before the market.
AppLovin (APP.US)'s Q3 net revenue and profit both hit record highs, soaring more than 19% before the market. AppLovin handed over a report card that completely exceeded expectations after the market on November 4: third-quarter revenue of US$2.85 billion increased 55% year over year, net profit of US$1,439 million increased 72% year on year, adjusted EBITDA of US$1,842 million increased 59% year on year, and profit margin reached 84%. Revenue, net profit and adjusted EBITDA all hit record highs in a single quarter. Strong AI advertising monetization capabilities continued to be realized. The board of directors simultaneously approved an additional $3.2 billion in repurchase authorizations. By the end of October, the total number of repurchase authorizations reached 3.6 billion US dollars. Thanks to the dual benefits of performance and shareholder returns, the company's pre-market stock price soared by more than 19%, becoming a rare highlight on the AI application side of the day.
Toyota (TM.US) Q3 operating profit surpassed expectations by 34%, and the pre-market increase exceeded the 8% upward guidance. Toyota announced results for the second fiscal quarter (July-September). Operating profit surged 34% year on year to 1.127 trillion yen, far exceeding market expectations of 992 billion yen, the first increase in profit in six quarters; net profit to mother of 449.6 billion yen increased 24% year over year. The increase was mainly due to strong demand for hybrid models (especially in the North American market) and the favorable exchange rate of the yen. Despite declining global sales and weakness in the Chinese market, stable sales in Japan and North America were sufficient to support improved profits. The company drastically raised its annual operating profit forecast to 3.9 trillion yen (previously 3.4 trillion yuan), extended the repurchase limit to 1.3 trillion yen, decided to cancel 1.2 billion shares, and the pre-market stock price rose by more than 8%.
Sony (SONY.US) Q2 operating profit surpassed expectations by 45%, with a pre-market increase of nearly 5%. Sony announced results for the second quarter of fiscal year 2026. Operating profit increased 45% year on year to 622.3 billion yen (about 3.95 billion US dollars), significantly exceeding market expectations; revenue of 3.43 trillion yen increased 10.3% year on year, and net profit to mother of 449.6 billion yen increased 24% year on year. The big box office sales of the “Spider-Man” movie and the strong game business were the main driving forces. The company simultaneously raised its full-year guidance, raising its operating profit forecast from 1.72 trillion yen to 1.87 trillion yen, net profit forecast to 1.33 trillion yen, and raising the annual dividend forecast per share from 25 yen to 35 yen (up 40% year over year). Due to the advantages of both performance and return, the pre-market stock price rose by nearly 5%.
Lumentum (LITE.US) will release earnings after the market tonight, and the continued boom in optical communications is yet to be verified. Lumentum will release its third-quarter results after the market on November 5. The market unanimously expects revenue of US$1,248 billion (up about 138% year over year) and adjusted earnings per share of US$4.19 (up about 307% year over year), and the boom continues. The company's revenue increased 109% year-on-year and gross profit margin of 49.3% last quarter. Increased visibility of high-speed optical components and optical path exchange orders is the core driving force. However, against the backdrop of the overall weakening of the optical communications sector (Lumentum, Maywell, etc. all fell by more than 3%), the market will examine its delivery pace and profit margin resilience, and be wary of downstream pace fluctuations disrupting high base growth.
IREN (IREN.US) will release earnings reports after the market tonight. AI computing power and mining are the two main lines. IREN will announce the third quarter results after the market on November 5. The market expects revenue of US$220 million (up about 48% year on year) and earnings per share of -0.24 US dollars (year-on-year profit and loss). The accounting standards are US-GAAP. As a representative company transforming from Bitcoin mining to AI computing power infrastructure, the company is facing the direct impact of tightening data center regulations after the Democratic Party won the election — the stock price had plummeted by more than 10% on the previous trading day. Investors will focus on the progress of their AI computing power listing, access to electricity resources, and financing capabilities to determine the certainty of the transformation path in the face of policy headwinds.
When Meta (META.US) Eurobonds went public, subscription orders surpassed the face value of 62 billion euros, setting a record high. According to compiled data, the prices of the six term bonds issued by Meta this time all rose on Thursday, and even the purchase price was higher than face value. The banks involved in underwriting completed the issuance of six parts of bonds totaling 9 billion euros (about 10.1 billion US dollars) on Wednesday. The price of each bond was slightly less than 100 euros for every 100 euros in face value. This price increase comes after Meta's record bond issuance. The transaction order book reached 62 billion euros, far exceeding the 31 billion euro record set by Budweiser InBev ten years ago.
Microsoft (MSFT.US) refused to reach a tens of billion dollar expansion agreement with the British AI startup NScale. According to reports, NScale, the UK's highest-valued AI startup, failed to reach a potentially tens of billion dollars of new agreement with Microsoft, which placed its plans to achieve its $35 billion listing target facing a new test. According to three people familiar with the matter, Microsoft has refused to more than double the size of the existing data center computing power lease contract, and the relevant facilities are located in Texas, USA. This means that Nscale must find new customers for the data center or risk losing billions of dollars in future revenue.
Apple (AAPL.US) is rumored to be cutting its internal AI budget. According to reports, Apple is cutting the budget for employees to use artificial intelligence (AI) as part of cost reduction measures, although the company is still seeking to place AI at the core of its own operations. According to people familiar with the matter, Apple quietly lowered the daily spending limit for some engineers using AI models from $300 to $200 last month. According to these sources, Apple is currently planning to further cut the budget of some engineering teams, and the daily quota may be as low as $100.
Goldman Sachs and Apollo agreed to sell SpaceX (SPCX.US) $40 billion in AI chip financing. According to people familiar with the matter, the two companies have begun to reach out to potential buyers of this multi-stage financing. SpaceX has said that the deal structure aims to keep debt off SpaceX's balance sheet and is the largest GPU financing arrangement on record. People familiar with the matter said that in some cases, investors are required to purchase shares of up to 500 million US dollars before the official syndicated distribution process begins in order to complete the transaction as soon as possible. The syndicated distribution program was launched soon.
Key economic data and event forecasts
21:30 Beijing time: Number of jobless claims in the US until October 31 at the beginning of the week
21:30 Beijing time: 2026 FOMC voting committee and Cleveland Federal Reserve Chairman Hamak delivered a speech on stablecoins and safe-haven currency exchange issues
22:10 Beijing time: 2027 FOMC voting committee and Richmond Federal Reserve Chairman Barkin delivered a speech
The next day at 00:30 Beijing time: 2027 FOMC voting committee and Chicago Federal Reserve Chairman Goulsby delivered a speech
At 02:00 Beijing time the next day: ECB President Lagarde and Governing Council Member Dolentz deliver speeches
The next day at 05:00 Beijing time: Canadian Finance Minister Shang Pengfei announces the federal budget
08:00 Beijing time the next day: 2026 FOMC voting committee and Dallas Federal Reserve Chairman Logan delivered a speech
Performance Forecast
Friday morning: IREN, Cloudflare (NET.US), Airbnb (ABNB.US)
Friday pre-market: Moderna (MRNA.US)