
Taiwan Semiconductor Manufacturing (TSM) Pulls Back As ARK Sale Revives The Valuation Debate
Cathie Wood’s ARK Invest recently sold about 56,000 shares of Taiwan Semiconductor Manufacturing (NYSE:TSM), a trade worth roughly US$24.6 million, after a reported gain of more than 75% since July 2026.
Taiwan Semiconductor Manufacturing’s share price has cooled recently, with the stock down about 10% over the past week and roughly 19% over the past month. It still holds a 24% year to date share price gain and a 36% one year total shareholder return, which points to longer term momentum even as near term sentiment softens.
Scan how Taiwan Semiconductor Manufacturing fits into the wider chip story by weighing it up against a curated 53 AI infrastructure stocks that could be driving the next leg of demand.
Taiwan Semiconductor Manufacturing now trades at a discount to both analyst targets and some fair value estimates after a sharp pullback. Is that caution a warning sign or an opportunity on the recent slide?
Most Popular Narrative: 5% Overvalued
Taiwan Semiconductor Manufacturing last closed at $395.75, a touch above the most followed fair value estimate of $378.29 that uses an 11.51% discount rate, so the narrative frames today’s price as paying a premium for quality rather than buying clear-cut value.
Here is the exercise that settles most arguments. Instead of asking what TSMC is worth, invert. Ask what has to happen for $417.52 to be the right price.
Run the machine backwards and the answer is a 13.2% compound annual revenue growth rate for ten consecutive years, on a path where margins fade from today''s records as management says they will. Strip out inflation and that is roughly 10.7% real growth, every year, for a decade, from a company already doing $171 billion of revenue.
See why 141 investors see Taiwan Semiconductor Manufacturing as 5% overvalued.
Result: Fair Value of $378.29 (OVERVALUED)
Still, Taiwan Semiconductor Manufacturing faces two clear pressure points: elevated geopolitical risk around Taiwan and rising overseas costs that could weigh on future profitability.
Find out about the key risks to this Taiwan Semiconductor Manufacturing narrative.
Another View: What Multiples Say About Taiwan Semiconductor Manufacturing
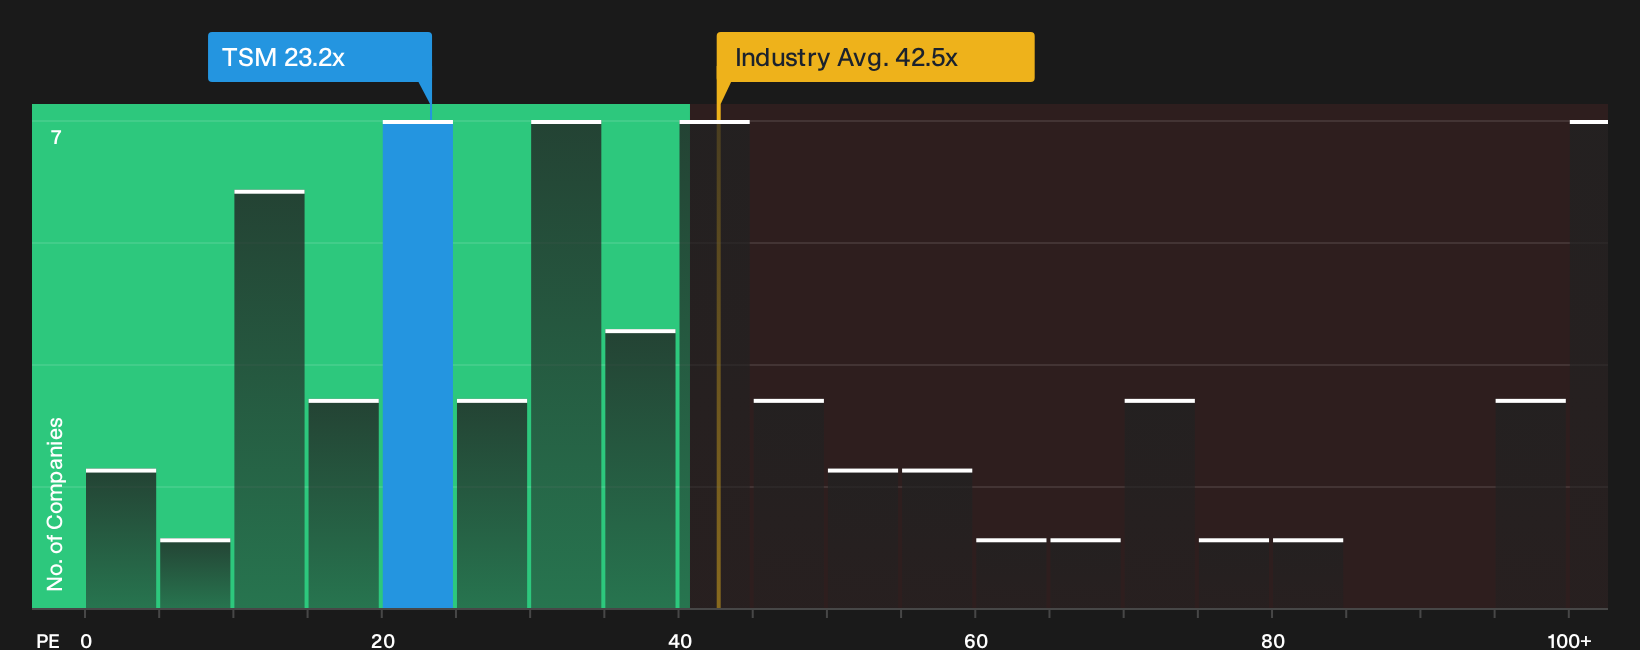
That fair value narrative paints Taiwan Semiconductor Manufacturing as about 5% over where the most followed estimate lands, yet the market is not pricing it like a stretched story. At a P/E of 23.2x versus 42.5x for the US semiconductor group and 44.9x across peers, and against a fair ratio of 34.8x, the stock trades on a much lower earnings tag than many rivals. That gap cuts both ways for investors because it can signal either a margin of safety on quality or a market that keeps a permanent discount on geopolitical and concentration risk. Which side of that trade do you think dominates over a full cycle?
To see how that earnings multiple stacks up in detail against peers and the fair ratio the market could move toward, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Questions about whether Taiwan Semiconductor Manufacturing is stretched or still reasonable on this pullback will only be settled by your own homework on the numbers. Act quickly; weigh both the risks and the upside; then ground your view in the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Taiwan Semiconductor Manufacturing?
If Taiwan Semiconductor Manufacturing has sharpened your focus on quality, do not stop here. Cast a wider net with other opportunities that could suit your approach.
- Target potential mispricing by scanning a curated universe of companies through the 35 high quality undervalued stocks that line up solid fundamentals with appealing valuations.
- Strengthen your income game by reviewing the 5 dividend fortresses that groups higher yielding payouts with an emphasis on resilience.
- Dial down portfolio stress by filtering for the 31 resilient stocks with low risk scores which highlights businesses scored for more durable balance sheets and steadier profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com